Financials · NYSE: USB
U.S. Bancorp: how the business works
U.S. Bancorp owns U.S. Bank, a lender and card payments company in 26 states with $28.7 billion of net revenue in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow U.S. Bancorp
Email me when U.S. Bancorp's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
U.S. Bancorp · Minneapolis, Minnesota
Updated for Q3 FY2026 · checked
- Total net revenue, FY2025 (taxable-equivalent)
- $28.7B
- Net income to common shareholders, FY2025
- $7.19B
- Deposits, Dec 31, 2025
- $522.2B
- Branches, Dec 31, 2025
- 2,075
- Employees, Dec 31, 2025
- 68,520
The short version
U.S. Bancorp in 5 points
1 · What it sells
U.S. Bancorp owns U.S. Bank, with 2,075 branches in 26 states, and had $28.7 billion of total net revenue in FY2025.
2 · Who pays it
U.S. Bancorp does not report revenue by customer; in FY2025, borrowers paid $30,970 million of interest income and fees added $11,891 million.
3 · What it keeps from $100
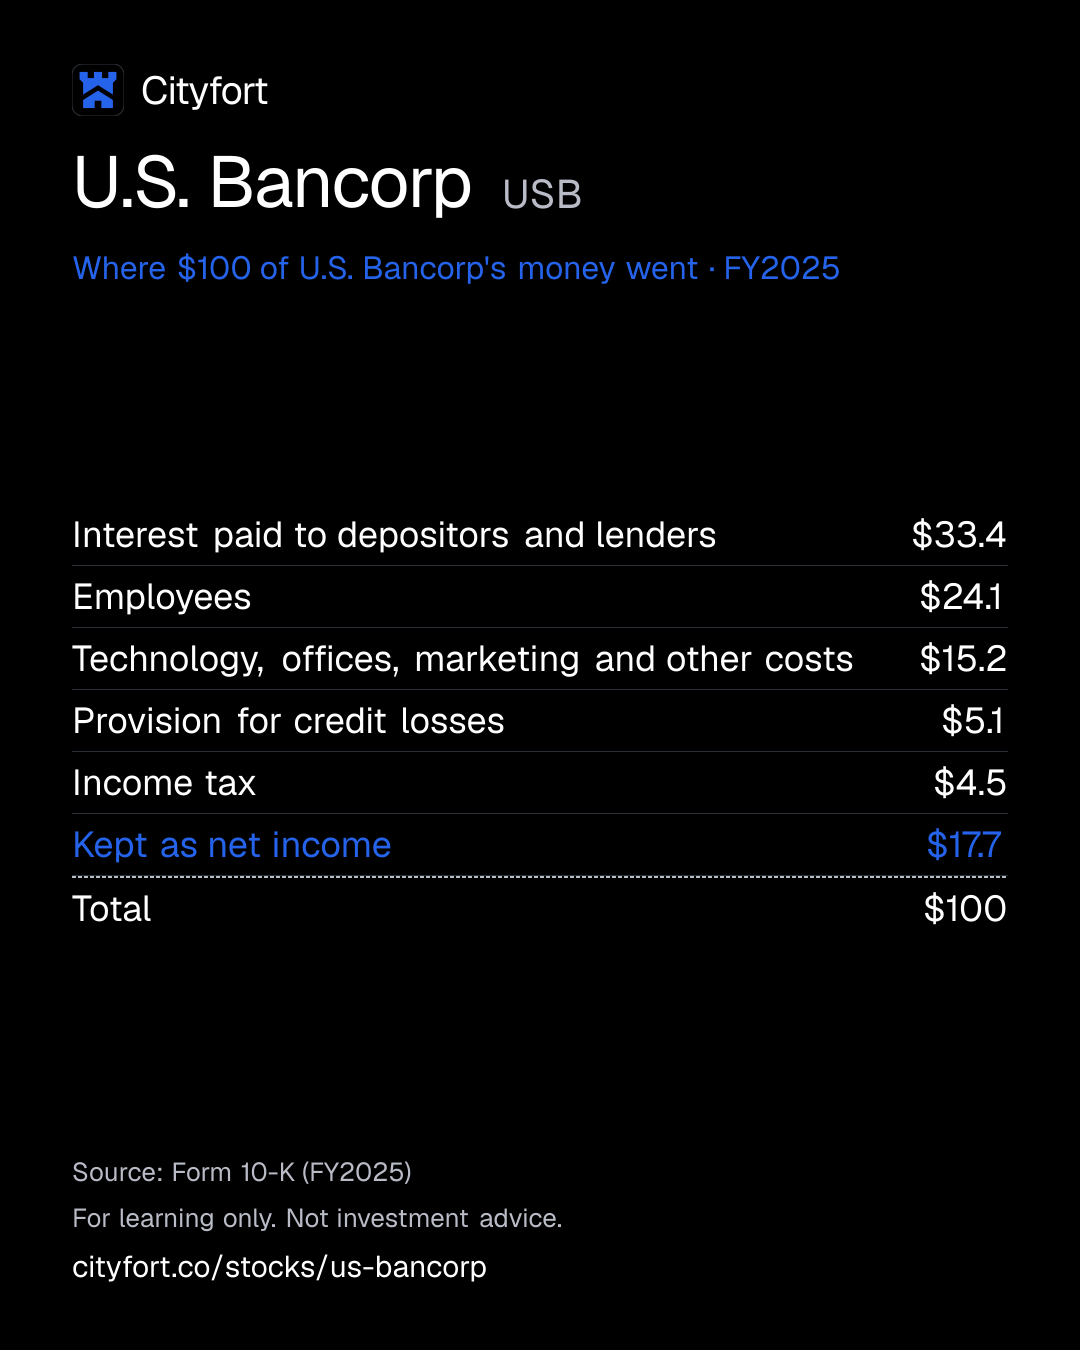
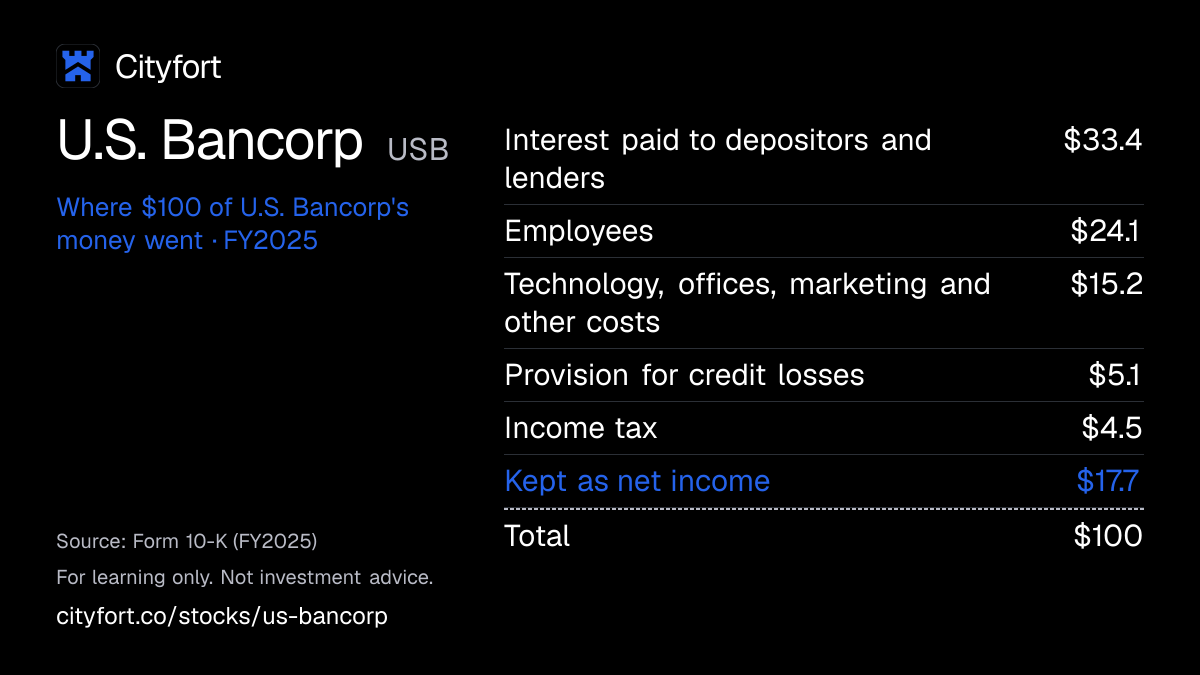
Of every $100 that came in during FY2025, U.S. Bancorp paid $33.4 in interest and $24.1 for employees and kept $17.7 as net income; pre-provision profit (revenue minus operating costs) was $11.7 billion.
4 · Where the operating profit comes from
Of FY2025 segment net income, Wealth, Corporate, Commercial and Institutional Banking earned $4,626 million, Consumer and Business Banking $1,723 million and Payment Services $1,282 million.
5 · The one thing to watch
Payment Services set aside $594 million for credit losses in Q3 FY2026, against $409 million a year earlier.
Sources: From U.S. Bancorp's FY2025 10-K and Q3 FY2026 10-Q · checked
01Where $100 of a bank's money goes · FY2025
Where does $100 of U.S. Bancorp's money go?
U.S. Bancorp · FY2025
Receipt for every $100
| Interest paid to depositors and lenders | $33.4 |
|---|---|
| Employees | $24.1 |
| Technology, offices, marketing and other costs | $15.2 |
| Provision for credit losses | $5.1 |
| Income tax | $4.5 |
| Kept as net income | $17.7 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Of every $100 that came in (interest income of $30,970 million plus noninterest income of $11,891 million = $42,861 million), each line = line ÷ $42,861 million × 100. Net income includes $26 million for noncontrolling interests and $376 million for preferred stockholders and other items.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report earnings, explained in 5 points.
No tips. Unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does U.S. Bancorp do?
U.S. Bancorp lends out deposits at higher rates than it pays on them, and charges fees. It kept $17.7 of every $100 as net income in FY2025.
- Borrowers paid $30,970 million of interest income in FY2025, and fees from cards, payments, trust and capital markets added $11,891 million.
- Interest paid on deposits and borrowings took $33.4 of every $100 that came in, and employees took $24.1.
03Who pays it
Who pays U.S. Bancorp?
U.S. Bancorp does not disclose how much each type of customer pays.
Borrowers
Companies, property owners, home buyers and card holders pay interest on loans. Interest income, including on securities, was $30,970 million in FY2025.
Merchants, card holders and businesses
They pay card and payment fees: card revenue $1,735 million, corporate payment products $765 million and merchant processing $1,792 million in FY2025.
Wealthy clients and institutions
They pay trust and investment management fees, which were $2,869 million in FY2025.
Companies raising money
They pay capital markets fees, which were $1,633 million in FY2025.
Account holders
People and businesses pay service charges on accounts, which were $1,302 million in FY2025.
How spread out the customers are
The FY2025 10-K does not report revenue by customer. Within commercial real estate loans, borrowers in California held 36.6% at Dec 31, 2025.
04How it makes money
How does U.S. Bancorp make money?
It earns a spread on the deposits it lends out, plus fees from cards, payments and wealth.
U.S. Bancorp pays interest on its deposits and earns more on loans and securities. In FY2025 that gap, called net interest income, was $16,649 million, and fees added $11,891 million.
Noninterest expense per $100 of revenue (company efficiency ratio)
$66.7$58.6
FY2023 to FY2025
- Collects deposits from people and businesses
- Lends and buys securities at higher rates
- Earns fees from cards, payments, trust and capital markets
- Pays staff, technology and loan losses
- Keeps the rest as profit and capital for more lending
↺ Step 5 feeds back into step 1.
05Business segments · FY2025
Which businesses make up U.S. Bancorp?
Wealth, Corporate, Commercial and Institutional Banking
42.2%Lending, payments, capital markets and wealth management for companies, institutions and wealthy clients; net income $4,626 million in FY2025.
Revenue $12.1B ($12,083M)
Consumer and Business Banking
31%Branch, mortgage and consumer lending for households and small businesses; net income $1,723 million in FY2025.
Revenue $8.9B ($8,873M)
Payment Services
25.8%Credit and debit cards, corporate cards and merchant processing; net income $1,282 million in FY2025.
Revenue $7.4B ($7,407M)
Treasury and Corporate Support
1%Investment securities, funding, capital and central costs; revenue was negative $953 million in FY2024.
Revenue $293M
How the mix changed
- Wealth, Corporate, Commercial and Institutional Banking
- Consumer and Business Banking
- Payment Services
- Treasury and Corporate Support
Revenue by segment, FY2024 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has U.S. Bancorp done?
Net interest income
$16.6BFY2025
Net interest income was $16,649 million in FY2025, up from $16,289 million in FY2024 but below $17,396 million in FY2023.
US$ · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net income
$7.2BFY2025
Net income applicable to U.S. Bancorp common shareholders rose to $7,194 million in FY2025 from $5,051 million in FY2023.
US$ · after the provision for credit losses and tax
See the yearly numbers
See the quarterly numbers
Net interest margin
2.72%FY2025
The net interest margin, on the company's taxable-equivalent basis, was 2.72% in FY2025 and 2.84% in Q3 FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
0.57%FY2025
Net charge-offs were 0.57% of average loans in FY2025, and the allowance for credit losses was 2.03% of loans at year end.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the yearly numbers
See the quarterly numbers
See all yearly numbers
† Restated by the company. Net income and EPS here are both for common shareholders, after preferred dividends. Net income attributable to U.S. Bancorp, before preferred dividends, was $7,570 million in FY2025.
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (Fiscal year ends Dec 31 (calendar year)).
- Net interest margin, return on assets, return on equity and return on tangible common equity are the company's own figures from its 10-Ks; return on tangible common equity is a company-defined measure. The efficiency ratio here is noninterest expense ÷ (net interest income + noninterest income), a Cityfort calculation from the FY2023 and FY2025 10-Ks. The company's own ratio, on its taxable-equivalent basis, was 58.6% in FY2025, 62.3% in FY2024 and 66.7% in FY2023.
- The allowance shown is the total allowance for credit losses, including unfunded commitments, the base of the company's own ratio. The allowance for loan losses alone was 1.94% of loans at Dec 31, 2025 (Cityfort calculation from the FY2025 10-K).
- The year-end noninterest-bearing deposit figure for FY2021 was not collected for this page.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100 · Fiscal years that don't end in December: Nvidia's FY2027 explained
Sources (11)
- FY2023 Form 10-K, MD&A and financial statements
- FY2025 Form 10-K, MD&A and financial statements
- FY2024 Form 10-K, MD&A and financial statements
- Q1 2025 earnings release
- Q2 2025 earnings release
- Q4 2024 earnings release
- Q3 2025 earnings release
- Q4 2025 earnings release
- Q1 2026 earnings release
- Q2 2026 earnings release
- Q3 2026 earnings release (8-K Ex. 99.1)
07Who runs it
Who runs U.S. Bancorp, and did they deliver?
Gunjan Kedia
Chairman and Chief Executive Officer · since 2025
CEO since April 2025 and President since May 2024; signed the Q3 2026 release as Chairman and CEO.
John C. Stern
Vice Chair and Chief Financial Officer · since 2023
CFO since September 2023.
Jodi L. Richard
Vice Chair and Chief Risk Officer · since 2018
Stephen L. Philipson
Vice Chair, Head of Wealth, Corporate, Commercial and Institutional Banking · since 2024
James L. Chosy
General Counsel · since 2013
Venkatachari Dilip
Chief Information and Technology Officer · since 2018
What they said, and what happened
3 too early to tell
Said on Oct 15, 2026
FY2026 total net revenue up 8% to 9% from $28.7 billion in FY2025, or 6% to 7% without BTIG.
Too early to tellWhat happened
FY2026 results are not yet reported.
Said on Oct 15, 2026
Return on assets of 1.15% to 1.35% in 2026 and 2027.
Too early to tellWhat happened
Return on assets was 1.25% in Q3 FY2026.
Said on Oct 15, 2026
BTIG expected to add about $200 million of quarterly net revenue.
Too early to tellWhat happened
The Q2 2026 release says BTIG added about $98 million of fee revenue in Q2 FY2026, which included one month after the Jun 1 closing.
08What could go wrong
What could go wrong for U.S. Bancorp?
- Concentration
Commercial real estate loans
Commercial real estate loans were $48,920 million, 12.5% of loans, at Dec 31, 2025. California held 36.6% of them, and office buildings 8.8%.
Watch Nonperforming commercial real estate loans ($518 million at Dec 31, 2025) in each 10-Q.
- Other
Credit card losses
Credit card charge-offs were $1,461 million in FY2025, up from $1,014 million in FY2023. Payment Services set aside $594 million for credit losses in Q3 FY2026, against $409 million a year earlier.
Watch The net charge-off ratio each quarter (0.51% in Q3 FY2026).
- Cash and liquidity
Uninsured deposits
$273.5 billion of deposits were not covered by any deposit insurance program at Dec 31, 2025, up from $259.9 billion a year earlier. Total deposits were $522,216 million.
Watch Uninsured deposits in the FY2026 10-K and the average liquidity coverage ratio (106.5% in Q4 2025).
- Pricing
Interest rates and deposit costs
The FY2025 10-K lists changes in interest rates among its risks. Interest paid on deposits was $10,151 million in FY2025, and the net interest margin was 2.72%, down from 2.90% in FY2023.
Watch Net interest margin each quarter (2.84% in Q3 FY2026).
- Regulation
Capital rules and interchange limits
The FY2025 10-K lists changes to capital and liquidity rules and limits on interchange fees among its risks. Federal regulators proposed capital rule changes in March 2026; the Q3 FY2026 10-Q says adoption "is expected to be favorable to the Company".
Watch Final capital rules and the CET1 ratio (10.8% at Sep 30, 2026).
- Legal
Mortgage-backed securities trustee lawsuits
Since 2011, investors have sued U.S. Bank National Association as trustee for mortgage-backed securities trusts, alleging it failed to enforce loan repurchase obligations. The FY2025 10-K says plaintiffs generally seek unspecified damages.
Watch The litigation note in each 10-Q.
- Execution
Integrating BTIG
U.S. Bancorp bought BTIG on Jun 1, 2026 for about $395 million in cash and 6.6 million shares. The Q3 FY2026 10-Q says up to $275 million more in cash may follow over three years, subject to performance conditions. Management said on Oct 15, 2026 it expects BTIG to add about $200 million of quarterly net revenue.
Watch Capital markets fees in each quarterly release.
- Competition
Competition from fintechs
The FY2025 10-K says competition has increased from fintechs and other firms that are not subject to the same rules as banks.
Watch Card and merchant processing fees in each quarterly release.
09Supporters vs. critics
What do supporters and critics point to?
What supporters point to
- The company's efficiency ratio (costs per $100 of revenue) fell to 58.6 in FY2025 from 66.7 in FY2023.
- Net income applicable to U.S. Bancorp common shareholders rose to $7,194 million in FY2025 from $5,051 million in FY2023.
- Noninterest income reached $3,480 million in Q3 FY2026, up from $3,078 million in Q3 FY2025.
- The net interest margin was 2.84% in Q3 FY2026, up from 2.75% a year earlier.
- Dividends per common share rose every year from $1.76 in FY2021 to $2.04 in FY2025.
What critics point to
- $273.5 billion of deposits were not covered by any deposit insurance program at Dec 31, 2025.
- Credit card charge-offs were $1,461 million in FY2025, up from $1,014 million in FY2023.
- Payment Services net income attributable to U.S. Bancorp fell to $175 million in Q3 FY2026 from $255 million a year earlier.
- Commercial real estate loans were $48,920 million at Dec 31, 2025, and California held 36.6% of them.
- Net income applicable to U.S. Bancorp common shareholders of $7,194 million in FY2025 was below the $7,605 million of FY2021.
10What to watch next
What should you watch next at U.S. Bancorp?
Next event
Q4 FY2026 results
Date not announced yet.
Full-year revenue
Management said on Oct 15, 2026 that it expects FY2026 total net revenue up 8% to 9% from $28.7 billion. The Q4 FY2026 release will show the full year.
BTIG's contribution
U.S. Bancorp bought BTIG on Jun 1, 2026. On Oct 15, 2026, management said it expects BTIG to add about $200 million of quarterly net revenue.
Card credit losses
Payment Services set aside $594 million for credit losses in Q3 FY2026, against $409 million a year earlier.
Capital rules
Federal regulators proposed capital rule changes in March 2026. U.S. Bancorp's CET1 capital ratio was 10.8% at Dec 31, 2025.
11Key facts
Key facts about U.S. Bancorp
- What does U.S. Bancorp do?
- U.S. Bancorp owns U.S. Bank, a national bank with 2,075 branches in 26 states at Dec 31, 2025. It takes deposits, makes loans, processes card payments and manages money for wealthy clients and institutions.
- How does U.S. Bancorp make money?
- U.S. Bancorp earns more interest on loans and securities than it pays on deposits. In FY2025 that net interest income was $16,649 million, and fees added $11,891 million.
- Who are U.S. Bancorp's customers?
- U.S. Bancorp serves companies, institutions, wealthy clients, households, small businesses, card holders and merchants. In FY2025, Wealth, Corporate, Commercial and Institutional Banking brought in 42.2% of segment revenue, Consumer and Business Banking 31% and Payment Services 25.8%.
- How big is U.S. Bancorp?
- U.S. Bancorp had total net revenue of $28,656 million (taxable-equivalent basis) and net income applicable to common shareholders of $7,194 million in FY2025. Deposits were $522,216 million at Dec 31, 2025.
- Who owns U.S. Bancorp?
- U.S. Bancorp's 23 directors and executive officers held about 0.2% of its shares at Feb 2, 2026 (Cityfort calculation from the 2026 proxy statementThe yearly filing about shareholder votes, the board and executive pay. Learn more and the Q3 FY2026 10-Q). The Vanguard Group reported 8.7% and BlackRock 7.0% in Schedule 13GA filing by anyone who owns more than 5% of a company's shares and does not seek control. Learn more amendments filed in Feb 2024 and Jan 2024.
- Does U.S. Bancorp pay a dividend?
- U.S. Bancorp declared dividends of $2.04 per common share in FY2025, up from $1.76 in FY2021. It repurchased $489 million of common stock in FY2025.
Terms on this page
- Allowance for credit losses
- CET1 ratio
- Dividend payout ratio
- Earnings per share (EPS)
- Efficiency ratio
- Market cap
- Net charge-offs
- Net interest income and margin
- P/E ratio
- Stock buyback
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does U.S. Bancorp sell?
Loans
Loans to companies, commercial property owners, home buyers and card holders. Total loans were $391,335 million at Dec 31, 2025, and commercial loans were the largest group at 39.4%.
Deposit accounts
Checking, savings, money market and time deposit accounts for people and businesses. Deposits were $522,216 million at Dec 31, 2025.
Cards and payments
Credit and debit cards, corporate and government cards, and merchant processing, which means handling card payments for shops through its subsidiary Elavon. Merchant processing fees were $1,792 million in FY2025.
Wealth and trust
Trust, investment management and brokerage for wealthy families and institutions. Trust and investment management fees were $2,869 million in FY2025.
Capital markets
Helping companies raise money, hedge and trade. Capital markets fees were $1,633 million in FY2025. That was before it bought BTIG, a broker-dealer, on Jun 1, 2026.
Think of it like this
A bank works like a shop for money: it pays interest to get deposits and charges a higher rate when it lends them out.
What it does
- Does: Takes deposits; all of them sit in its bank, U.S. Bank National Association
- Does: Lends to companies, property owners, home buyers and card holders
- Does: Processes card payments for merchants
- Does: Holds and manages investments for wealthy clients and institutions
What it does not do
- Does not: Have branches in every state: its 2,075 branches are in 26 states
- Does not: Live on interest alone: fees and other noninterest income were $11,891 million in FY2025, on top of $16,649 million of net interest income
13How the money flows
13How the money flows · FY2025
How does money flow through U.S. Bancorp?
Money in
- Interest earned on loans, securities and other assets$31.0B
- Fees and other noninterest income$11.9B
The company
U.S. Bancorp
$42.9B came in
Money out
- Interest paid to depositors and lenders$14.3B
- Employees$10.3B
- Technology, offices, marketing and other costs$6.5B
- Provision for credit losses$2.2B
- Income tax$1.9B
- Net income$7.6B
- Borrowers and securities paid U.S. Bancorp $30,970 million of interest in FY2025.
- Fees from cards, payments, trust, capital markets and accounts added $11,891 million.
- Interest paid to depositors and lenders took $14,321 million, and staff cost $10,327 million.
- Other running costs were $6,510 million, money set aside for loan losses $2,186 million and income tax $1,921 million.
- Net income was $7,596 million, of which $26 million belonged to outside holders of subsidiaries.
14What it needs to run
14What it needs to run
What does U.S. Bancorp need to run?
Deposits
Deposits fund most of its lending: $522,216 million at Dec 31, 2025, and 16.1% of them paid no interest.
Capital
Capital is the cushion a bank keeps against losses. Its CET1 capital, the core measure regulators use, was $51,665 million, or 10.8% of risk-weighted assets, at Dec 31, 2025.
Branches and ATMs
It had 2,075 branches and 4,428 ATMs at Dec 31, 2025.
People
It had 68,520 employees at Dec 31, 2025; compensation and benefits cost $10,327 million in FY2025.
Technology
Technology and communications cost $2,211 million in FY2025, up from $2,049 million in FY2023.
15Competitors and what protects it
15Competitors and what protects it
Who does U.S. Bancorp compete with?
JPMorgan Chase & Co.
NYSE: JPM
Named in the 2026 proxy peer group of banks offering broadly comparable retail and commercial banking services.
Bank of America Corporation
NYSE: BAC
Named in the 2026 proxy peer group of banks offering broadly comparable retail and commercial banking services.
Wells Fargo & Company
NYSE: WFC
Named in the 2026 proxy peer group of banks offering broadly comparable retail and commercial banking services.
The PNC Financial Services Group
NYSE: PNC
Named in the 2026 proxy peer group of banks offering broadly comparable retail and commercial banking services.
Truist Financial Corporation
NYSE: TFC
Named in the 2026 proxy peer group of banks offering broadly comparable retail and commercial banking services.
What protects the business
Each strength is scored 1 (weak) to 5 (strong) for the business, with the reason. It is not a rating of the share.
- Deposit base4 of 5
Deposits were $522,216 million at Dec 31, 2025, against $391,335 million of loans, and $84,116 million of them paid no interest.
- Payments business3 of 5
Payment Services earned $7,407 million of revenue in FY2025, including merchant processing fees of $1,792 million.
- Fee income3 of 5
Noninterest income was $11,891 million in FY2025, on top of $16,649 million of net interest income.
Weak spot
Uninsured deposits
$273.5 billion of deposits were not covered by any deposit insurance program at Dec 31, 2025, up from $259.9 billion a year earlier.
16Where growth could come from
16Where growth could come from
Where could U.S. Bancorp's growth come from?
In the Q3 2026 earnings presentation on Oct 15, 2026, management guided FY2026 total net revenue up 8% to 9% from $28.7 billion in FY2025, or 6% to 7% without BTIG. It also set targets for 2026 and 2027: a 1.15% to 1.35% return on assets and a return on tangible common equity in the 'high teens'.
Capital markets and BTIG
NewCapital markets revenue +69.3%, Q3 FY2026 vs Q3 FY2025
U.S. Bancorp bought BTIG, a broker-dealer, on Jun 1, 2026. CEO Gunjan Kedia said in the Q3 2026 release that a full quarter of BTIG drove the rise.
Status: New, recently announced.
Fee revenue
WorkingNoninterest income $3,480 million in Q3 FY2026, up from $3,078 million
Total fee revenue, which leaves out securities gains and losses, was $3,545 million in Q3 FY2026, up 14.9% from $3,085 million.
Status: Working, on track against what the company said.
Net interest margin
Working2.84% in Q3 FY2026, up from 2.75% in Q3 FY2025
Net interest income was $4,468 million in Q3 FY2026, up from $4,222 million a year earlier.
Status: Working, on track against what the company said.
Payments
MixedPayment Services revenue $1,868 million in Q3 FY2026, up from $1,754 million
Revenue grew, but the segment net income attributable to U.S. Bancorp fell to $175 million from $255 million as its provision for credit losses rose to $594 million.
Status: Mixed, partly on track.
Small business banking
NewBusiness Essentials cards launched, Q3 FY2026
In Q3 FY2026 it took on a small business credit card relationship and launched Business Essentials and Business Essentials Plus cards.
Status: New, recently announced.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
17The company's own measures (non-GAAP)
17The company's own measures · FY2025
What do U.S. Bancorp's own measures show?
Official (GAAP): Return on average common equity, FY2025
13.0%
Company's own measure: Return on average tangible common equity (ROTCE), FY2025
18.1%
Leaves goodwill and other intangible assets out of common equity, as the company defines it.
Official (GAAP): Book value per share, Dec 31, 2025
$37.55
Company's own measure: Tangible book value per share, Dec 31, 2025
$29.12
Common equity minus goodwill and other intangible assets, per share.
Official (GAAP): Net interest income, FY2025
$16.6B
Company's own measure: Net interest income, taxable-equivalent basis, FY2025
$16.8B
Adds $116 million so tax-exempt interest is shown as if it were taxed; the company's net interest margin and total net revenue use this basis.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
18Financial strength: capital, loan losses, deposits
18Financial strength · FY2025
How strong is U.S. Bancorp's balance sheet?
- Loans made$391.3B
- Deposits taken$522.2B
- of which pay no interest$84.1B
Loans were 74.9% of deposits at the end of FY2025 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 16.1% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 10.8%
- common equity capital as a share of risk-weighted assets (Basel III standardized approach); regulators set a minimum
- Allowance for credit losses
- $7.9B
- money set aside for expected loan losses: 2.03% of loans
- Net charge-offs
- $2.2B
- loans written off, minus recoveries: 0.57% of average loans
- Efficiency ratio
- 59.0%
- $ of noninterest expense per $100 of revenue (net interest income + noninterest income)
- Return on assets
- 1.12%
- net income as % of average total assets
- Return on equity
- 13.0%
- net income as % of average common equity
- Return on tangible common equity
- 18.1%
- the company's own measure (non-GAAP): equity without goodwill and other intangibles
Figures at the end of FY2025, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
19Who owns it
19Who owns it · ownership as of Feb 2, 2026
Who owns U.S. Bancorp?
- Officers and directors (as a group), shares
- 0.2%
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes
20What it does with profit
20What it does with profit
What does U.S. Bancorp do with its profit?
Dividend per share
$2.04FY2025
Dividend paid for each share, by financial year.
$ per share
See the numbers
Buyback · Dec 31, 2025
FY2025: $489 million of common stock repurchased. $4,389 million remained at Dec 31, 2025 under the $5.0 billion program authorized on Sep 12, 2024.
$489M
21Governance signals
21Governance signals
What do U.S. Bancorp's governance filings show?
- Auditor
- Ernst & Young LLP, since 2003
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy says U.S. Bancorp did ordinary-course business with directors, officers, BlackRock and Vanguard on normal terms. It paid about $75 million in 2025 to Microsoft, where director Yusuf I. Mehdi is an executive; the board found him independent.
- Credit rating
- Moody's, S&P Global Ratings, Fitch Ratings and DBRS Morningstar (as listed in the FY2025 10-K) U.S. Bancorp long-term issuer: A3 (Moody's) / A (S&P) / A+ (Fitch) / AA (low) (DBRS Morningstar) (outlook Not stated in the 10-K), Feb 23, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · Dec 19, 2023
2023 consent orders on prepaid benefit cards
On Dec 19, 2023, U.S. Bank National Association agreed to consent orders with the OCC and the CFPB. The FY2023 10-K says they resolved investigations of how it ran unemployment insurance benefit prepaid debit cards during the pandemic.
regulatory · Feb 9, 2024
2024 SEC settlement on record keeping
On Feb 9, 2024, the SEC announced a settlement with U.S. Bancorp Investments, Inc. over record retention rules for electronic business communications, as the FY2023 10-K states.
other · Feb 23, 2026
Mortgage-backed securities trustee lawsuits
Since 2011, investors have sued U.S. Bank National Association as trustee for mortgage-backed securities trusts. They allege it failed to enforce loan repurchase obligations; the FY2025 10-K says plaintiffs generally seek unspecified damages.
22What the market paid
22What the market paid · price as of Dec 31, 2025
What did the market pay for U.S. Bancorp on Dec 31, 2025?
Price as of Dec 31, 2025 (shown for education; prices change daily).
The FY2025 10-K gives a market value of $53.36 per share at Dec 31, 2025. At that price, the 1,555.4 million shares outstanding were worth about $83.0 billion. P/E (price ÷ yearly diluted earnings per share) was 11.5 on FY2025 EPS of $4.62, and P/B (price ÷ book value per share) was 1.4 on $37.55 (Cityfort calculation from the FY2025 10-K). These are dated facts, not a view on the price.
- Share price
- $53.36
- Market value (market cap)
- $83.0B
- P/E
- 11.5×
- P/B
- 1.4×
More price-based ratios · as of Dec 31, 2025
Each ratio divides a number from the company's filings by the market value or share price on Dec 31, 2025. Prices change daily, so these ratios do too.
Price to sales (P/S)
2.9×
$83.0B market value ÷ $28.7B revenue (four quarters to Dec 31, 2025) = 2.9×
Cityfort calculation from the Dec 31, 2025 closing price and the Q1 FY2025 to Q4 FY2025 10-Qs and 8-Ks. Source: FY2025 Form 10-K, MD&A and financial statements; Form 10-Q for Q1 FY2025; Q1 2025 earnings release and 5 more
How price ratios workDividend yield
3.82%
$2.04 dividends per share (FY2025) ÷ $53.36 share price = 3.82%
Cityfort calculation from the FY2025 10-K and the Dec 31, 2025 closing price. Source: FY2025 Form 10-K, MD&A and financial statements
What dividend yield means
Shares used for the market value: 1,558.2 million ($53.36 × 1,558.2 million shares ≈ $83.0B). Source: Q3 FY2026 Form 10-Q
23How it got here
23How it got here
How did U.S. Bancorp get here?
2022
Business-model change
Bought MUFG Union Bank
On Dec 1, 2022, it bought MUFG Union Bank's core regional banking business from MUFG for $5.5 billion in cash plus shares; year-end loans rose to $388,213 million from $312,028 million.
2023
Milestone
Merger costs
Merger and integration charges were $1,009 million in FY2023, and net income attributable to the company fell to $5,429 million.
2023
Crisis
Consent orders on prepaid cards
On Dec 19, 2023, its bank agreed to OCC and CFPB consent orders over its pandemic-era unemployment benefit prepaid cards.
2024
Milestone
$5.0 billion buyback approved
The board authorized up to $5.0 billion of share repurchases on Sep 12, 2024.
2025
Milestone
New chief executive
Gunjan Kedia became CEO in April 2025, succeeding Andrew Cecere, who became Executive Chairman.
2026
Business-model change
Acquired BTIG
On Jun 1, 2026, it bought Condor Trading LP and its subsidiaries, including the broker-dealer BTIG, LLC.
2026
Milestone
Stablecoin pilot
In Q3 FY2026 it ran a live pilot of its USBDC stablecoin for a cross-border payment between U.S. Bank entities in North America and Europe.
24Sources and changes
Where every number on this page comes from
Sources (23 documents)
- S1FY2025 Form 10-K (business, risk factors, Items 5, 9A, 10-14) · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Feb 23, 2026
- S2FY2025 Form 10-K, MD&A and financial statements · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Feb 23, 2026
- S4FY2024 Form 10-K, MD&A and financial statements · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Feb 21, 2025
- S6FY2023 Form 10-K, MD&A and financial statements · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Feb 20, 2024
- S7Q3 FY2026 Form 10-Q · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Nov 5, 2026
- S8Q2 FY2026 Form 10-Q · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Aug 6, 2026
- S9Q1 FY2026 Form 10-Q · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · May 4, 2026
- S10Q3 FY2025 Form 10-Q · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Nov 5, 2025
- S112026 proxy statement (DEF 14A) · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Mar 10, 2026
- S12Q3 2026 earnings release (8-K Ex. 99.1) · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Oct 15, 2026
- S14Q3 2026 earnings presentation · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Oct 15, 2026
- S15Q2 2026 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Jul 16, 2026
- S18Q1 2026 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Apr 16, 2026
- S20Q4 2025 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Jan 20, 2026
- S22Q3 2025 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Oct 16, 2025
- S23Q2 2025 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Jul 17, 2025
- S24Q1 2025 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Apr 16, 2025
- S25Q4 2024 earnings release · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Jan 16, 2025
- S26Form 10-Q for Q2 FY2025 · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Aug 7, 2025
- S27Form 10-Q for Q1 FY2025 · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · May 6, 2025
- S28Form 10-Q for Q3 FY2024 · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Nov 5, 2024
- S29Form 10-Q for Q2 FY2024 · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · Aug 6, 2024
- S30Form 10-Q for Q1 FY2024 · U.S. Bancorp (SEC EDGAR) · Tier 1: company or exchange filing · May 1, 2024
Changes to this page (v1 · Nov 20, 2026)
- v1 · Nov 20, 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.