Financials · NYSE: WFC
Wells Fargo: how the business works
Wells Fargo, the fourth-largest US bank holding company by assets, takes deposits, makes loans and sells wealth and investment banking services, with revenue of $83.7 billion in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow Wells Fargo
Email me when Wells Fargo's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
Wells Fargo & Company · San Francisco, California
Updated for Q3 FY2026 · checked
- Revenue, FY2025
- $83.7B
- Net income to common stock, FY2025
- $20.3B
- Loans, Sep 30, 2026
- $1,048.1B
- Deposits, Sep 30, 2026
- $1,502.7B
- Employees, Dec 31, 2025
- About 205,000
The short version
Wells Fargo in 5 points
1 · What it sells
Wells Fargo takes deposits, makes consumer and business loans and sells wealth management and investment banking services, with $1,048.1 billion of loans at Sep 30, 2026.
2 · Who pays it
Wells Fargo gives no revenue by customer; by segment, people and small businesses brought in 44% of FY2025 segment revenue, large companies and institutions 23%, wealth clients 19% and commercial clients 14%.
3 · What it keeps from $100
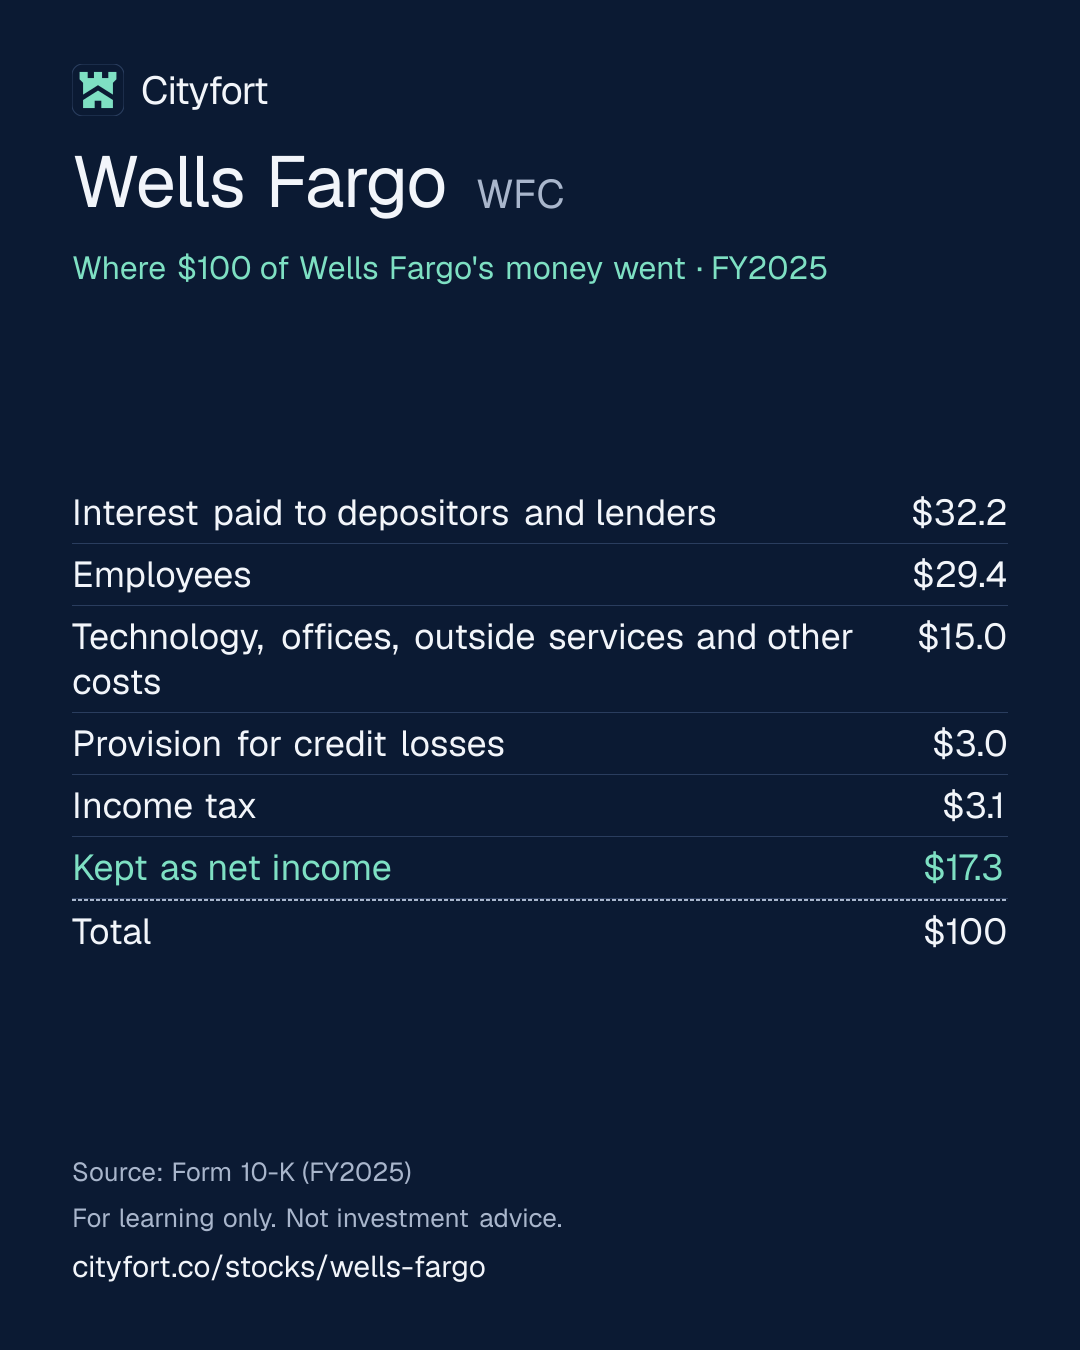
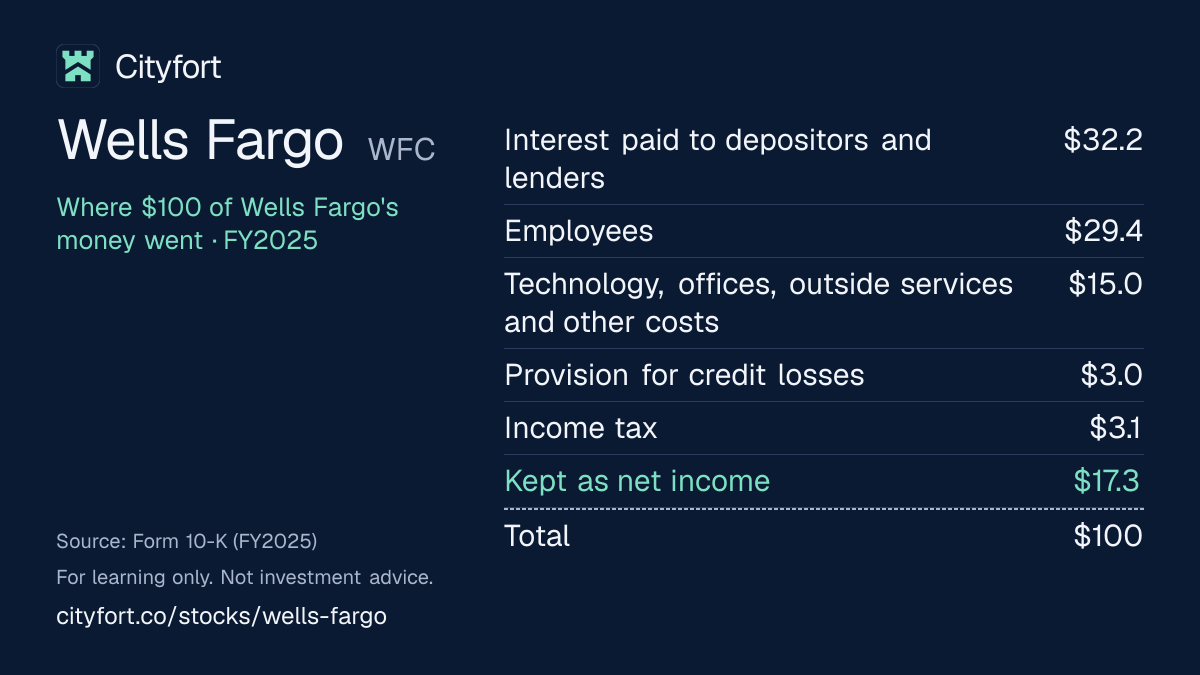
Of every $100 that came in during FY2025, Wells Fargo paid $32.2 in interest to depositors and lenders and $29.4 to employees (including $953 million of severance, of which $612 million in Q4 the company called a notable item, and a special award after the asset cap was removed) and kept $17.3 as net income, with operating profit before credit losses and tax (pre-provision profit) of $28.9 billion.
4 · Where the operating profit comes from
Of FY2025 segment net income, Consumer Banking and Lending earned $7,865 million, Corporate and Investment Banking $7,283 million, Commercial Banking $4,184 million and Wealth and Investment Management $2,119 million.
5 · The one thing to watch
The net interest margin was 2.43% in Q3 FY2026, down from 2.61% in Q3 FY2025, while the company said average loans grew 11% over the same year.
Sources: From Wells Fargo's FY2025 10-K, Q3 FY2026 10-Q, and Oct 13, 2026 earnings release and supplement · checked
See the full receipt and the management scorecard below
Sources (5)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q4 2025 earnings release (Form 8-K Ex. 99.1, filed Jan 14, 2026)
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
01Where $100 of a bank's money goes · FY2025
Where does $100 of Wells Fargo's money go?
Wells Fargo · FY2025
Receipt for every $100
| Interest paid to depositors and lenders | $32.2 |
|---|---|
| Employees | $29.4 |
| Technology, offices, outside services and other costs | $15.0 |
| Provision for credit losses | $3.0 |
| Income tax | $3.1 |
| Kept as net income | $17.3 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Of every $100 that came in (interest earned $87,314 million plus noninterest income $36,215 million = $123,529 million): each line = line ÷ $123,529 million × 100. The $20 million paid to minority owners of subsidiaries rounds to $0.0 and is left out. Net income includes $1,053 million of preferred stock dividends and other. The employee line includes $953 million of severance (of which $612 million of Q4 FY2025 severance, which the company called a notable item in its Q4 2025 earnings release, S9) and a special award to employees after the asset cap was removed (amount not given).
Save this receipt as an image:
1080 × 1350 PNG for Instagram, LinkedIn1200 × 675 PNG for X
Embed this receipt
Paste this code into a blog or website to show the receipt, with a link back to this page:
Each week: one company explained in 5 points, picked by earnings date.
Free, no tips, unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does Wells Fargo do?
Households and companies pay Wells Fargo interest on loans and fees for accounts, cards, advice and deals; most of that money goes on interest to depositors and lenders and on staff, and what's left is profit.
- In FY2025 Wells Fargo earned $47,484 million of net interest income (interest earned minus interest paid) and $36,215 million of noninterest income, mostly fees.
- Interest paid to depositors and lenders took $32.2 of every $100 that came in during FY2025, employees $29.4, and $17.3 was left as net income.
03Who pays it
Who pays Wells Fargo?
People and small businesses
44%
of revenue
Interest on cards and on home, auto and personal loans, plus account and card fees (Consumer Banking and Lending)
Large companies and institutions
23%
of revenue
Interest on corporate and real estate loans, deal fees and trading (Corporate and Investment Banking)
Wealth and brokerage clients
19%
of revenue
Advisory and asset-based fees, commissions and interest (Wealth and Investment Management)
Commercial clients
14%
of revenue
Interest on loans and leases to private, family-owned and public companies, plus treasury management fees (Commercial Banking)
- People and small businesses44%
- Large companies and institutions23%
- Wealth and brokerage clients19%
- Commercial clients14%
How spread out the customers are
Wells Fargo's filings give no revenue by customer, so the split above is by segment: each segment's FY2025 revenue as a share of the four segments' combined $84,900 million, before Corporate and reconciling items (Cityfort calculation from the FY2025 10-K).
04Why it makes money
Why does Wells Fargo make money?
It earns the gap between the interest it charges and the interest it pays, plus fees
Wells Fargo lends out money that mostly comes from depositors. Deposits that pay no interest make that gap wider: $365,368 million of them at the end of FY2025. Fees for advice, cards, deals and trading added $29.3 of every $100 that came in.
Net interest margin (taxable-equivalent)
2.1%2.6%
FY2021 to FY2025
- Take in deposits
- Lend and invest them
- Earn interest and fees
- Pay depositors and staff
- Set money aside for loan losses
- Keep the rest as profit
↺ Step 6 feeds back into step 1.
05Business segments · FY2025
Which businesses make up Wells Fargo?
Consumer Banking and Lending
44%Accounts, cards and home, auto, personal and small business loans. FY2025 net income $7,865 million.
Revenue $37.4B
Corporate and Investment Banking
23%Banking, deal advice, real estate lending and trading for large companies and institutions. FY2025 net income $7,283 million.
Revenue $19.2B
Wealth and Investment Management
19%Investment advice, brokerage, planning and private banking. FY2025 net income $2,119 million.
Revenue $16.3B
Commercial Banking
14%Loans, leases and treasury management for private, family-owned and public companies. FY2025 net income $4,184 million.
Revenue $12.0B
How the mix changed
- Consumer Banking and Lending
- Corporate and Investment Banking
- Wealth and Investment Management
- Commercial Banking
Revenue by segment, FY2024 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has Wells Fargo done?
Net interest income
$47.5BFY2025
Net interest income rose from $35,779 million in FY2021 to $52,375 million in FY2023, then was $47,484 million in FY2025.
* FY2021: allowance release.
US$ · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net income
$20.3BFY2025
Net income applicable to common stock was $20,285 million in FY2025 and $16,863 million in the first nine months of FY2026, up from $15,171 million a year earlier.
* FY2021: allowance release.
US$ · after the provision for credit losses and tax
See the yearly numbers
See the quarterly numbers
Net interest margin
2.64%FY2025
The net interest margin rose from 2.05% in FY2021 to 3.06% in FY2023, was 2.64% in FY2025 and 2.43% in Q3 FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
0.43%FY2025
Net loan charge-offs rose from 0.18% of average loans in FY2021 to 0.52% in FY2024 and were 0.43% in FY2025, when the allowance for loan losses was 1.40% of loans.
* FY2021: allowance release.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the yearly numbers
See the quarterly numbers
See all yearly numbers
† Restated by the company. Diluted EPS on net income applicable to common stock; FY2021 and FY2022 as restated.
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (Fiscal year ends on December 31 (calendar year)).
- All figures are consolidated US GAAP, in US$ million. FY2021 and FY2022 are as restated in the FY2023 annual report for a 2023 change in insurance accounting (ASU 2018-12).
- The FY2021 provision for credit losses is negative: the allowance fell by $5,737 million that year, a release of earlier reserves.
- The net interest margin is on a taxable-equivalent basis, the margin Wells Fargo reports.
- The allowance shown is the allowance for loan losses ($13,797 million at Dec 31, 2025, 1.40% of loans), the ratio in Wells Fargo's quarterly supplement. The annual report's headline ratio adds the allowance for unfunded credit commitments: $14,337 million, or 1.45% of loans.
- Net charge-offs are net loan charge-offs; the ratio is on average loans, as reported (annualized for quarters).
- CET1 is under the standardized approach, which Wells Fargo says is its binding framework; under the advanced approach it was 12.35% at Dec 31, 2025.
- Efficiency ratios are as Wells Fargo reports them, in whole numbers. ROTCE is the company's own (non-GAAP) measure.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100
Sources (6)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
- 2022 Annual Report to Shareholders (Exhibit 13 to the FY2022 Form 10-K)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q3 2025 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 14, 2025)
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
07Who runs it
Who runs Wells Fargo, and did they deliver?
Charles W. (Charlie) Scharf
Chairman, Chief Executive Officer and President · since 2019
CEO and President since October 2019; also Chairman since October 2025.
Michael P. Santomassimo
Chief Financial Officer · since 2020
CFO since October 2020.
Scott E. Powell
Chief Operating Officer · since 2019
COO since December 2019; becomes Chief Risk Officer on Jan 15, 2027.
Derek A. Flowers
Chief Risk Officer · since 2022
Chief Risk Officer since January 2022, as the FY2025 10-K lists.
What they said, and what happened
3 too early to tell
Said on Jan 14, 2026
Management said 2026 net interest income would be "+/- $50" billion.
Too early to tellWhat happened
Net interest income was $36,930 million in the first nine months of FY2026. On Oct 13, 2026 management kept the outlook and said it expects about $13 billion in Q4 FY2026.
Said on Jan 14, 2026
Management said 2026 noninterest expense would be about $55.7 billion.
Too early to tellWhat happened
Noninterest expense was $41,734 million in the first nine months of FY2026; the outlook was unchanged on Oct 13, 2026.
Said on Jan 14, 2026
The CEO said the company set a new medium-term ROTCE target of 17-18%.
Too early to tellWhat happened
ROTCE, the company's own measure, was 16.3% in Q3 FY2026 and 16.2% for the first nine months of FY2026.
Sources (8)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- 8-K Ex. 99.1 (filed Jul 31, 2025): board intends to name CEO Charlie Scharf Chairman
- 8-K Item 5.02 (filed Sep 23, 2026): Scott E. Powell to become Chief Risk Officer from Jan 15, 2027
- 4Q25 Financial Results presentation (Form 8-K Ex. 99.3, filed Jan 14, 2026)
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- 3Q26 Financial Results presentation (Form 8-K Ex. 99.3, filed Oct 13, 2026)
- Q4 2025 earnings release (Form 8-K Ex. 99.1, filed Jan 14, 2026)
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
08What could go wrong
What could go wrong for Wells Fargo?
- Pricing
Paying more for deposits
Interest paid to depositors and lenders rose from $3,915 million in FY2021 to $39,830 million in FY2025. Deposits that pay no interest fell from 35.6% of deposits at the end of FY2021 to 24.3% at Sep 30, 2026 (Cityfort calculation from the FY2022 annual report and the Q3 FY2026 supplement).
Watch Net interest margin each quarter: 2.43% in Q3 FY2026.
- Demand
Loan losses
Net loan charge-offs rose from 0.18% of average loans in FY2021 to 0.52% in FY2024 and were 0.43% in FY2025. Commercial charge-offs rose to 0.18% (annualized) in Q3 FY2026 from 0.10% in Q2, driven by commercial real estate and business loans.
Watch Net charge-off ratio each quarter: 0.38% in Q3 FY2026.
- Regulation
Capital rules and supervision
The CET1 ratio fell from 11.35% at the end of FY2021 to 10.0% at Sep 30, 2026; the regulatory minimum plus buffers was 8.50% at Dec 31, 2025. The FY2025 10-K says complying with the September 2024 OCC formal agreement and other regulatory actions may keep raising costs.
Watch CET1 ratio in each quarterly supplement.
- Legal
Lawsuits and investigations
The Q3 FY2026 10-Q lists class actions and government inquiries, including anti-money laundering and fair-access-to-banking investigations. It puts the high end of reasonably possible losses above accruals at about $1.5 billion.
Watch The legal actions note in each 10-Q.
- Demand
Fee and trading income swings
Noninterest income was $43,387 million in FY2021 and $29,418 million in FY2022. Q2 FY2026 included $847 million of net gains from equity securities, against $4 million in Q3 FY2026.
Watch Noninterest income each quarter: $9,353 million in Q3 FY2026.
- Execution
Cost control
Noninterest expense was $54,842 million in FY2025, an efficiency ratio of 66% of revenue. Employees are the largest cost at $36,281 million; headcount fell to 194,369 at Sep 30, 2026.
Watch Efficiency ratio each quarter: 63% in Q3 FY2026.
Sources (6)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
- 2022 Annual Report to Shareholders (Exhibit 13 to the FY2022 Form 10-K)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
09Both sides
What do supporters and critics point to?
What supporters point to
- Net income applicable to common stock rose from $12,562 million in FY2022 to $20,285 million in FY2025.
- Loans grew from $912,745 million at the end of FY2024 to $1,048,113 million at Sep 30, 2026, after the asset cap was removed on Jun 3, 2025.
- ROTCE, the company's own measure, was 16.3% in Q3 FY2026, up from 15.2% a year earlier.
- Average diluted shares fell from 4,096.2 million in FY2021 to 3,242.3 million in FY2025; the company repurchased $18 billion of stock in 2025.
- S&P raised the parent company's long-term rating to A- from BBB+ on Sep 29, 2026.
What critics point to
- Interest paid to depositors and lenders rose from $3,915 million in FY2021 to $39,830 million in FY2025.
- The net interest margin fell from 2.61% in Q3 FY2025 to 2.43% in Q3 FY2026.
- The CET1 ratio fell from 11.35% at the end of FY2021 to 10.0% at Sep 30, 2026.
- Net loan charge-offs were 0.43% of average loans in FY2025, up from 0.18% in FY2021.
- The Q3 FY2026 10-Q puts the high end of reasonably possible legal losses above accruals at about $1.5 billion.
10What to watch next
What should you watch next at Wells Fargo?
Next event
Q4 FY2026 results
Date not announced yet.
Net interest margin
It was 2.43% in Q3 FY2026, down from 2.61% a year earlier. On Oct 13, 2026 management said it expects Q4 FY2026 net interest income of about $13 billion.
Loan losses
Net loan charge-offs were 0.38% of average loans in Q3 FY2026; commercial charge-offs rose to 0.18% from 0.10% in Q2.
Chief Risk Officer change
Scott E. Powell moves from Chief Operating Officer to Chief Risk Officer on Jan 15, 2027.
11Key dates
What are the key dates for Wells Fargo?
| Event | Date | Source |
|---|---|---|
| Scott E. Powell becomes Chief Risk Officer (officer change, 8-K)He stops serving as Chief Operating Officer on that date. | 8-K Item 5.02 (filed Sep 23, 2026): Scott E. Powell to become Chief Risk Officer from Jan 15, 2027 |
Learn: What is an 8-K? A company's news report, with a real Adobe filing
12Key facts
Key facts about Wells Fargo
- What does Wells Fargo do?
- Wells Fargo & Company is a US bank holding company that takes deposits, makes consumer and business loans, and sells wealth management, brokerage and investment banking services; it had $1,048.1 billion of loans and $1,502.7 billion of deposits at Sep 30, 2026.
- How does Wells Fargo make money?
- Wells Fargo earned $47,484 million of net interest income (interest on loans and securities minus interest paid to depositors and lenders) and $36,215 million of noninterest income such as advisory, card and banking fees in FY2025, for total revenue of $83,699 million.
- Is Wells Fargo profitable?
- Yes. Wells Fargo's net income applicable to common stock was $20,285 million in FY2025, up from $18,606 million in FY2024, and $16,863 million in the first nine months of FY2026; diluted EPS was $6.26 in FY2025.
- What is Wells Fargo's revenue by segment?
- In FY2025 Wells Fargo's Consumer Banking and Lending segment brought in $37,362 million of revenue, Corporate and Investment Banking $19,232 million, Wealth and Investment Management $16,328 million and Commercial Banking $11,978 million.
- How many branches and digital customers does Wells Fargo have?
- Wells Fargo had 4,068 retail bank branches, 38.2 million digital active customers and 34.0 million mobile active customers at Sep 30, 2026.
- How much does Wells Fargo lose on bad loans?
- Wells Fargo's net loan charge-offs were $3,994 million in FY2025, or 0.43% of average loans, and it recorded a provision for credit losses of $3,658 million; net loan charge-offs were 0.38% of average loans (annualized) in Q3 FY2026.
- What is Wells Fargo's CET1 capital ratio?
- Wells Fargo's CET1 capital ratio under the standardized approach was 10.61% at Dec 31, 2025, against a regulatory minimum plus buffers of 8.50%, and 10.0% at Sep 30, 2026.
- Who owns Wells Fargo?
- Wells Fargo has one class of common stock with one vote per share; directors and executive officers owned about 0.13% as of Feb 9, 2026, and Vanguard Capital Management reported owning 7.5% at Mar 31, 2026.
- Does Wells Fargo pay a dividend?
- Wells Fargo declared dividends of $1.70 per common share in FY2025, up from $1.50 in FY2024, and repurchased $18 billion of its stock in 2025; the Q3 FY2026 dividend was $0.50 a share.
Sources (7)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
- 2026 proxy statement (DEF 14A, filed Mar 18, 2026)
- Schedule 13G by Vanguard Capital Management on Wells Fargo & Co (event date Mar 31, 2026)
- Q4 2025 earnings release (Form 8-K Ex. 99.1, filed Jan 14, 2026)
Terms on this page
- Allowance for credit losses
- CET1 ratio
- Earnings per share (EPS)
- Efficiency ratio
- Market cap
- Net charge-offs
- Net interest income and margin
- P/E ratio
- Stock buyback
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
13What it sells
13What it sells
What does Wells Fargo sell?
Accounts and consumer loans
Checking and savings accounts, debit and credit cards, and home, auto, personal and small business loans.
Wealth management and brokerage
Investment advice, brokerage, financial planning, private banking and trust services, paid mostly by fees.
Commercial banking
Loans, leases and treasury management (handling payments and cash) for private, family-owned and public companies.
Corporate and investment banking
Corporate banking, deal advice, raising money in stock and bond markets, commercial real estate lending, and trading for large companies and institutions.
Think of it like this
Like a shop that buys money from savers and rents it to borrowers at a higher price, with a fee counter on the side.
What it does
- Does: Takes deposits from people and businesses
- Does: Makes home, auto, card, personal and business loans
- Does: Gives investment advice and runs a brokerage
- Does: Arranges deals and trades for large companies
What it does not do
- Does not: Serve customers mainly outside the US: it operates primarily in the US
- Does not: Own the Visa or Mastercard networks: it issues cards that run on them
- Does not: Run its rail car leasing business any more: it sold it in Q1 FY2026
14How the money flows
14How the money flows · FY2025
How does money flow through Wells Fargo?
Money in
- Interest earned on loans and securities$87.3B
- Fees and other noninterest income$36.2B
The company
Wells Fargo
$123.5B came in
Money out
- Interest paid to depositors and lenders$39.8B
- Employees$36.3B
- Technology, offices, outside services and other costs$18.6B
- Provision for credit losses$3.7B
- Income tax$3.8B
- Owners of minority stakes in subsidiaries$20M
- Wells Fargo net income (of which $1,053 million went to preferred stockholders)$21.3B
- Savers and companies deposit money; Wells Fargo also borrows in bond markets.
- It lends and invests that money and earned $87,314 million of interest in FY2025.
- Fees for advice, cards, deals and trading brought in another $36,215 million.
- It paid $39,830 million of interest, $36,281 million to employees and $18,561 million of other running costs, and set aside $3,658 million for loan losses.
- After $3,841 million of tax, $21,338 million was left as net income.
15What it needs to run
15What it needs to run
What does Wells Fargo need to run?
Deposits
Its main source of money to lend: $1,426,207 million at the end of FY2025, of which $365,368 million paid no interest.
Capital
Regulators require a cushion of shareholders' money. Its CET1 ratio was 10.61% at Dec 31, 2025, against a minimum plus buffers of 8.50%.
People
About 205,000 active employees at Dec 31, 2025, about 76% of them in the US; 194,369 at Sep 30, 2026.
Branches and apps
4,090 retail bank branches and 37.2 million digital active customers at Dec 31, 2025.
16Where growth could come from
16Where growth could come from
Where could Wells Fargo's growth come from?
Management said in its 3Q26 results presentation (Oct 13, 2026) that it expects 2026 net interest income of "+/- $50 billion", unchanged from prior guidance, Q4 FY2026 net interest income of about $13 billion, and 2026 noninterest expense of about $55.7 billion.
Loan growth after the asset cap
Working$912.7B → $1,048.1B loans
The Federal Reserve removed the asset cap on Jun 3, 2025. Loans rose from $912,745 million at the end of FY2024 to $1,048,113 million at Sep 30, 2026, and the company said average loans grew 11% from a year earlier in Q3 FY2026.
Status: Working, on track against what the company said.
Wealth and Investment Management
Working+12% revenue in Q3 FY2026
Segment revenue rose from $15,436 million in FY2024 to $16,328 million in FY2025; the company said it grew 12% from a year earlier in Q3 FY2026.
Status: Working, on track against what the company said.
Corporate and Investment Banking
Mixed+3% revenue in Q3 FY2026
Segment revenue was $19,344 million in FY2024 and $19,232 million in FY2025; the company said it rose 3% from a year earlier in Q3 FY2026, with M&A revenue up 30%.
Status: Mixed, partly on track.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (5)
- 3Q26 Financial Results presentation (Form 8-K Ex. 99.3, filed Oct 13, 2026)
- 8-K Ex. 99.1 (filed Jun 3, 2025): Federal Reserve removed the asset growth limit of the 2018 consent order
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
17The company's own measures (non-GAAP)
17The company's own measures · FY2025 and Q3 FY2026
What do Wells Fargo's own measures show?
Official (GAAP): Return on average common equity (ROE), FY2025
12.4%
Company's own measure: Return on average tangible common equity (ROTCE), FY2025
14.6%
Tangible common equity is total equity less preferred equity, noncontrolling interests, goodwill and certain intangible assets (other than mortgage servicing rights), net of related deferred taxes, as Wells Fargo defines it.
Official (GAAP): ROE, Q3 FY2026 (annualized)
13.8%
Company's own measure: ROTCE, Q3 FY2026 (annualized)
16.3%
The same definition. Wells Fargo put ROTCE at 16.2% for the first nine months of FY2026.
Official (GAAP): Book value per common share, Sep 30, 2026
$52.91
Company's own measure: Tangible book value per common share, Sep 30, 2026
$44.46
Tangible common equity divided by common shares outstanding.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
18Financial strength: capital, loan losses, deposits
18Financial strength · FY2025
How strong is Wells Fargo's balance sheet?
- Loans made$986.2B
- Deposits taken$1.43T
- of which pay no interest$365.4B
Loans were 69.1% of deposits at the end of FY2025 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 25.6% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 10.61%
- common equity capital as a share of risk-weighted assets (standardized approach); regulators set a minimum
- Allowance for credit losses
- $13.8B
- money set aside for expected loan losses: 1.4% of loans
- Net charge-offs
- $4.0B
- loans written off, minus recoveries: 0.43% of average loans
- Efficiency ratio
- 66.0%
- $ of noninterest expense per $100 of revenue (net interest income + noninterest income)
- Return on assets
- 1.07%
- net income as % of average total assets
- Return on equity
- 12.4%
- net income as % of average common equity
- Return on tangible common equity
- 14.6%
- the company's own measure (non-GAAP): equity without goodwill and other intangibles
Figures at the end of FY2025, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
19Who owns it
19Who owns it · ownership as of Feb 9, 2026
Who owns Wells Fargo?
- Officers and directors (as a group), shares
- 0.1%
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Insider trades · Form 4 data as of Nov 6, 2026
What did Wells Fargo's insiders report trading?
Wells Fargo's insiders made 92 Form 4A filing an insider must make within two business days of buying or selling the company's shares. Learn more filings in the 12 months to Nov 6, 2026.
They reported no purchases and 3 sales (115,000 shares) in the open market or privately (codes P and S).
None of the sales were on forms with the Rule 10b5-1 plan box checked.
The same filings report 151 other share transactions (F: 70, M: 70, G: 10, J: 1).
They also report 120 transactions in options, stock units or other derivatives.
Insiders are a company's officers, directors and owners of more than 10% of a class of its shares. Most changes in their holdings must be reported to the SEC on a Form 4 within two business days. Source: SEC Form 4 filings on EDGAR.
- P
- a purchase in the open market or privately
- S
- a sale in the open market or privately
- F
- shares withheld or handed over to pay an exercise price or tax when an award is received, exercised or vests
- M
- exercise or conversion of an option or other derivative, exempt under Rule 16b-3
- G
- a bona fide gift
- J
- another acquisition or disposition, described in a footnote
Code meanings: General Instruction 8 of Form 4 (SEC).
The latest 25 of 154 transactions
Shares: A = acquired, D = disposed of. A price the filing gives only in a footnote shows as “See filing”. The 10b5-1 box is checked when at least one trade on the form was made under a Rule 10b5-1 plan. A Form 4/A replaces the form it amends. See all of Wells Fargo's Form 4 filings on EDGAR.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes · Rule 10b5-1 trading plans: how insiders pre-schedule their trades
Sources (5)
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
- 2026 proxy statement (DEF 14A, filed Mar 18, 2026)
- Schedule 13G by Vanguard Capital Management on Wells Fargo & Co (event date Mar 31, 2026)
- Schedule 13G/A by The Vanguard Group on Wells Fargo & Co (event date Mar 13, 2026: 0 shares)
- Schedule 13G/A by FMR LLC on Wells Fargo & Company (event date Sep 30, 2026: 4.7%)
20What it does with profit
20What it does with profit
What does Wells Fargo do with its profit?
Dividend per share
$1.70FY2025
Dividend paid for each share, by financial year.
$ per share
See the numbers
Buyback · Dec 31, 2025
Repurchased $18 billion of common stock in 2025, part of the $23 billion the company said it returned to shareholders that year.
$18.0B
Buyback · Sep 30, 2026
Repurchased 28.6 million shares in Q3 FY2026.
$2.5B
Sources (4)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q4 2025 earnings release (Form 8-K Ex. 99.1, filed Jan 14, 2026)
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
21Governance signals
21Governance signals
What do Wells Fargo's governance filings show?
- Auditor
- KPMG LLP, since 1931
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy says some directors, executive officers and the 5% holders BlackRock, FMR and Vanguard had loans and other banking services from Wells Fargo in 2025 in the ordinary course of business, on substantially the same terms as for unrelated customers.
- Credit rating
- Moody's, S&P Global Ratings and Fitch (as stated in the Q3 FY2026 10-Q) Parent long-term: A1 (Moody's), A- (S&P, raised from BBB+ on Sep 29, 2026), A+ (Fitch). Wells Fargo Bank, N.A.: Aa2 / A+ / AA- (Stable (all three agencies)), Sep 30, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · Jun 3, 2025
2018 Federal Reserve consent order and asset cap
A February 2018 Federal Reserve consent order limited growth in Wells Fargo's total assets. The Federal Reserve removed that limit on Jun 3, 2025. The FY2025 10-K (filed Feb 24, 2026) still named the 2018 order among the company's regulatory actions. The 2026 proxy statementThe yearly filing about shareholder votes, the board and executive pay. Learn more (filed Mar 18, 2026) says all outstanding consent orders have been terminated: 14 since 2019, eight of them in 2025 and early 2026.
regulatory · Sep 12, 2024
Anti-money laundering formal agreement
On Sep 12, 2024, Wells Fargo Bank, N.A. entered a formal agreement with the OCC on its anti-money laundering and sanctions risk management. The Q3 FY2026 10-Q says government authorities are conducting inquiries into these programs.
other · Sep 30, 2026
Pending lawsuits
The Q3 FY2026 10-Q lists suits alleging a breach of duties over cash sweep rates, alleged mortgage discrimination and alleged interchange collusion, and a March 2025 trust verdict that Wells Fargo has appealed. It puts the high end of reasonably possible losses above accruals at about $1.5 billion.
other · Jan 13, 2026
Derivative suit settlement
On Jan 13, 2026 a federal court in Northern California gave preliminary approval to a proposed settlement of shareholder derivative suits over home mortgage lending and diversity hiring practices. The settlement notice filed with the 8-K says Wells Fargo shall fund $100 million in mortgage assistance for low- and moderate-income borrowers, and that the court set a hearing on final approval for May 5, 2026.
other · Jul 31, 2025
CEO is also Chairman
Charlie Scharf became Chairman in October 2025, with a Lead Independent Director. In July 2025 the board gave him a one-time grant of $30 million in restricted share rights and 1,046,000 stock options.
Sources (7)
- 2026 proxy statement (DEF 14A, filed Mar 18, 2026)
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
- 8-K Ex. 99.1 (filed Jun 3, 2025): Federal Reserve removed the asset growth limit of the 2018 consent order
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- 8-K Item 8.01 and Ex. 99.1 (filed Jan 22, 2026): notice of pendency and proposed settlement of shareholder derivative action
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- 8-K Ex. 99.1 (filed Jul 31, 2025): board intends to name CEO Charlie Scharf Chairman
22What the market paid
22What the market paid · price as of Nov 5, 2026
What did the market pay for Wells Fargo on Nov 5, 2026?
Price as of Nov 5, 2026 (shown for education; prices change daily).
Price as of Nov 5, 2026: Wells Fargo closed at $84.80, from Nasdaq's historical price table for WFC; the shares are listed on the NYSE. Market value of about $254.6 billion (Cityfort calculation from the Nov 5, 2026 closing price and the Q3 FY2026 10-Q) = $84.80 × 3,001,850,317 shares outstanding on Oct 19, 2026. P/E is the price ÷ earnings per share: 13.5 on FY2025 diluted EPS of $6.26. P/B is the price ÷ book value per share: 1.60 on $52.91 at Sep 30, 2026.
- Share price
- $84.80
- Market value (market cap)
- $254.6B
- P/E
- 13.5×
- P/B
- 1.6×
More price-based ratios · as of Nov 5, 2026
Each ratio divides a number from the company's filings by the market value or share price on Nov 5, 2026. Prices change daily, so these ratios do too.
Price to sales (P/S)
2.9×
$254.6B market value ÷ $87.2B revenue (four quarters to Sep 30, 2026) = 2.9×
Cityfort calculation from the Nov 5, 2026 closing price and the Q4 FY2025 to Q3 FY2026 10-Qs and earnings releases. Source: WFC historical daily prices, Nasdaq's table for an NYSE-listed share (close of Nov 5, 2026: $84.80); Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026); 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements and 1 more
How price ratios workDividend yield
2.00%
$1.70 dividends per share (FY2025) ÷ $84.80 share price = 2.00%
Cityfort calculation from the FY2025 10-K and the Nov 5, 2026 closing price. Source: WFC historical daily prices, Nasdaq's table for an NYSE-listed share (close of Nov 5, 2026: $84.80); Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026); 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements and 1 more
What dividend yield means
Shares used for the market value: 3,001.85 million ($84.80 × 3,001.85 million shares ≈ $254.6B). Source: Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026); 2026 proxy statement (DEF 14A, filed Mar 18, 2026)
Source: WFC historical daily prices, Nasdaq's table for an NYSE-listed share (close of Nov 5, 2026: $84.80); Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026); 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements and 1 more
Sources (5)
- WFC historical daily prices, Nasdaq's table for an NYSE-listed share (close of Nov 5, 2026: $84.80)
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- 2026 proxy statement (DEF 14A, filed Mar 18, 2026)
23How it got here
23How it got here
How did Wells Fargo get here?
2000
Milestone
Financial holding company
Became a financial holding company on Mar 13, 2000, which lets it own securities and insurance businesses alongside its banks.
2018
Crisis
Federal Reserve consent order
A February 2018 consent order capped growth in total assets until board governance, compliance and operational risk were improved.
2019
Milestone
New CEO
Charlie Scharf became Chief Executive Officer and President in October 2019.
2024
Crisis
OCC formal agreement
On Sep 12, 2024 the main bank entered a formal agreement with the OCC on anti-money laundering and sanctions risk management.
2025
Business-model change
Asset cap removed
On Jun 3, 2025 the Federal Reserve removed the limit on total asset growth. Loans grew from $912,745 million at the end of FY2024 to $1,048,113 million at Sep 30, 2026.
2025
Milestone
CEO becomes Chairman
Charlie Scharf added the Chairman role in October 2025, as the board had said on Jul 31, 2025.
2026
Milestone
Rail car leasing sold
Sold its rail car leasing business in Q1 FY2026, which lowered lease income.
2026
Milestone
S&P rating raised
On Sep 29, 2026 S&P raised the parent company's long-term rating to A- from BBB+, with a stable outlook.
Sources (7)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- 8-K Ex. 99.1 (filed Jun 3, 2025): Federal Reserve removed the asset growth limit of the 2018 consent order
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements
- Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026)
- Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026)
- 8-K Ex. 99.1 (filed Jul 31, 2025): board intends to name CEO Charlie Scharf Chairman
- Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026)
24Sources and changes
Where every number on this page comes from
Sources (20 documents)
- S1Form 10-K, fiscal year 2025 (ended Dec 31, 2025) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Feb 24, 2026
- S22025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K): Financial Review, risk factors, financial statements · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Feb 24, 2026
- S32023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Feb 20, 2024
- S42022 Annual Report to Shareholders (Exhibit 13 to the FY2022 Form 10-K) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Feb 21, 2023
- S5Form 10-Q, quarter ended Sep 30, 2026 (Q3 FY2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Oct 28, 2026
- S6Q3 2026 earnings release (Form 8-K Ex. 99.1, filed Oct 13, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Oct 13, 2026
- S7Q3 2026 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 13, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Oct 13, 2026
- S8Q3 2025 Quarterly Financial Supplement (Form 8-K Ex. 99.2, filed Oct 14, 2025) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Oct 14, 2025
- S9Q4 2025 earnings release (Form 8-K Ex. 99.1, filed Jan 14, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Jan 14, 2026
- S104Q25 Financial Results presentation (Form 8-K Ex. 99.3, filed Jan 14, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Jan 14, 2026
- S113Q26 Financial Results presentation (Form 8-K Ex. 99.3, filed Oct 13, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Oct 13, 2026
- S122026 proxy statement (DEF 14A, filed Mar 18, 2026) · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Mar 18, 2026
- S13Schedule 13G by Vanguard Capital Management on Wells Fargo & Co (event date Mar 31, 2026) · Vanguard Capital Management (SEC EDGAR) · Tier 1: company or exchange filing · Apr 30, 2026
- S14Schedule 13G/A by The Vanguard Group on Wells Fargo & Co (event date Mar 13, 2026: 0 shares) · The Vanguard Group (SEC EDGAR) · Tier 1: company or exchange filing · Mar 27, 2026
- S15Schedule 13G/A by FMR LLC on Wells Fargo & Company (event date Sep 30, 2026: 4.7%) · FMR LLC (SEC EDGAR) · Tier 1: company or exchange filing · Nov 5, 2026
- S168-K Ex. 99.1 (filed Jun 3, 2025): Federal Reserve removed the asset growth limit of the 2018 consent order · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Jun 3, 2025
- S178-K Ex. 99.1 (filed Jul 31, 2025): board intends to name CEO Charlie Scharf Chairman · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Jul 31, 2025
- S188-K Item 5.02 (filed Sep 23, 2026): Scott E. Powell to become Chief Risk Officer from Jan 15, 2027 · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Sep 23, 2026
- S198-K Item 8.01 and Ex. 99.1 (filed Jan 22, 2026): notice of pendency and proposed settlement of shareholder derivative action · Wells Fargo & Company (SEC EDGAR) · Tier 1: company or exchange filing · Jan 22, 2026
- S20WFC historical daily prices, Nasdaq's table for an NYSE-listed share (close of Nov 5, 2026: $84.80) · Nasdaq, Inc. · Tier 1: company or exchange filing · Nov 5, 2026
Changes to this page (v1 · Nov 6, 2026)
- v1 · Nov 6, 2026First version, through Q3 FY2026 (quarter ended Sep 30, 2026). (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.