Financials · NYSE: TFC
Truist: how the business works
Truist takes deposits and lends to people and companies through 1,927 branches, with revenue of $20.3 billion in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow Truist
Email me when Truist's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
Truist Financial Corporation · Charlotte, North Carolina · Founded 1872
Updated for Q3 FY2026 · checked
- Revenue, FY2025
- $20.3B
- Net income to common shareholders, FY2025
- $5.0B
- Deposits, Dec 31, 2025
- $400.4B
- Branches, Dec 31, 2025
- 1,927
- Employees, Dec 31, 2025
- 38,711
The short version
Truist in 5 points
1 · What it sells
Truist takes deposits and lends to people, small businesses and companies through 1,927 branches, and sells wealth, card, payment and investment banking services, with revenue of $20.3 billion in FY2025.
2 · Who pays it
Of the two segments' combined FY2025 revenue, consumer and small business clients brought in 51.9% and commercial, corporate and wealth clients 48.1% (Cityfort calculation from the FY2025 10-K).
3 · What it keeps from $100
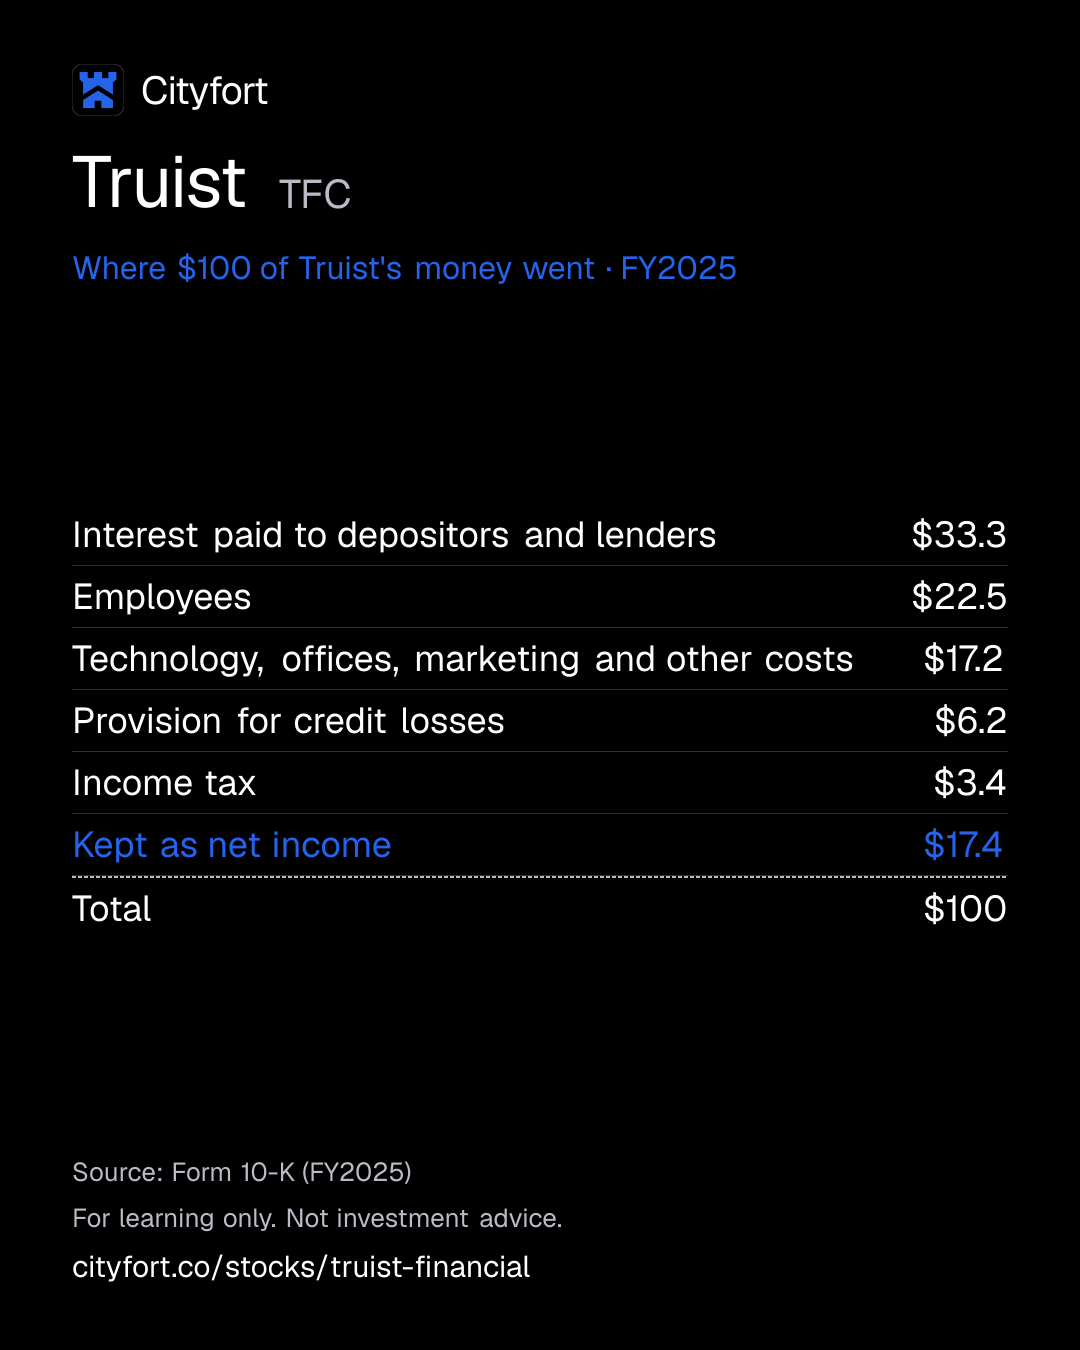
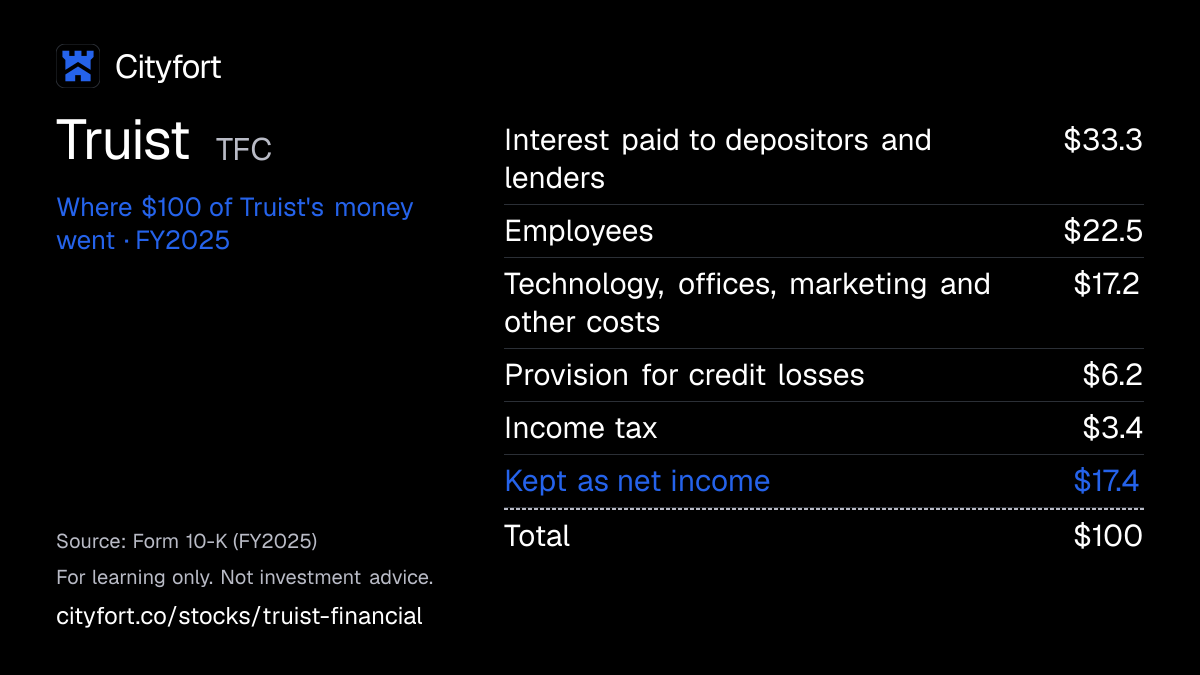
Of every $100 that came in during FY2025, Truist paid $33.3 in interest to depositors and lenders and $22.5 to employees, and kept $17.4 as net income, all from continuing operations; its operating profit before income tax was $6,349 million.
4 · Where the operating profit comes from
Of FY2025 segment net income, Wholesale Banking earned $4,102 million and Consumer and Small Business Banking $2,529 million.
5 · The one thing to watch
Truist's net interest margin rose from 2.86% in FY2021 to 3.03% in FY2025, while its deposits that pay no interest fell from $145.9 billion to $105.1 billion.
Sources: From Truist's FY2021 and FY2025 10-Ks · checked
01Where $100 of a bank's money goes · FY2025
Where does $100 of Truist's money go?
Truist · FY2025
Receipt for every $100
| Interest paid to depositors and lenders | $33.3 |
|---|---|
| Employees | $22.5 |
| Technology, offices, marketing and other costs | $17.2 |
| Provision for credit losses | $6.2 |
| Income tax | $3.4 |
| Kept as net income | $17.4 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Of every $100 that came in (interest income of $24,542 million plus noninterest income of $5,896 million = $30,438 million): each line = line ÷ $30,438 million × 100. Net income includes $333 million of preferred dividends and other items that go to preferred shareholders.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report earnings, explained in 5 points.
No tips. Unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does Truist do?
Borrowers pay Truist interest and clients pay it fees; most of that goes on interest to depositors and on staff, and what is left is profit.
- In FY2025, $24.5 billion of interest and $5.9 billion of fees and other income came in.
- Of every $100 that came in, $33.3 went on interest paid, $22.5 on employees, and $17.4 was kept as net income.
03Who pays it
Who pays Truist?
Truist does not disclose how much each type of customer pays.
Borrowers and bond issuers
Companies and households pay interest on loans, and Truist also earns interest on the securities it holds. Total interest income was $24,542 million in FY2025.
Wealth management clients
Pay for advice, trust and asset management: $1,431 million in FY2025.
Card users and businesses using payment services
Card and treasury management fees were $1,360 million in FY2025.
Companies raising money or trading
Investment banking and trading income was $1,136 million in FY2025.
Account holders and mortgage borrowers
Other deposit revenue was $471 million, mortgage banking income $452 million and lending related fees $395 million in FY2025.
How spread out the customers are
Truist's filings do not give revenue by customer. Its loans at Dec 31, 2025 were spread over eight loan types, from commercial and industrial loans ($167.8 billion) to credit cards ($4.9 billion).
04How it makes money
How does Truist make money?
Truist earns the gap between what borrowers pay and what it pays for deposits, plus fees.
Net interest income, the interest earned minus the interest paid, was $14.4 billion of Truist's $20.3 billion revenue in FY2025. The net interest margin measures that gap against earning assets: 3.03% in FY2025, up from 2.86% in FY2021. Staff, technology and loan losses are paid from what comes in.
Net interest margin (taxable-equivalent)
2.9%3.0%
FY2021 to FY2025
- Customers deposit money at Truist Bank
- Truist lends it to companies and households and buys bonds
- Borrowers pay interest; depositors are paid a lower rate
- Fees from wealth, cards, payments and deals add income
- Staff, technology and loan losses are paid
- What remains is profit, partly paid out as dividends and buybacks
↺ Step 6 feeds back into step 1.
05Business segments · FY2025
Which businesses make up Truist?
Consumer and Small Business Banking
51.9%Accounts, loans and cards for retail, premier and small business clients; FY2025 net income $2,529 million. Revenue here is segment net interest income plus noninterest income, and shares are of the two segments' combined $22,481 million (Cityfort calculation from the FY2025 10-K). Other, Treasury and Corporate subtracts $2,162 million to reach total revenue of $20,319 million.
Revenue $11.7B ($11,657M)
Wholesale Banking
48.1%Loans, payments, investment banking and wealth services for commercial, corporate, institutional and wealth clients; FY2025 net income $4,102 million.
Revenue $10.8B ($10,824M)
How the mix changed
- Consumer and Small Business Banking
- Wholesale Banking
Revenue by segment, FY2023 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has Truist done?
Net interest income
$14.4BFY2025
Net interest income was $14.4 billion in FY2025, against $14.1 billion in FY2024 and $13.0 billion in FY2021.
* FY2021: As first reported, insurance included; FY2022: As first reported, insurance included; FY2023: $6.1B goodwill impairment; FY2024: $6.7B securities loss; insurance sale.
US$ · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net income
$5.0BFY2025
Q3 FY2026 net income to common shareholders of $684 million included a $1,447 million pre-tax loss on securities sold, against $1,519 million in Q2 FY2026.
* FY2021: As first reported, insurance included; FY2022: As first reported, insurance included; FY2023: $6.1B goodwill impairment; FY2024: $6.7B securities loss; insurance sale.
US$ · after the provision for credit losses and tax
See the yearly numbers
See the quarterly numbers
Net interest margin
3.03%FY2025
The taxable-equivalent net interest margin was 3.03% in both FY2024 and FY2025, and 3.00% in Q3 FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
0.54%FY2025
Net charge-offs were 0.54% of average loans in FY2025; the allowance for loan and lease losses was 1.53% of loans at Dec 31, 2025 and 1.25% at Sep 30, 2026.
* FY2021: As first reported, insurance included; FY2022: As first reported, insurance included; FY2023: $6.1B goodwill impairment; FY2024: $6.7B securities loss; insurance sale.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the yearly numbers
See the quarterly numbers
See all yearly numbers
† Restated by the company.
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (December 31).
- FY2023 to FY2025 are as reported in the FY2025 10-K, with Truist Insurance Holdings (sold May 6, 2024) shown as discontinued operations; FY2021 and FY2022 are as first reported, with insurance income and costs included.
- Net interest margin is on a taxable-equivalent basis, as Truist reports it. Return on average assets for FY2025 was not found in the FY2025 10-K collected for this page.
- Q4 FY2024 revenue ($5,060 million), net interest income ($3,590 million) and net income to common shareholders ($1,220 million) are the Q4 FY2024 and Q4 FY2025 earnings releases' figures, which are stated only in billions to two decimals; the other Q4 FY2024 figures are exact.
- Q3 FY2026 includes the Regional Acceptance auto loan sale ($581 million reserve release, $251 million of net charge-offs on the transfer) and the $1,447 million securities loss.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100
Sources (16)
- Truist Financial Corporation FY2021 Form 10-K
- Truist Financial Corporation FY2023 Form 10-K
- Truist Financial Corporation FY2022 Form 10-K
- Truist Financial Corporation FY2024 Form 10-K
- Truist Financial Corporation FY2025 Form 10-K
- Truist Financial Corporation Q4 2024 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q4 2025 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q1 2025 Form 10-Q
- Truist Financial Corporation Q1 2025 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q2 2026 quarterly performance summary (8-K Ex. 99.2)
- Truist Financial Corporation Q2 2025 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q3 2026 quarterly performance summary (8-K Ex. 99.2)
- Truist Financial Corporation Q3 2025 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q1 2026 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q2 2026 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q3 2026 earnings release (8-K Ex. 99.1)
07Who runs it
Who runs Truist, and did they deliver?
Michael P. Lyons
President and Chief Executive Officer · since 2026
Became CEO of Truist Financial and Truist Bank on Aug 31, 2026, per the Q3 FY2026 10-Q.
William H. Rogers Jr.
Executive Chair · since 2026
CEO from September 2021 and Chairman from March 2022. Under the succession plan announced Jun 15, 2026, he was to retire as CEO and serve as Executive Chair through the 2027 annual meeting.
Michael B. Maguire
Chief Financial Officer · since 2022
Senior Executive Vice President and CFO since September 2022.
Brad Bender
Chief Risk Officer · since 2024
In the role since November 2024.
Scott A. Stengel
Chief Legal Officer · since 2023
General Counsel at Ally Financial from May 2016 to December 2023.
Kristin Lesher
Chief Wholesale Banking Officer · since 2024
Joined from Wells Fargo; in the role since February 2024.
Dont L. Wilson
Chief Consumer and Small Business Banking Officer · since 2023
In the role since November 2023.
Thomas E. Skains
Lead Independent Director · since 2022
Retired chairman, president and CEO of Piedmont Natural Gas; re-elected lead director in February 2026.
What they said, and what happened
3 too early to tell
Said on Jul 17, 2026
Management's Q2 FY2026 earnings presentation projected about $5 billion of share repurchases in 2026.
Too early to tellWhat happened
Truist repurchased $1.1 billion in Q1, $1.2 billion in Q2 and $1.2 billion in Q3 FY2026; the Oct 16, 2026 presentation projected about $1 billion more in Q4 2026.
Said on Jul 17, 2026
The forward-looking statements in management's Q2 FY2026 presentation name achieving a 15% ROTCE, a non-GAAPThe company's own "adjusted" numbers, not the official (GAAP) ones. Always read them next to the official figure. Learn more return measure, in 2027.
Too early to tellWhat happened
ROTCE was 13.8% in Q1, 15.4% in Q2 and 7.2% in Q3 FY2026 (14.6% on the company's adjusted basis); the Oct 16, 2026 presentation said Truist was "on track to achieve ROTCE targets".
Said on Jul 17, 2026
Management's Q2 FY2026 presentation projected a FY2026 net charge-off ratio of about 0.55%.
Too early to tellWhat happened
The quarterly ratio was 0.61% in Q1, 0.50% in Q2 and 0.77% in Q3 FY2026; the company states 0.38% for Q3 excluding the Regional Acceptance sale.
Sources (9)
- Truist Financial Corporation Q3 2026 Form 10-Q
- Truist Financial Corporation FY2025 Form 10-K
- Truist Financial Corporation Q2 2026 Form 10-Q
- Truist Financial Corporation 2026 proxy statement (DEF 14A)
- Truist Financial Corporation Q2 2026 earnings presentation (8-K Ex. 99.3)
- Truist Financial Corporation Q1 2026 Form 10-Q
- Truist Financial Corporation Q3 2026 earnings presentation (8-K Ex. 99.3)
- Truist Financial Corporation Q3 2026 quarterly performance summary (8-K Ex. 99.2)
- Truist Financial Corporation Q3 2026 earnings release (8-K Ex. 99.1)
08What could go wrong
What could go wrong for Truist?
- Pricing
Interest rates and deposit costs
The FY2025 10-K says changes in interest rates have affected net interest income and could again. Deposits that pay no interest fell from $145.9 billion at Dec 31, 2021 to $105.1 billion at Dec 31, 2025.
Watch The net interest margin (3.00% in Q3 FY2026) and the noninterest-bearing deposit total each quarter.
- Other
Loans that are not repaid
Net charge-offs, loans written off minus recoveries, were $1,705 million in FY2025, or 0.54% of average loans. The commercial real estate charge-off rate was 1.31% in FY2024 and 0.62% in FY2025.
Watch The net charge-off ratio: 0.77% in Q3 FY2026, or 0.38% excluding the Regional Acceptance sale, as the company states it.
- Execution
Losses from selling securities
A 2024 balance sheet repositioning produced $6.7 billion of pre-tax securities losses. In Q3 FY2026 Truist sold $8.6 billion of securities yielding 2.67% for a $1,447 million pre-tax loss and bought $7.2 billion yielding 5.60%.
Watch Any further securities sale tied to the LightStream deal, which the Oct 16, 2026 presentation mentions as possible.
- Regulation
Regulation and capital rules
The Federal Reserve, the FDIC and the North Carolina banking commissioner supervise Truist, among others. The 10-K says extensive and changing regulation could hurt its business.
Watch The CET1 ratio (10.7% at Sep 30, 2026) and changes to capital rules.
- Execution
New CEO and asset sales
Mike Lyons became CEO on Aug 31, 2026. Truist agreed on Oct 14, 2026 to sell $7.7 billion of LightStream loans, which its Q3 FY2026 10-Q (Oct 28, 2026) said was expected to close in Q4 2026. The 10-K lists ineffective execution of strategic initiatives as a risk.
Watch Whether the LightStream sale closes in Q4 2026, and ROTCE against the 15% goal management named for 2027.
- Other
Goodwill write-downs
Truist wrote down $6,078 million of goodwill in 2023, and $17,125 million of goodwill remained at Sep 30, 2026. The 10-K says depressed stock values and weak economic conditions could require further write-downs.
Watch Goodwill impairment tests described in the 10-K and 10-Qs.
- Concentration
Concentration in a few states
Florida, Georgia, Virginia and North Carolina held 22%, 21%, 14% and 13% of Truist's deposits, per the FY2025 10-K. The 10-K also names natural disasters and extreme weather as risks.
Watch Deposit and loan trends in its largest states.
Sources (7)
- Truist Financial Corporation FY2025 Form 10-K
- Truist Financial Corporation FY2021 Form 10-K
- Truist Financial Corporation Q3 2026 quarterly performance summary (8-K Ex. 99.2)
- Truist Financial Corporation Q3 2026 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q3 2026 earnings presentation (8-K Ex. 99.3)
- Truist Financial Corporation Q3 2026 Form 10-Q
- Truist Financial Corporation Q2 2026 earnings presentation (8-K Ex. 99.3)
09Supporters vs. critics
What do supporters and critics point to?
What supporters point to
- Truist's net interest margin rose from 2.86% in FY2021 to 3.03% in FY2025.
- Using FDIC data at Jun 30, 2025, Truist's FY2025 10-K ranks it 1st by deposits in Georgia and 2nd in North Carolina.
- Truist returned $5.2 billion to common shareholders in FY2025, and bought back $1.1 billion, $1.2 billion and $1.2 billion of stock in Q1 to Q3 FY2026.
- The holding company's CET1 capital ratio was 10.7% at Sep 30, 2026, up from 9.0% at Dec 31, 2022.
- Wholesale Banking net income rose to $4,102 million in FY2025 from $3,856 million in FY2024.
What critics point to
- Truist's deposits that pay no interest fell from $145.9 billion at Dec 31, 2021 to $105.1 billion at Dec 31, 2025.
- A $6,078 million goodwill write-down gave Truist a FY2023 net loss to common shareholders of $1,452 million, and FY2024 revenue included $6.7 billion of securities losses.
- In Q3 FY2026 Truist took a further $1,447 million pre-tax loss on securities it sold, and net income to common shareholders fell to $684 million from $1,519 million in Q2.
- Return on average common equity was 8.4% in FY2025, down from 10.4% in FY2022.
- Net charge-offs, loans written off minus recoveries, rose from $697 million in FY2021 to $1,705 million in FY2025.
10What to watch next
What should you watch next at Truist?
Next event
Q4 FY2026 results
Date not announced yet.
The LightStream loan sale
Truist agreed on Oct 14, 2026 to sell $7.7 billion of LightStream loans to Carlyle. Its Q3 FY2026 10-Q (Oct 28, 2026) said the sale was expected to close in Q4 2026, subject to closing conditions.
Management's Q4 2026 outlook
In its Oct 16, 2026 presentation, management said it expected Q4 2026 taxable-equivalent revenue of about $5.35 billion and a net charge-off ratio of about 0.45%.
Deposits and the interest margin
The net interest margin was 3.00% in Q3 FY2026. Deposits that pay no interest were $105.1 billion at Dec 31, 2025, down from $145.9 billion at Dec 31, 2021.
Share buybacks
Truist bought back $1.2 billion of stock in Q3 FY2026, and $6.5 billion of the board's $10.0 billion authorization remained at Sep 30, 2026.
11Key facts
Key facts about Truist
- What does Truist do?
- Truist Financial Corporation, based in Charlotte, North Carolina, owns Truist Bank. Truist Bank takes deposits and lends to people, small businesses and companies through 1,927 branches (Dec 31, 2025) and a digital platform.
- How does Truist make money?
- Truist makes most of its money from net interest income, the interest it earns minus the interest it pays: $14.4 billion of its $20.3 billion revenue in FY2025. Fees added the rest, including wealth management ($1,431 million) and card and treasury management ($1,360 million).
- Who are Truist's customers?
- Truist's Consumer and Small Business Banking segment brought in 51.9% and its Wholesale Banking segment 48.1% of the two segments' combined FY2025 revenue of $22,481 million (Cityfort calculation from the FY2025 10-K). Truist's filings do not give revenue by customer.
- How big is Truist?
- Truist reported FY2025 revenue of $20,319 million, income before income taxes of $6,349 million and net income to common shareholders of $4,974 million. It had $547.5 billion of assets and $400.4 billion of deposits at Dec 31, 2025.
- Who owns Truist?
- Truist has one class of common stock with one vote per share, and 1,198,488,412 shares were outstanding at Sep 30, 2026. Truist's 2026 proxy shows directors and executive officers owning less than 1% at Feb 19, 2026, and lists Vanguard (9.5%), Capital International Investors (8.6%) and BlackRock (7.9%).
- How did Truist do in Q3 FY2026?
- Truist's Q3 FY2026 revenue was $3,747 million and net income to common shareholders was $684 million, down from $1,519 million in Q2 FY2026. Q3 included a $1,447 million pre-tax loss on securities Truist sold.
- Who runs Truist?
- Mike Lyons became Truist's President and Chief Executive Officer on Aug 31, 2026, according to Truist's Q3 FY2026 10-Q. He succeeded William Rogers, CEO since September 2021.
Sources (6)
- Truist Financial Corporation FY2025 Form 10-K
- Truist Financial Corporation Q3 2026 Form 10-Q
- Truist Financial Corporation 2026 proxy statement (DEF 14A)
- Truist Financial Corporation Q3 2026 quarterly performance summary (8-K Ex. 99.2)
- Truist Financial Corporation Q3 2026 earnings release (8-K Ex. 99.1)
- Truist Financial Corporation Q3 2026 earnings presentation (8-K Ex. 99.3)
Terms on this page
- Allowance for credit losses
- CET1 ratio
- Dividend payout ratio
- Earnings per share (EPS)
- Efficiency ratio
- Net charge-offs
- Net interest income and margin
- Stock buyback
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does Truist sell?
Consumer and small business banking
Checking and savings accounts, mortgages, home equity loans, auto loans made through car dealers, personal loans and credit cards for households and small firms.
Commercial and corporate banking
Loans, treasury management and merchant services for companies. Commercial and industrial loans were $167.8 billion of the $328.6 billion loan book at Dec 31, 2025.
Investment banking and capital markets
Advice and help raising money for companies, plus trading; this brought in $1,136 million of income in FY2025.
Wealth management
Advice, trust, brokerage and asset management for wealthier clients; wealth management income was $1,431 million in FY2025.
Think of it like this
A bank works like a middleman for money: it pays savers interest on deposits and charges borrowers a higher rate on loans.
What it does
- Does: Takes deposits: $400.4 billion at Dec 31, 2025
- Does: Lends to companies and households: $328.6 billion of loans held for investment at Dec 31, 2025
- Does: Earns fees from wealth management, cards, payments and investment banking
What it does not do
- Does not: Own an insurance broker any more: Truist sold its majority stake in Truist Insurance Holdings on May 6, 2024
- Does not: Belong to the Federal Reserve System as a member bank: Truist Bank is a North Carolina state-chartered bank regulated by the state banking commissioner and the FDIC
13How the money flows
13How the money flows · FY2025
How does money flow through Truist?
Money in
- Interest earned on loans, securities and other assets$24.5B
- Fees and other noninterest income$5.9B
The company
Truist
$30.4B came in
Money out
- Interest paid to depositors and lenders$10.1B
- Employees$6.8B
- Technology, offices, marketing and other costs$5.2B
- Provision for credit losses$1.9B
- Income tax$1.0B
- Net income$5.3B
- Customers held $400.4 billion of deposits at Truist at the end of FY2025.
- Truist lent and invested that money and earned $24.5 billion of interest in FY2025.
- It earned another $5.9 billion of fees and other income from wealth management, cards, payments and investment banking.
- It paid $10.1 billion of interest to depositors and lenders, then staff, other costs, credit losses and tax.
- What was left, $5.3 billion, was net income; $5.0 billion of it belonged to common shareholders.
14What it needs to run
14What it needs to run
What does Truist need to run?
Deposits
Deposits were $400.4 billion at Dec 31, 2025, of which $105.1 billion paid no interest. The average cost of all deposits was 1.78% in FY2025.
Branches and local market share
Truist had 1,927 branches at Dec 31, 2025. Using FDIC data at Jun 30, 2025, the 10-K ranks it 1st by deposits in Georgia and 2nd in North Carolina and West Virginia.
Capital
CET1 capital is the common equity a bank holds against its risk-weighted assets. The holding company's CET1 ratio was 10.8% at Dec 31, 2025 and 10.7% at Sep 30, 2026.
Borrowed money
Besides deposits, Truist had $27.8 billion of short-term borrowings and $42.0 billion of long-term debt at Dec 31, 2025.
People
Truist had 38,711 employees, which it calls teammates, at Dec 31, 2025; personnel expense was $6,848 million in FY2025.
15Where growth could come from
15Where growth could come from
Where could Truist's growth come from?
In its Q3 FY2026 earnings presentation of Oct 16, 2026, management said it expected fourth-quarter 2026 taxable-equivalent revenue of about $5.35 billion, noninterest expense up 2.5%, a net charge-off ratio of about 0.45% and about $1 billion of share repurchases. That outlook excludes potential strategic actions.
Wholesale Banking
WorkingNet income $4,102M in FY2025 vs $3,856M
The FY2025 10-K names growth in Wholesale Banking as a strategic priority. The segment's average loans rose $4.6 billion, or 2.6%, in FY2025.
Status: Working, on track against what the company said.
Consumer deposits
MixedSegment average deposits +0.8% in FY2025
The 10-K names deposit growth focused on Premier clients as a consumer banking priority. Consumer and Small Business Banking net interest income fell $395 million in FY2025 while its average loans rose 5.0%.
Status: Mixed, partly on track.
Selling loan portfolios
New$5.5B auto loan portfolio sold in Q3 FY2026
Truist completed the sale of its Regional Acceptance auto loans in Q3 FY2026. On Oct 14, 2026 it agreed to sell $7.7 billion of LightStream loans to Carlyle; its Q3 FY2026 10-Q (Oct 28, 2026) said the sale was expected to close in Q4 2026, subject to closing conditions.
Status: New, recently announced.
Share buybacks
Mixed$1.2B repurchased in Q3 FY2026
Management's Jul 17, 2026 presentation projected about $5 billion of repurchases in 2026. Truist bought back $1.1 billion in Q1, $1.2 billion in Q2 and $1.2 billion in Q3 FY2026. Its Oct 16, 2026 presentation projected about $1 billion of repurchases for Q4 2026.
Status: Mixed, partly on track.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (6)
- Truist Financial Corporation Q3 2026 earnings presentation (8-K Ex. 99.3)
- Truist Financial Corporation FY2025 Form 10-K
- Truist Financial Corporation Q3 2026 Form 10-Q
- Truist Financial Corporation Q2 2026 earnings presentation (8-K Ex. 99.3)
- Truist Financial Corporation Q1 2026 Form 10-Q
- Truist Financial Corporation Q2 2026 Form 10-Q
16The company's own measures (non-GAAP)
16The company's own measures · FY2025 and Q3 FY2026
What do Truist's own measures show?
Official (GAAP): Return on average common equity, FY2025
8.4%
Company's own measure: Return on average tangible common equity (ROTCE), FY2025
12.7%
Net income to common shareholders plus after-tax intangible amortization, divided by average tangible common equity, as Truist defines it.
Official (GAAP): Return on average common equity, FY2023
−2.6%
Company's own measure: ROTCE, FY2023
18.9%
Excludes the $6,078 million goodwill impairment, which the GAAP return includes.
Official (GAAP): Book value per common share, Dec 31, 2025
$47.74
Company's own measure: Tangible book value per share, Dec 31, 2025
$33.48
Common equity minus goodwill and other intangibles, per share, as Truist defines it.
Official (GAAP): Diluted EPS, Q3 FY2026
$0.56
Company's own measure: Adjusted diluted EPS, Q3 FY2026
$1.16
Excludes the Regional Acceptance loan sale and the securities repositioning, as Truist defines it.
Official (GAAP): Book value per common share, Sep 30, 2026
$46.78
Company's own measure: Tangible book value per share, Sep 30, 2026
$31.90
Common equity minus goodwill and other intangibles, per share, as Truist defines it.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
17Financial strength: capital, loan losses, deposits
17Financial strength · FY2025
How strong is Truist's balance sheet?
- Loans made$328.6B
- Deposits taken$400.4B
- of which pay no interest$105.1B
Loans were 82.1% of deposits at the end of FY2025 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 26.2% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 10.8%
- common equity capital as a share of risk-weighted assets (holding company); regulators set a minimum
- Allowance for credit losses
- $5.0B
- money set aside for expected loan losses: 1.53% of loans
- Net charge-offs
- $1.7B
- loans written off, minus recoveries: 0.54% of average loans
- Efficiency ratio
- 59.4%
- $ of noninterest expense per $100 of revenue (net interest income + noninterest income)
- Return on equity
- 8.4%
- net income as % of average common equity
- Return on tangible common equity
- 12.7%
- the company's own measure (non-GAAP): equity without goodwill and other intangibles
Figures at the end of FY2025, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
18Who owns it
18Who owns it · ownership as of Feb 19, 2026
Who owns Truist?
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes
19What it does with profit
19What it does with profit
What does Truist do with its profit?
Dividend per share
$2.08FY2025
Dividend paid for each share, by financial year.
$ per share
See the numbers
Buyback · Dec 31, 2025
FY2025: $2.5 billion of common shares repurchased. In December 2025 the board authorized repurchases of up to $10.0 billion, with no expiration date.
$2.5B
Buyback · Mar 31, 2026
Q1 FY2026: $1.1 billion repurchased; $8.9 billion of the authorization remained at Mar 31, 2026.
$1.1B
Buyback · Jun 30, 2026
Q2 FY2026: $1.2 billion repurchased; $7.7 billion remained at Jun 30, 2026.
$1.2B
Buyback · Sep 30, 2026
Q3 FY2026: $1.2 billion repurchased; $6.5 billion remained at Sep 30, 2026.
$1.2B
20Governance signals
20Governance signals
What do Truist's governance filings show?
- Auditor
- PricewaterhouseCoopers LLP, since 2002
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy says Truist does routine business on arm's-length terms with its 5% holders (Vanguard, Capital International and BlackRock), including technology products bought from BlackRock affiliates.
- Credit rating
- S&P, Moody's, Fitch and DBRS Morningstar (as stated in the Q3 FY2026 10-Q, at Sep 30, 2026) A- (S&P) / Baa1 (Moody's) / A (Fitch) / AAL (DBRS Morningstar) for Truist Financial Corporation as issuer; Truist Bank A / A3 / A / AA (outlook Stable (all four)), Sep 30, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
other · Oct 28, 2026
Chair and CEO roles
The 2026 proxy says the board has not adopted a policy on separating the chair and CEO roles. William Rogers held both until the 2026 succession, under which Mike Lyons became CEO and Rogers was to serve as Executive Chair.
21How it got here
21How it got here
How did Truist get here?
1872
Milestone
Truist Bank chartered
Truist Bank was chartered in 1872; the FY2025 10-K calls it the oldest bank headquartered in North Carolina.
2019
Business-model change
BB&T and SunTrust merge
Truist was formed by the merger of equals of BB&T and SunTrust, effective Dec 6, 2019.
2023
Crisis
$6.1 billion goodwill write-down
A $6,078 million goodwill impairment gave Truist a FY2023 net loss to common shareholders of $1,452 million.
2024
Business-model change
Insurance broker sold
Truist sold its majority stake in Truist Insurance Holdings on May 6, 2024, to investors led by Stone Point Capital and Clayton, Dubilier & Rice, at a price implying a $15.5 billion enterprise value.
2024
Milestone
Securities sold at a loss
FY2024 revenue of $13.3 billion includes $6.7 billion of securities losses from a balance sheet repositioning.
2025
Milestone
$10 billion buyback authorized
In December 2025 the board authorized repurchases of up to $10.0 billion of common stock, with no expiration date.
2026
Milestone
New CEO
Mike Lyons became President and CEO on Aug 31, 2026, succeeding William Rogers, CEO since September 2021.
2026
Business-model change
Loan books sold
Truist sold its Regional Acceptance auto loans ($5.5 billion portfolio, $5.2 billion price) in Q3 FY2026 and agreed on Oct 14, 2026 to sell LightStream loans to Carlyle.
22Sources and changes
Where every number on this page comes from
Sources (23 documents)
- S1Truist Financial Corporation FY2025 Form 10-K · SEC EDGAR · Tier 1: company or exchange filing · Feb 24, 2026
- S2Truist Financial Corporation FY2024 Form 10-K · SEC EDGAR · Tier 1: company or exchange filing · Feb 25, 2025
- S3Truist Financial Corporation FY2023 Form 10-K · SEC EDGAR · Tier 1: company or exchange filing · Feb 27, 2024
- S4Truist Financial Corporation FY2022 Form 10-K · SEC EDGAR · Tier 1: company or exchange filing · Feb 28, 2023
- S5Truist Financial Corporation FY2021 Form 10-K · SEC EDGAR · Tier 1: company or exchange filing · Feb 23, 2022
- S6Truist Financial Corporation Q3 2026 Form 10-Q · SEC EDGAR · Tier 1: company or exchange filing · Oct 28, 2026
- S7Truist Financial Corporation Q2 2026 Form 10-Q · SEC EDGAR · Tier 1: company or exchange filing · Jul 31, 2026
- S8Truist Financial Corporation Q1 2026 Form 10-Q · SEC EDGAR · Tier 1: company or exchange filing · May 1, 2026
- S10Truist Financial Corporation Q2 2025 Form 10-Q · SEC EDGAR · Tier 1: company or exchange filing · Jul 31, 2025
- S11Truist Financial Corporation Q1 2025 Form 10-Q · SEC EDGAR · Tier 1: company or exchange filing · Apr 30, 2025
- S12Truist Financial Corporation Q3 2026 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Oct 16, 2026
- S13Truist Financial Corporation Q2 2026 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Jul 17, 2026
- S14Truist Financial Corporation Q1 2026 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Apr 17, 2026
- S15Truist Financial Corporation Q4 2025 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Jan 21, 2026
- S16Truist Financial Corporation Q3 2025 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Oct 17, 2025
- S17Truist Financial Corporation Q2 2025 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Jul 18, 2025
- S18Truist Financial Corporation Q1 2025 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Apr 17, 2025
- S19Truist Financial Corporation Q4 2024 earnings release (8-K Ex. 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Jan 17, 2025
- S20Truist Financial Corporation Q3 2026 quarterly performance summary (8-K Ex. 99.2) · SEC EDGAR · Tier 1: company or exchange filing · Oct 16, 2026
- S21Truist Financial Corporation Q2 2026 quarterly performance summary (8-K Ex. 99.2) · SEC EDGAR · Tier 1: company or exchange filing · Jul 17, 2026
- S22Truist Financial Corporation Q3 2026 earnings presentation (8-K Ex. 99.3) · SEC EDGAR · Tier 1: company or exchange filing · Oct 16, 2026
- S23Truist Financial Corporation Q2 2026 earnings presentation (8-K Ex. 99.3) · SEC EDGAR · Tier 1: company or exchange filing · Jul 17, 2026
- S24Truist Financial Corporation 2026 proxy statement (DEF 14A) · SEC EDGAR · Tier 1: company or exchange filing · Mar 16, 2026
Changes to this page (v1 · Nov 20, 2026)
- v1 · Nov 20, 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.