Financials · NYSE: ALL
Allstate: how the business works
Allstate sells car, home and other insurance to households in the US and Canada, with 211 million policies in force and total revenues of $67,685 million in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow Allstate
Email me when Allstate's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
The Allstate Corporation · Northbrook, Illinois · Founded 1992
Updated for Q3 FY2026 · checked
- Total revenues, FY2025
- $67.7B
- Net income to common shareholders, FY2025
- $10.2B
- Policies in force, Dec 31, 2025
- 211 million
- Combined ratio, FY2025
- 85.2
- Full-time employees, Dec 31, 2025
- About 53,000
The short version
Allstate in 5 points
1 · What it sells
Allstate sells car, home and other insurance to households in the US and Canada, with 211 million policies in force at Dec 31, 2025 and total revenues of $67,685 million in FY2025.
2 · Who pays it
In FY2025, households buying car, home and other policies through Allstate Protection paid 85.2% of revenue, buyers of protection plans and roadside, dealer and identity products 5.0%, investment income 5.1%, and fees and other revenue 4.7%.
3 · What it keeps from $100
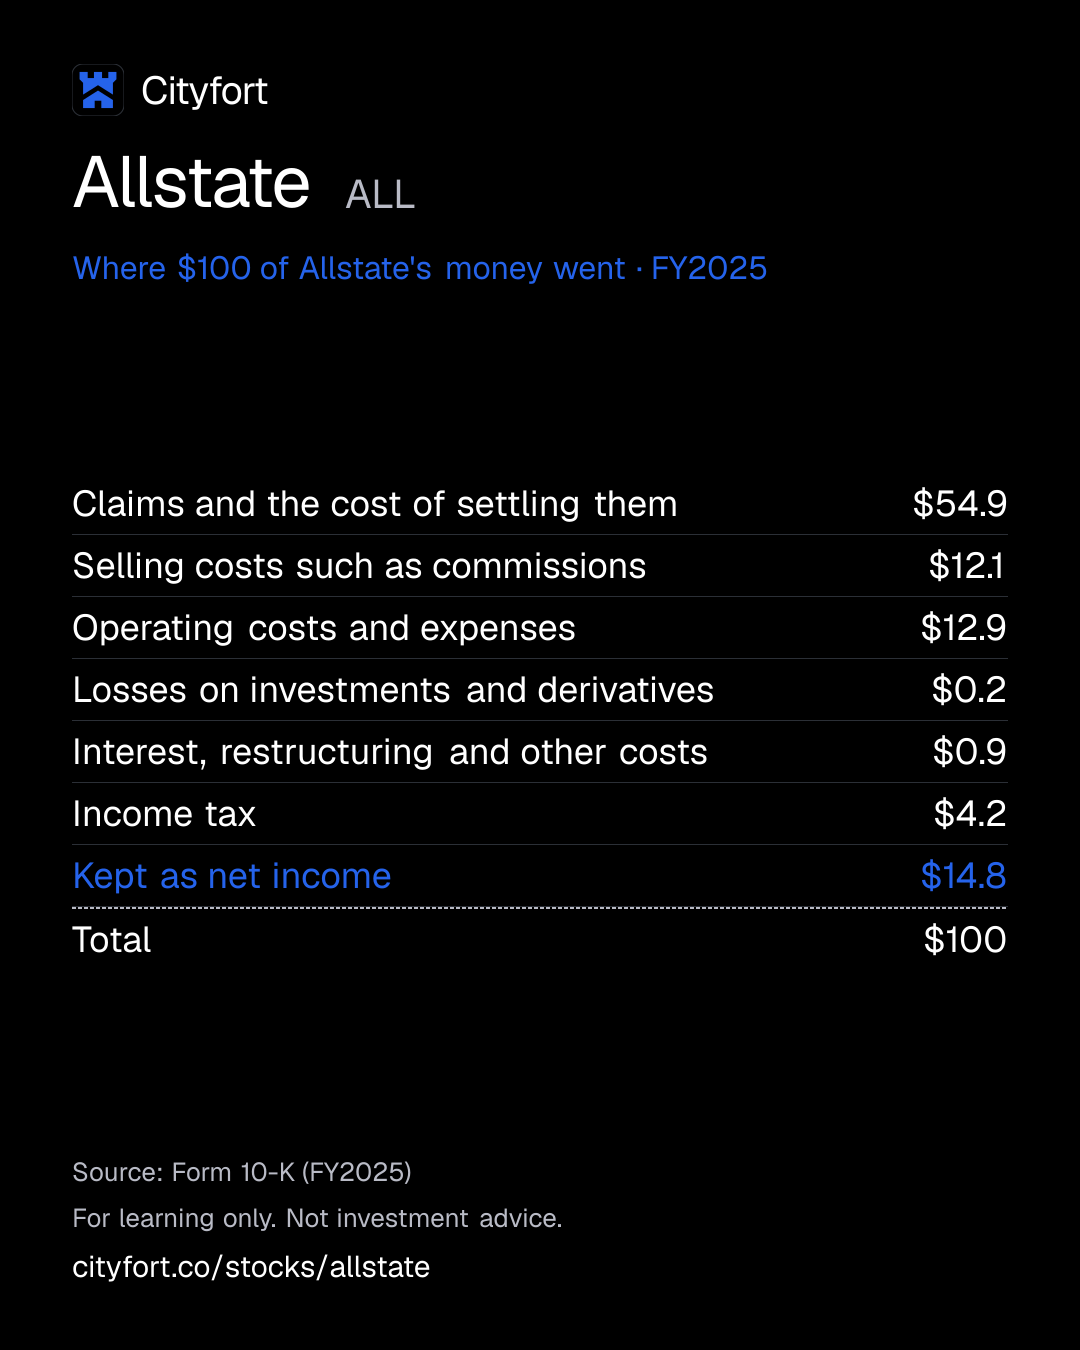
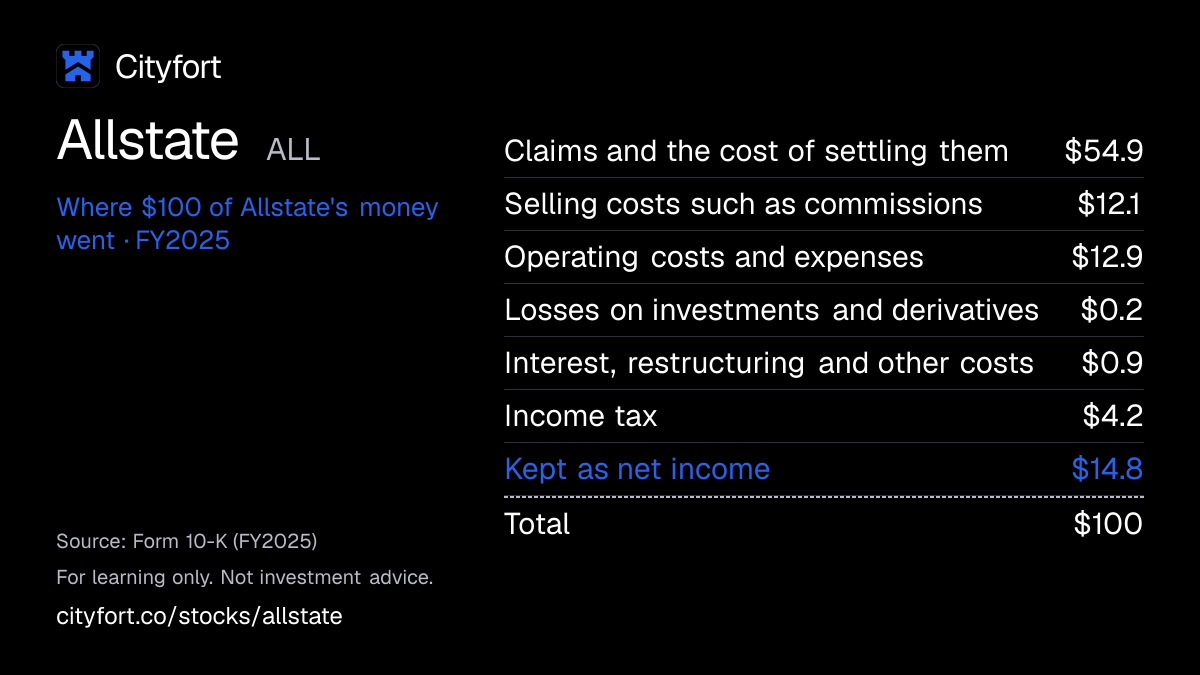
Of every $100 that came in during FY2025, Allstate spent $54.9 on claims and kept $14.8 as net income, which includes a one-time $1,603 million gain on selling two benefits businesses; its operating result from insurance, underwriting income, was $8,540 million.
4 · Where the operating profit comes from
In FY2025, auto insurance made $5,724 million of underwriting income and homeowners insurance $2,393 million, and investments added $3,449 million of net investment income.
5 · The one thing to watch
The combined ratioAn insurer's claims plus underwriting costs, per $100 of premiums earned. Under 100% means premiums covered both., claims and costs per $100 of premiums earned, was 86.6 in Q3 FY2026, against 80.1 in Q3 FY2025.
Sources: From Allstate's FY2025 10-K, its Q3 FY2026 10-Q and its investor supplements for Q4 FY2025 and Q3 FY2026 · checked
01Where $100 of an insurer's money goes · FY2025
Where does $100 of Allstate's money go?
Allstate · FY2025
Receipt for every $100
| Claims and the cost of settling them | $54.9 |
|---|---|
| Selling costs such as commissions | $12.1 |
| Operating costs and expenses | $12.9 |
| Losses on investments and derivatives | $0.2 |
| Interest, restructuring and other costs | $0.9 |
| Income tax | $4.2 |
| Kept as net income | $14.8 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Money in = premiums $61,449 million + net investment income $3,449 million + other revenue $2,955 million + the $1,603 million gain on selling businesses = $69,456 million; each line = line ÷ $69,456 million × 100. Net losses on investments ($168 million) are shown as a cost.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report earnings, explained in 5 points.
No tips. Unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does Allstate do?
Households pay Allstate premiums to insure their cars and homes; most of that money goes on claims, and what is left after costs, plus income from investing the premiums, is profit.
- Allstate Protection's earned premiums, mostly from car and home policies, were 85.2% of FY2025 revenue, the 10-K says.
- Claims and the cost of settling them took $38,110 million in FY2025. Net income applicable to common shareholders was $10,165 million, including a one-time $1,603 million pre-tax gain on selling two benefits businesses.
03Who pays it
Who pays Allstate?
Households buying car, home and other insurance (Allstate Protection)
85.2%
of revenue
Pay premiums for auto, homeowners and other policies; this segment's earned premiums were 85.2% of FY2025 revenue, the 10-K says.
Buyers of protection plans, roadside, dealer and identity products (Protection Services)
5%
of revenue
Shoppers, car buyers and companies pay for these plans and services; the segment was 5.0% of FY2025 revenue.
Borrowers and markets that pay on Allstate's investments
5.1%
of revenue
Bonds, stocks and funds bought with premium money paid $3,449 million of net investment income in FY2025, 5.1% of revenue (Cityfort calculation from the FY2025 10-K: $3,449 million ÷ $67,685 million).
Fees and other revenue
4.7%
of revenue
The other 4.7% of FY2025 revenue (Cityfort calculation from the FY2025 10-K: 100% minus the shares above) is mostly fees and accident and health premiums, net of $168 million of investment losses.
- Households buying car, home and other insurance (Allstate Protection)85.2%
- Buyers of protection plans, roadside, dealer and identity products (Protection Services)5%
- Borrowers and markets that pay on Allstate's investments5.1%
- Fees and other revenue4.7%
How spread out the customers are
Allstate insures millions of households, with 211 million policies in force at Dec 31, 2025. The FY2025 10-K reports no customer that makes up a large share of revenue.
Sources (1)
04How it makes money
How does Allstate make money?
Allstate profits when premiums cover claims and costs, and again on the money it invests in between.
The combined ratio is claims plus costs per $100 of premiums earned; below 100 means underwriting made money. Allstate's was 106.6 in FY2022 and 85.2 in FY2025. The premiums it holds also earned $3,449 million of investment income in FY2025.
Combined ratio (claims and costs per $100 of premiums earned)
95.985.2
FY2021 to FY2025
- Households pay premiums for car and home policies
- Allstate invests the money until claims are paid
- Accidents and storms bring claims, which swing from year to year
- Allstate asks state regulators to approve new prices
- When prices cover claims and costs, the combined ratio falls below 100
- Underwriting income plus investment income becomes profit
↺ Step 6 feeds back into step 1.
05Business segments · FY2025
Which businesses make up Allstate?
Auto insurance
61.8%Premiums written for car insurance in Allstate Protection; underwriting income was $5,724 million in FY2025.
Revenue $38.6B ($38,649M)
Homeowners insurance
26.5%Premiums written for home insurance; underwriting income was $2,393 million in FY2025.
Revenue $16.6B ($16,565M)
Other personal and commercial lines
6.9%Other personal lines ($3,265 million), commercial ($402 million) and other business lines ($665 million), premiums written.
Revenue $4.3B ($4,332M)
Protection Services
4.8%Premiums written for protection plans, roadside, dealer and identity products.
Revenue $3.0B ($3,006M)
How the mix changed
- Auto insurance
- Homeowners insurance
- Other personal and commercial lines
- Protection Services
Revenue by segment, FY2024 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has Allstate done?
Premiums earned
$57.7BFY2025
Property-Liability premiums written rose every year, from $41,358 million in FY2021 to $59,546 million in FY2025.
US$ · net premiums earned: the part of premiums that covers the period, after reinsurance
See the yearly numbers
See the quarterly numbers
Combined ratio
85.2%FY2025
The combined ratio was above 100, meaning an underwriting loss, in FY2022 and FY2023, and was 85.2 in FY2025.
Allstate's ratios cover Property-Liability (Allstate Protection plus run-off business), and its expense ratio nets that business's other revenue (fees) against underwriting costs.
% of premiums earned · claims plus underwriting costs per $100 of premiums, as reported; under 100% means premiums covered both
See the yearly numbers
See the quarterly numbers
Net income
$10.2BFY2025
FY2025 net income applicable to common shareholders was $10,165 million, with $8,540 million of underwriting income and $3,449 million of investment income; it includes a $1,603 million pre-tax gain on selling businesses.
US$ · after claims, costs, investment results and tax; the table shows where it came from
See the numbers
Catastrophe losses
$5.0BFY2025
Catastrophe losses ranged from $3,112 million to $5,636 million a year in FY2021 to FY2025, adding 7.1 to 11.6 points to the combined ratio.
US$ · claims from storms, wildfires and other events the company counts as catastrophes, as reported
See the numbers
See all yearly numbers
Loss ratio = losses and loss adjustment expenses ÷ net premiums earned. Expense ratio = underwriting costs ÷ net premiums earned. Combined ratio = loss ratio + expense ratio, as the company reports them. Net investment income is interest and dividends on the money the company holds before paying claims; realized and unrealized gains are shown apart because they move with markets. Net income is the amount for common stockholders. Fiscal years are the company's own (Fiscal year ends Dec 31).
- Premiums, claims and the loss, expense and combined ratios are for Property-Liability, as Allstate reports them; they leave out Protection Services.
- Underwriting expenses = amortization of acquisition costs + operating costs + restructuring + amortization of purchased intangibles, minus Property-Liability other revenue, matching the company's expense ratio (Cityfort calculation from the FY2025 and FY2023 10-Ks).
- Fees and other = Protection Services premiums earned + accident and health premiums + other revenue; FY2025: $2,821 million + $946 million + $2,955 million (Cityfort calculation from the FY2025 10-K and the Q4 FY2025 investor supplement).
- Realized gains = sales, credit losses and derivatives; unrealized gains = the change in value of equity investments, which passes through net income (Cityfort calculation from the Q4 FY2025 investor supplement and the FY2023 10-K).
- Net income is applicable to common shareholders: net income attributable to Allstate minus preferred dividends ($10,282 million minus $117 million in FY2025). FY2021 includes a $3,593 million loss from discontinued operations tied to the Allstate Life sale.
- Changes to earlier years' claim reserves added $1,744 million to FY2022 claims and cut FY2025 claims by $1,810 million.
- Book value per share and ROE for FY2021 are as first reported; FY2022 is as restated in the FY2023 10-K for a new accounting rule on long-duration insurance contracts ($58.07 and -7.3% as first reported).
- Policies in force are as stated in each year's 10-K and include Protection Services plans; the Q4 FY2025 investor supplement restates FY2024 to 204.7 million without the businesses sold in 2025.
Learn: What is the combined ratio? Claims plus costs, with real US insurers · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What is return on equity? Profit on equity, with real US companies · Fiscal years that don't end in December: Nvidia's FY2027 explained
07Who runs it
Who runs Allstate, and did they deliver?
Thomas J. Wilson
Chair, President and Chief Executive Officer · since 2007
CEO since Jan 2007 and Chair since May 2008.
John E. Dugenske
Chief Financial Officer · since 2025
CFO since Oct 2025; also President, Investments and Corporate Strategy since Sep 2022.
Mario Rizzo
Chief Operating Officer · since 2025
President, Property-Liability from Sep 2022 to Oct 2025.
Jesse E. Merten
President, Property-Liability · since 2025
CFO from Sep 2022 to Oct 2025.
Andrea M. Carter
Chief Human Resources Officer · since 2025
What they said, and what happened
3 too early to tell
Said on Feb 4, 2026
The board approved a $4.00 billion share buyback on Feb 4, 2026, to be completed by Feb 29, 2028.
Too early to tellWhat happened
$1.35 billion of the program was left at Sep 30, 2026, the Q3 FY2026 10-Q says.
Said on Nov 4, 2026
Arity agreed in Nov 2026 to buy the rest of Replica, with closing expected before the end of 2026.
Too early to tellWhat happened
Not yet reported.
Said on Nov 4, 2026
CEO Tom Wilson said in the Q3 FY2026 earnings release that more capabilities are planned for early 2027 for ALLIE, Allstate's AI system for service calls.
Too early to tellWhat happened
Not yet reported.
08What could go wrong
What could go wrong for Allstate?
- Other
Catastrophes and severe weather
Catastrophe losses were $5,636 million in FY2023 and $4,959 million in FY2025. In Q1 FY2025 catastrophes added 49.9 points to homeowners' combined ratio, which reached 112.3.
Watch Catastrophe losses each quarter, which Allstate also reports monthly in 8-K filings.
- Pricing
Claim cost and reserve estimates
The 10-K lists the uncertainty of loss cost estimates and reserves first among its risks. Changes to earlier years' reserves added $1,744 million to FY2022 claims and cut FY2025 claims by $1,810 million.
Watch Prior-year reserve reestimates in the quarterly investor supplement.
- Regulation
Getting rate increases approved
Many states must approve insurers' price changes, and the 10-K lists that approval as a risk. Net auto rate changes implemented in Q3 FY2026 were +0.4%.
Watch Implemented auto and homeowners rate changes each quarter.
- Competition
Competition in car and home insurance
The 10-K calls personal lines insurance highly competitive. The Allstate-brand average auto premium written fell from $858 in Q4 FY2024 to $811 in Q3 FY2026.
Watch Auto policies in force and the average auto premium.
- Other
Investment market swings
Net gains on investments and derivatives were $1,055 million in Q2 FY2026 and a $545 million loss in Q3 FY2026. Equity securities were $10,172 million of the portfolio at Sep 30, 2026.
Watch Net gains and losses on investments in each quarter's results.
- Legal
Lawsuits over driving data and National General
Suits allege privacy and consumer protection claims over driving behavior data. A Justice Department suit alleges a banking-law violation by National General; both seek money.
Watch The legal proceedings note in each 10-Q.
09Supporters vs. critics
What do supporters and critics point to?
What supporters point to
- The Property-Liability combined ratio fell from 106.6 in FY2022 to 85.2 in FY2025, and underwriting income was $8,540 million in FY2025.
- Auto policies in force reached 26.2 million at Sep 30, 2026, up from 24.9 million at Dec 31, 2024.
- Protection Services revenue rose 6.9% to $964 million in Q3 FY2026, from $902 million a year earlier.
- Allstate bought back 13 million shares in the first nine months of FY2026. The quarterly common dividend was $1.08 in Q3 FY2026, up from $1.00 a year earlier.
What critics point to
- Catastrophe losses were $4,959 million in FY2025, and in Q1 FY2025 catastrophes pushed the homeowners combined ratio to 112.3.
- In Q3 FY2026 auto premiums written rose 0.2%, and net auto rate changes implemented were +0.4%. The Allstate-brand average auto premium was $811, down from $858 in Q4 FY2024.
- FY2025 net income includes a one-time $1,603 million pre-tax gain on selling two benefits businesses. Q3 FY2026 net income applicable to common shareholders was $2,050 million, against $3,717 million a year earlier.
- A Justice Department suit alleges that services National General provided to a bank violated a 1989 banking law, and other suits allege privacy claims over driving data.
10What to watch next
What should you watch next at Allstate?
Next event
Q4 and full-year FY2026 results
Date not announced yet.
Combined ratio
It was 86.6 in Q3 FY2026, against 80.1 in Q3 FY2025; below 100 means underwriting made money.
Catastrophe losses
They were $1,650 million in Q3 FY2026, against $558 million a year earlier; Allstate also reports them monthly in 8-K filings.
Auto policies against auto premiums
In Q3 FY2026 auto policies rose 3.4% from a year earlier, while auto premiums written rose 0.2%.
Arity's purchases
Arity bought substantially all assets of INRIX in Oct 2026 and agreed in Nov 2026 to buy the rest of Replica; the filings read give no prices.
11Key facts
Key facts about Allstate
- What does Allstate do?
- The Allstate Corporation sells car, home and other personal insurance to households in all 50 US states, D.C. and Canada. Auto insurance was its biggest line in FY2025, with $38,649 million of premiums written.
- How does Allstate make money?
- Allstate makes money when premiums cover claims and costs, and by investing premiums until claims are paid. In FY2025 Allstate's Property-Liability underwriting income was $8,540 million and its net investment income was $3,449 million.
- Who are Allstate's customers?
- Allstate's customers are mostly households buying car and home insurance. Allstate Protection's earned premiums were 85.2% of Allstate's FY2025 revenue, and Allstate had 211 million policies in force at Dec 31, 2025.
- How big is Allstate?
- Allstate reported total revenues of $67,685 million and net income applicable to common shareholders of $10,165 million in FY2025, up from $64,106 million and $4,550 million in FY2024. Allstate's FY2025 net income includes a $1,603 million pre-tax gain on selling two benefits businesses.
- Who owns Allstate?
- No single holder controls Allstate. Allstate's 2026 proxy lists directors and executive officers as a group with 1.55% of the common stock and BlackRock with 8.4%, from a filing dated Feb 3, 2025.
- What is Allstate's combined ratio?
- Allstate's Property-Liability combined ratio, claims and costs per $100 of premiums earned, was 85.2 in FY2025. It was 106.6 in FY2022 and 104.5 in FY2023, when Allstate lost money on underwriting.
- How much do catastrophes cost Allstate?
- Allstate's catastrophe losses, from events such as storms and wildfires, were $4,959 million in FY2025 and $5,636 million in FY2023.
- Does Allstate pay a dividend?
- Allstate declared common dividends of $4.00 per share in FY2025, up from $3.68 in FY2024. Allstate also bought back 13 million shares in the first nine months of FY2026.
Terms on this page
- Capital expenditures (capex)
- Combined ratio
- Earnings per share (EPS)
- Net margin
- Revenue vs net income
- Stock buyback
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does Allstate sell?
Auto insurance
Covers drivers' cars and the damage they cause to others. Auto premiums written were $38,649 million in FY2025, the biggest line.
Homeowners insurance
Pays to repair or rebuild a home after fire, storms or theft. Homeowners premiums written were $16,565 million in FY2025.
Other personal and commercial lines
Smaller personal policies plus select commercial property and casualty cover. Together they wrote $4,332 million of premiums in FY2025 (Cityfort calculation from the Q4 FY2025 investor supplement).
Protection Plans
Repair or replacement plans for mobile phones, electronics and major appliances, sold through retailers and mobile operators. Revenue was $2,300 million in FY2025.
Roadside, Dealer Services and Identity Protection
Towing and jump-starts, vehicle service contracts sold at car dealerships, and identity theft protection. Their FY2025 revenue was $231 million, $590 million and $159 million.
Arity
A unit that collects and analyzes driving data from phones and cars and sells risk scores, leads and data services. Revenue was $266 million in FY2025.
Think of it like this
An insurer works like a shared rainy-day fund. Many households pay in a little, and the fund pays the few who crash a car or lose a roof.
What it does
- Does: Sells car, home and other personal insurance in all 50 states, D.C. and Canada
- Does: Sells through its own exclusive agents, through independent agents, and directly online and by phone
- Does: Invests the premiums it holds, mostly in bonds, until claims are paid
What it does not do
- Does not: No longer sells life insurance: FY2021 included a $3,593 million loss from discontinued operations tied to the Allstate Life sale
- Does not: No longer sells employer voluntary benefits or group health insurance, both sold in 2025
- Does not: Is not mainly a business insurer: commercial lines wrote $402 million of $59,546 million of premiums in FY2025
13How the money flows
13How the money flows · FY2025
How does money flow through Allstate?
Money in
- Insurance premiums earned (property-liability and protection services)$60.5B
- Accident and health premiums$946M
- Net investment income$3.4B
- Other revenue (fees)$3.0B
- Gain on selling two benefits businesses$1.6B
The company
Allstate
$69.5B came in
Money out
- Claims and the cost of settling them (incl. health benefits)$38.1B
- Selling costs such as commissions (amortized acquisition costs)$8.4B
- Operating costs and expenses$9.0B
- Losses on investments and derivatives$168M
- Interest, restructuring and other costs$656M
- Income tax$2.9B
- Net income (before a $16 million loss that belongs to minority owners)$10.3B
- Households pay premiums for car, home and other policies, and Allstate counts them as revenue over each policy's term.
- Allstate invests the money until claims come in; that earned $3,449 million of net investment income in FY2025.
- Claims and the cost of settling them took $38,110 million, the largest cost.
- Selling costs, running costs, investment losses, interest and tax took $21,080 million more.
- Net income was $10,266 million, including a one-time $1,603 million gain from selling two benefits businesses.
Sources (1)
14What it needs to run
14What it needs to run
What does Allstate need to run?
Agents and direct sales
Allstate sells through exclusive agents, independent agents and its own phone and online channels. In FY2025 they brought 3.13 million, 2.79 million and 2.99 million new auto applications.
Rate approvals from state regulators
In many states an insurer must show regulators its prices are justified before raising them. The 10-K lists getting rate increases approved as a risk.
Catastrophe reinsurance
Reinsurance is insurance that insurers buy for themselves against very large losses. The 10-K lists keeping its catastrophe reinsurance programs and limits as a risk.
An investment portfolio
Premiums are invested until claims are paid: $87,375 million at Sep 30, 2026, of which $60,246 million was bonds and other fixed income.
Driving data
Arity collects and analyzes driving data. The 10-K names wider use of telematics (data from phones and cars) in pricing as part of its growth plan.
Financial strength ratings
Agencies rate whether an insurer can pay claims. Allstate Insurance Company is rated A+ by S&P and A.M. Best and Aa3 by Moody's.
15Where it sells
15Where it sells · FY2025
Where does Allstate sell?
- United States96.7%
- Outside the US (Canada; protection plans also in Europe and Asia)3.3%
Sources (1)
16Where growth could come from
16Where growth could come from
Where could Allstate's growth come from?
Allstate gave no numeric earnings guidance in its Q3 FY2026 release. CEO Tom Wilson said there that Protection Plans' international revenues "are growing rapidly". He added that its AI system, ALLIE, handles millions of service calls, with more capabilities planned for early 2027.
More auto policies
Working26.2 million auto policies, Sep 30, 2026
Up from 24.9 million at Dec 31, 2024. In Q3 FY2026 auto policies rose 3.4% and new auto business 6.3% from a year earlier. Auto premiums written rose only 0.2%.
Status: Working, on track against what the company said.
Homeowners growth
WorkingPremiums written +7.4%, Q3 FY2026
Homeowners policies reached 7.9 million at Sep 30, 2026, up 3.3% from a year earlier, and new homeowners business rose 10.2%.
Status: Working, on track against what the company said.
Protection Services
WorkingRevenue $964 million, Q3 FY2026
Up 6.9% from $902 million a year earlier; Protection Plans brought $631 million of it.
Status: Working, on track against what the company said.
Arity deals
NewINRIX assets bought, Oct 2026
Arity bought substantially all assets of INRIX, a traffic data company, in Oct 2026. In Nov 2026 it agreed to buy the rest of Replica. Prices were not disclosed in the filings read.
Status: New, recently announced.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
17The company's own measures (non-GAAP)
17The company's own measures · Q3 FY2026
What do Allstate's own measures show?
Official (GAAP): Net income applicable to common shareholders, Q3 FY2026
$2.1B
Company's own measure: Adjusted net income, Q3 FY2026
$2.5B
Allstate's measure leaves out investment gains and losses, pension remeasurement, purchased-intangible amortization and gains or losses on selling businesses, after tax.
Official (GAAP): Net income applicable to common shareholders, 12 months to Sep 30, 2026
$11.5B
Company's own measure: Adjusted net income, 12 months to Sep 30, 2026
$11.4B
Same definition over the last four quarters.
Official (GAAP): Recorded combined ratio, Q3 FY2026
86.6%
Company's own measure: Underlying combined ratio, Q3 FY2026
80.5%
Leaves out catastrophe losses and changes to earlier years' claim reserves, among other items, as Allstate defines it.
Official (GAAP): Book value per common share, Sep 30, 2026
$120M
Company's own measure: Book value per share excluding unrealized bond gains and losses, Sep 30, 2026
$128M
In US$ per share. Removes the after-tax effect of bond price changes that have not been realized.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
18Financial strength: investments, debt, capital
18Financial strength · Sep 30, 2026
How strong is Allstate's balance sheet?
What the premiums are invested in
- Bonds and other fixed income$60.2B
69.0% of the investments listed
- Equity securities (stocks)$10.2B
11.6% of the investments listed
- Limited partnership interests$9.1B
10.4% of the investments listed
- Short-term investments$5.8B
6.6% of the investments listed
- Mortgage loans$1.0B
1.2% of the investments listed
- Other investments$1.1B
1.2% of the investments listed
Shares of the portfolio: Cityfort calculation from the Q3 FY2026 10-Q, each type ÷ the total listed.
- Book value per share
- $108.45
- shareholders' equity per share at the end of FY2025, as reported
- Return on equity
- 42.3%
- net income as % of average shareholders' equity, as reported
- Investments
- $87.4B
- money held in bonds, stocks and cash until claims are paid
- Debt
- $7.5B
- borrowings on the balance sheet
- Shareholders' equity
- $32.3B
- what the company owns minus what it owes
- Debt to capital
- 18.8%
- debt ÷ (debt + equity), as reported by the company
- Policies in force
- 211 million
- at the end of FY2025, as reported
Allstate Insurance Company can pay its parent up to $7.98 billion of dividends through Feb 2027 without prior Illinois approval, the Q3 FY2026 10-Q says. Dividends paid in the preceding 12 months count against that limit.
Figures at Sep 30, 2026, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
19Who owns it
19Who owns it · ownership as of Mar 1, 2026
Who owns Allstate?
- Officers and directors (as a group), shares
- 1.6%
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes
20What it does with profit
20What it does with profit
What does Allstate do with its profit?
Dividend per share
$4.00FY2025
Dividend paid for each share, by financial year.
$ per share
See the numbers
Buyback · Dec 31, 2025
Treasury stock purchases in FY2025.
$1.2B
Buyback · Sep 30, 2026
Allstate bought 13 million shares (4.9% of the Dec 31, 2025 count) in the first nine months of FY2026. The $4.00 billion program was approved on Feb 4, 2026, and $1.35 billion of it was left at Sep 30, 2026.
$2.9B
21Governance signals
21Governance signals
What do Allstate's governance filings show?
- Auditor
- Deloitte & Touche LLP, since 1993
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy says a board committee or its chair reviews deals above $120,000 with related persons. These are directors, executive officers, their families and 5% holders with a material interest.
- Credit rating
- S&P Global Ratings, Moody's and A.M. Best (as stated in the Q3 FY2026 10-Q and FY2025 10-K) Senior debt BBB+ (S&P), A3 (Moody's), a- (A.M. Best); Allstate Insurance Company financial strength A+ (S&P), Aa3 (Moody's), A+ (A.M. Best) (outlook Positive (S&P, Aug 2026); stable (A.M. Best, Sep 2026; Moody's, May 2025)), Nov 4, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory · Nov 4, 2026
Justice Department lawsuit over National General
A Justice Department suit filed in July 2024 alleges that services National General provided to a large bank violated a 1989 banking law. The services were for the bank's collateral protection insurance program; the suit seeks civil penalties.
other · Nov 4, 2026
Driving-data lawsuits
The Texas Attorney General and plaintiffs in putative class actions allege privacy and consumer protection claims. The suits concern the collection and use of driving behavior data and seek damages, restitution and injunctive relief.
other · Nov 4, 2026
Exclusive agents' expense lawsuit
Plaintiffs allege they were misclassified as independent contractors and that Allstate owes them business expenses from running exclusive agencies in California. The court decertified the class on Sep 10, 2026; plaintiffs are appealing.
22How it got here
22How it got here
How did Allstate get here?
1992
Milestone
Holding company formed
The Allstate Corporation was incorporated in Delaware on Nov 5, 1992, as the holding company for Allstate Insurance Company.
1995
Business-model change
Separated from Sears
The 2026 proxy refers to employees with Sears, Roebuck and Co. service at the time of the 1995 spin-off.
2007
Milestone
Tom Wilson becomes CEO
Wilson became CEO in Jan 2007 and Chair in May 2008, and still holds both roles.
2021
Business-model change
Exit from life insurance
FY2021 results included a $3,593 million loss from discontinued operations tied to the Allstate Life sale.
2022
Crisis
Two years of underwriting losses
The combined ratio was 106.6 in FY2022 and 104.5 in FY2023, and net income was negative in both years.
2025
Business-model change
Benefits businesses sold
Allstate sold employer voluntary benefits in the first half of 2025 and group health on Jul 1, 2025, booking a $1,603 million gain.
2026
Milestone
Arity buys INRIX assets
Arity, Allstate's driving-data unit, bought substantially all assets of INRIX in Oct 2026.
23Sources and changes
Where every number on this page comes from
Sources (19 documents)
- S1Form 10-Q for Q3 FY2026 · SEC EDGAR · Tier 1: company or exchange filing · Nov 4, 2026
- S2Form 10-Q for Q2 FY2026 · SEC EDGAR · Tier 1: company or exchange filing · Aug 5, 2026
- S3Form 10-Q for Q1 FY2026 · SEC EDGAR · Tier 1: company or exchange filing · Apr 29, 2026
- S4Form 10-K for FY2025 · SEC EDGAR · Tier 1: company or exchange filing · Feb 20, 2026
- S5Form 10-Q for Q3 FY2025 · SEC EDGAR · Tier 1: company or exchange filing · Nov 5, 2025
- S6Form 10-Q for Q2 FY2025 · SEC EDGAR · Tier 1: company or exchange filing · Jul 30, 2025
- S7Form 10-Q for Q1 FY2025 · SEC EDGAR · Tier 1: company or exchange filing · Apr 30, 2025
- S8Form 10-K for FY2024 · SEC EDGAR · Tier 1: company or exchange filing · Feb 24, 2025
- S9Form 10-Q for Q3 FY2024 · SEC EDGAR · Tier 1: company or exchange filing · Oct 30, 2024
- S10Form 10-Q for Q2 FY2024 · SEC EDGAR · Tier 1: company or exchange filing · Jul 31, 2024
- S11Form 10-Q for Q1 FY2024 · SEC EDGAR · Tier 1: company or exchange filing · May 1, 2024
- S12Form 10-K for FY2023 · SEC EDGAR · Tier 1: company or exchange filing · Feb 21, 2024
- S13Form 10-K for FY2022 · SEC EDGAR · Tier 1: company or exchange filing · Feb 16, 2023
- S14Form 10-K for FY2021 · SEC EDGAR · Tier 1: company or exchange filing · Feb 18, 2022
- S152026 proxy statement (DEF 14A) · SEC EDGAR · Tier 1: company or exchange filing · Apr 10, 2026
- S16Earnings release for Q3 FY2026 (8-K Exhibit 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Nov 4, 2026
- S17Investor supplement for Q3 FY2026 (8-K Exhibit 99.2) · SEC EDGAR · Tier 1: company or exchange filing · Nov 4, 2026
- S18Earnings release for Q4 FY2025 (8-K Exhibit 99.1) · SEC EDGAR · Tier 1: company or exchange filing · Feb 4, 2026
- S19Investor supplement for Q4 FY2025 (8-K Exhibit 99.2) · SEC EDGAR · Tier 1: company or exchange filing · Feb 4, 2026
Changes to this page (v1 · Nov 20, 2026)
- v1 · Nov 20, 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.