Financials · NASDAQ: SOFI
SoFi: how the business works
SoFi runs a bank through a phone app: it makes personal, student and home loans and holds members' deposits, with $3.6 billion of total net revenue in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow SoFi
Email me when SoFi's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
SoFi Technologies, Inc. · San Francisco, California · Founded 2011
Updated for Q3 FY2026 · checked
- Total net revenue, FY2025
- $3.6B
- Net income, FY2025
- $481.3M
- Members, Sep 30, 2026
- 17.1M
- Deposits, Sep 30, 2026
- $51.3B
- Founded
- 2011
The short version
SoFi in 5 points
1 · What it sells
SoFi makes personal, student and home loans, holds checking and savings deposits at SoFi Bank, offers investing and credit cards in one app and sells banking software through Galileo and Technisys, with $3,613.4 million of total net revenue in FY2025.
2 · Who pays it
Of the three segments' FY2025 revenue, borrowers and loan buyers in Lending paid 48.1%, members and partners in Financial Services 40.1% and software clients in the Technology Platform 11.7%.
3 · What it keeps from $100
Of every $100 that came in during FY2025, SoFi paid $24.2 in interest to depositors and lenders and kept $10.1 as net income; as an operating comparison, income before tax rose to $525.9 million from $233.3 million in FY2024, whose net income included a $258.4 million tax benefit.
4 · Where the operating profit comes from
In FY2025 the Lending segment earned $1.0 billion of contribution profit, Financial Services $793 million and the Technology Platform $144 million, before corporate costs SoFi does not assign to segments.
5 · The one thing to watch
Personal loans had net charge-offs of 2.26% of average balances in Q3 FY2026, and SoFi estimates about 3.4% when delinquent loans it sold before charge-off are counted.
Sources: From SoFi's FY2025 10-K and Q3 2026 earnings release · checked
See the full receipt and the management scorecard below
01Where $100 of a bank's money goes · FY2025
Where does $100 of SoFi's money go?
SoFi · FY2025
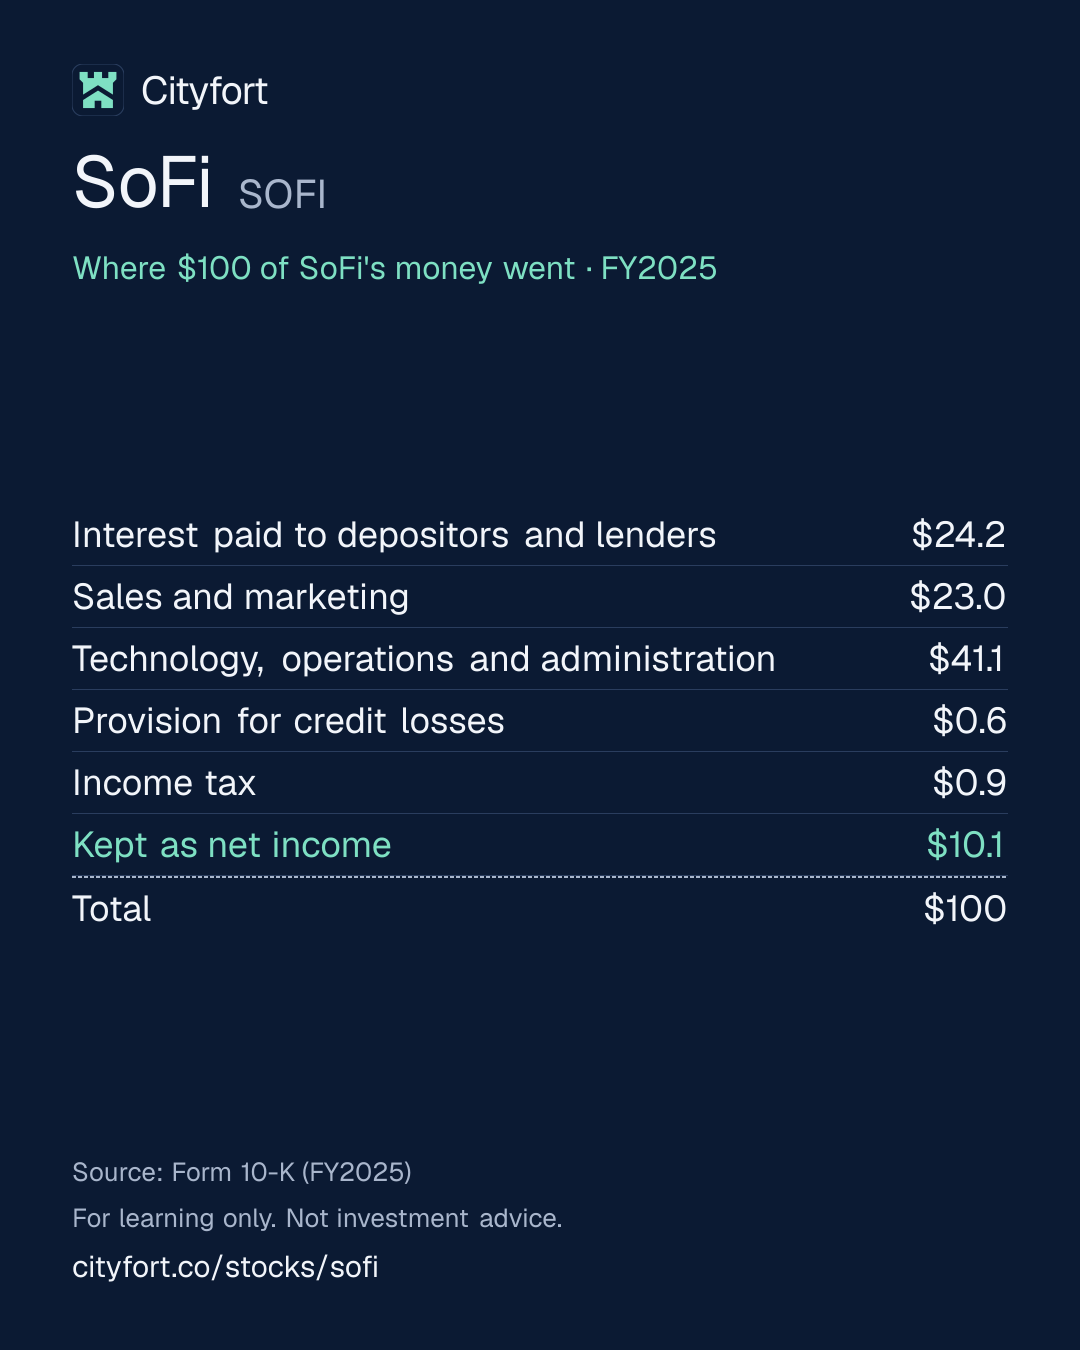
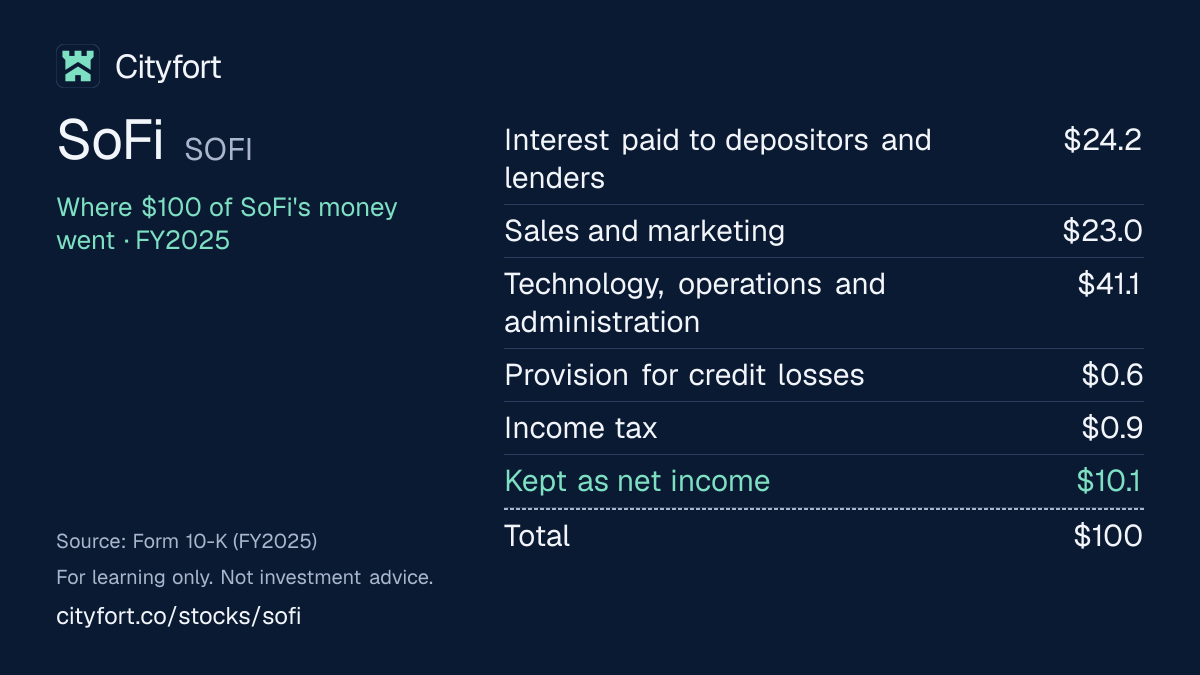
Receipt for every $100
| Interest paid to depositors and lenders | $24.2 |
|---|---|
| Sales and marketing | $23.0 |
| Technology, operations and administration | $41.1 |
| Provision for credit losses | $0.6 |
| Income tax | $0.9 |
| Kept as net income | $10.1 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Of every $100 that came in (interest income $3,375.2 million plus noninterest income $1,394.4 million = $4,769.6 million): each line = line ÷ $4,769.6 million × 100. SoFi reports costs by function, not total pay, so staff costs sit inside the cost lines.
Save this receipt as an image:
1080 × 1350 PNG for Instagram, LinkedIn1200 × 675 PNG for X
Embed this receipt
Paste this code into a blog or website to show the receipt, with a link back to this page:
Each week: one company explained in 5 points, picked by earnings date.
Free, no tips, unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does SoFi do?
Borrowers pay SoFi interest and fees on personal, student and home loans funded mostly by members' deposits; the money goes on interest to depositors and lenders, marketing, technology and staff, and what is left is profit.
- In FY2025 the Lending segment brought in 48.1% of the three segments' revenue, Financial Services 40.1% and the Technology Platform 11.7%.
- Interest paid to depositors and lenders took $24.2 of every $100 that came in during FY2025, and $10.1 was kept as net income.
03Who pays it
Who pays SoFi?
Borrowers and loan buyers (Lending)
48%
of revenue
Interest on personal, student and home loans, plus gains and fair-value changes when loans are valued or sold.
Members and partners (Financial Services)
40%
of revenue
The spread on members' deposits, credit card interest, card interchange, brokerage, and Loan Platform Business fees from partner lenders.
Companies using its software (Technology Platform)
12%
of revenue
Banks, fintechs and other companies paying Galileo and Technisys fees, mostly on multi-year contracts.
- Borrowers and loan buyers (Lending)48%
- Members and partners (Financial Services)40%
- Companies using its software (Technology Platform)12%
How spread out the customers are
Shares are of the three segments' FY2025 revenue, before $227.8 million of Corporate/Other and eliminations (Cityfort calculation from the FY2025 10-K). The 10-K says Galileo and Technisys revenue is highly concentrated in a few clients; a large client left before Dec 31, 2025, and Technology Platform revenue fell from $122.4 million in Q4 FY2025 to $75.1 million in Q1 FY2026.
04Why it makes money
Why does SoFi make money?
Deposits fund the loans, and selling more products to the same members spreads the cost of winning them
SoFi calls this its "Financial Services Productivity Loop". The 10-K says deposits at SoFi Bank cost less than warehouse funding, and that doing more business with existing members lowers acquisition cost. Noninterest expense per $100 of revenue fell from $148.1 in FY2021 to $84.6 in FY2025.
Noninterest expense per $100 of total net revenue (Cityfort calculation from the 10-Ks)
$148.1$84.6
FY2021 to FY2025
- A member joins, often for a loan
- The app offers more products
- Deposits fund new loans
- Marketing and tech costs spread over more products
- Savings fund rates and rewards
- More members join
↺ Step 6 feeds back into step 1.
05Business segments · FY2025
Which businesses make up SoFi?
Lending
48%Personal, student and home loans; profit shown is the segment's contribution profit.
Revenue $1.8B · Operating profit $1.0B
Financial Services
40%Checking and savings, investing, credit cards and the Loan Platform Business.
Revenue $1.5B · Operating profit $793M
Technology Platform
12%Galileo and Technisys software for other companies; revenue includes fees from SoFi's own units.
Revenue $450M · Operating profit $144M
How the mix changed
- Lending
- Financial Services
- Technology Platform
Revenue by segment, FY2021 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has SoFi done?
Net interest income
$2.2BFY2025
Net interest income rose from $252.2 million in FY2021 to $2,219.0 million in FY2025, while deposits rose from $7.3 billion at the end of FY2022 to $37.5 billion at the end of FY2025.
US$ · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net income
$481MFY2025
SoFi reported net losses to common stockholders in each year from FY2021 to FY2023 and net income of $479.1 million in FY2024, which included a $258.4 million tax benefit, and $481.3 million in FY2025.
US$ · after the provision for credit losses and tax
See the yearly numbers
See the quarterly numbers
Net interest margin
5.85%FY2025
The net interest margin was 3.95% in FY2021, between 5.40% and 5.88% in each year from FY2022 to FY2025, and 6.14% in Q3 FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
2.07%FY2025
Net charge-offs were 2.07% of average loans in FY2025, down from 2.66% in FY2023; most of SoFi's loans are carried at fair value, so their losses run through noninterest income rather than the provision.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the yearly numbers
See the quarterly numbers
See all yearly numbers
Diluted EPS for common stockholders. FY2024 diluted EPS ($0.39) uses $434.8 million of net income, after removing a gain on convertible notes, as the 10-K's diluted calculation does.
Not applicable: SoFi became a bank holding company in February 2022, so FY2021 has no deposits and no regulatory capital ratio.
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (December 31).
- FY2021 comes before SoFi became a bank holding company in February 2022: it had no deposits or CET1 ratio and funded its loans mainly with warehouse financing and its own capital.
- Loans are total loans as SoFi reports them in each 10-K's loans note (held for sale, held for investment at fair value and at amortized cost, net of the allowance): $38,037.1 million at the end of FY2025. For FY2021 this is the single Loans line on the balance sheet ($6,068.9 million).
- About 96% of those loans were carried at fair value at the end of FY2025 (Cityfort calculation from the FY2025 10-K). The allowance for credit losses ($50.9 million) covers only the $1,549.5 million of loans at amortized cost, such as credit cards; SoFi reports it as 3.29% of those loans.
- The FY2024 and FY2025 net charge-off ratios leave out delinquent personal loans SoFi sold before charging them off ($197.4 million and $209.2 million of unpaid balance), which it wrote down in noninterest income. FY2021 and FY2022 averages use month-end balances, later years daily balances.
- The efficiency ratio, return on assets and return on equity are Cityfort calculations from the 10-Ks, because SoFi reports none of them: efficiency = noninterest expense ÷ total net revenue; ROA = net income ÷ average total assets; ROE = net income to common stockholders ÷ average common equity. Noninterest expense was above total net revenue in FY2021 (148.1%), FY2022 (116.8%) and FY2023 (111.6%), so the efficiency ratio is blank for those years.
- Return on tangible common equity (ROTCE) is SoFi's own non-GAAP measure, based on its adjusted net income; its figures in the Q3 2026 earnings presentation start in FY2022.
- CET1 is for the holding company, SoFi Technologies; the company marks the Dec 31, 2025 and quarter-end figures as estimated. SoFi Bank's own CET1 ratio was 16.4% at the end of FY2025. The required minimum, including the conservation buffer, is 7.0%.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100
Sources (14)
- Form 10-K, fiscal year 2023 (year ended Dec 31, 2023)
- Form 10-K, fiscal year 2022 (year ended Dec 31, 2022)
- Form 10-K, fiscal year 2021 (year ended Dec 31, 2021)
- Form 10-K, fiscal year 2024 (year ended Dec 31, 2024)
- Q3 2026 earnings presentation
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
- Q4 2024 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2024
- Q1 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Mar 31, 2025
- Q2 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Jun 30, 2025
- Q3 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2025
- Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025
- Q1 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Mar 31, 2026
- Q2 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Jun 30, 2026
- Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026
07Who runs it
Who runs SoFi, and did they deliver?
Anthony Noto
Chief Executive Officer and director · since 2018
CEO of Social Finance from February 2018 and of SoFi Technologies since the May 2021 merger; previously Twitter's chief financial officer and chief operating officer. Total 2025 pay in the proxy's summary table: $30.3 million.
Christopher Lapointe
Chief Financial Officer · since 2020
CFO of Social Finance from September 2020 and of SoFi Technologies since May 2021; previously at Uber.
Arun Pinto
Chief Risk Officer · since 2024
Joined in February 2024 from Wells Fargo.
Eric Schuppenhauer
Group business unit leader, Borrow; interim or acting President of SoFi Bank · since 2024
Joined in August 2024 from Citizens Financial Group; in charge of SoFi Bank since April 2025.
What they said, and what happened
2 delivered · 2 too early to tell
Said on Jan 27, 2025
FY2025 GAAP net income of $285 million to $305 million and GAAP diluted EPS of $0.25 to $0.27.
DeliveredWhat happened
Net income was $481.3 million and diluted EPS $0.39 in FY2025.
Said on Jan 27, 2025
Add at least 2.8 million new members in FY2025.
DeliveredWhat happened
Members rose by 3,523,679 in FY2025, to 13,651,002.
Said on Jan 30, 2026
Grow members by at least 30% in FY2026.
Too early to tellWhat happened
Members were 17,074,272 at Sep 30, 2026, 25.1% above the 13,651,002 at Dec 31, 2025.
Said on Oct 27, 2026
Reach 100 million products by 2030.
Too early to tellWhat happened
SoFi counted 26,671,579 products at Sep 30, 2026, under a definition it changed three times in 2026.
Sources (5)
- 2026 proxy statement (DEF 14A), record date Apr 20, 2026
- Q4 2024 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2024
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
- Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025
- Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026
08What could go wrong
What could go wrong for SoFi?
- Other
Personal-loan losses
Personal loans were $32.1 billion of SoFi's fair-value loans at Sep 30, 2026. Their net charge-offs were 2.26% of average balances in Q3 FY2026, or about 3.4% by SoFi's own estimate counting delinquent loans it sold.
Watch Personal-loan charge-off rate in each earnings release.
- Other
Fair-value assumptions
About 96% of loans are valued at fair value using SoFi's own inputs, such as a 5.10% annual default rate and a 5.56% discount rate for personal loans at Sep 30, 2026. Changes in those inputs move noninterest income.
Watch Default and discount-rate inputs in each 10-Q.
- Pricing
Interest rates and deposit costs
Interest-bearing deposits averaged $48.6 billion at a 3.07% rate in Q3 FY2026. The CEO said on Oct 27, 2026 that the original 2026 guidance assumed two rate cuts, and instead there had been one rate hike.
Watch Net interest margin each quarter (6.14% in Q3 FY2026).
- Concentration
Few loan buyers and platform partners
The 10-K says SoFi sells loans to a concentrated number of whole-loan buyers and originates Loan Platform Business loans for a concentrated number of partners; those fees were $575.9 million in FY2025.
Watch Loan platform fees and loan sale volumes each quarter.
- Concentration
Software client concentration
A large client left the Technology Platform before Dec 31, 2025; segment revenue fell from $114.6 million in Q3 FY2025 to $87.4 million in Q3 FY2026.
Watch Technology Platform revenue and accounts each quarter.
- Regulation
Bank and stablecoin rules
SoFi is supervised by the Federal Reserve and SoFi Bank by the OCC. For its SoFiUSD stablecoin, SoFi says it intends to apply to the OCC under the GENIUS Act, which takes effect Jan 18, 2027.
Watch OCC decisions and new risk factors in each 10-Q.
- Other
More shares
Shares outstanding rose from 1,095.4 million at the end of FY2024 to 1,297.8 million at Oct 30, 2026, mostly from $3.2 billion of stock sold in 2025; stock-based compensationPay given as shares instead of cash, which spreads ownership more thinly. Learn more was $262.1 million in FY2025.
Watch Share count on each 10-Q cover.
Sources (5)
- Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
- Third quarter 2026 earnings call transcript
- Q3 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2025
- Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026)
09Both sides
What do supporters and critics point to?
What supporters point to
- Total net revenue rose every year, from $984.9 million in FY2021 to $3,613.4 million in FY2025.
- Members grew from 3.5 million at the end of FY2021 to 17.1 million at Sep 30, 2026.
- Income before tax rose from $233.3 million in FY2024 to $525.9 million in FY2025.
- Loans were 104.7% of deposits at Sep 30, 2026, down from 188.8% at the end of FY2022 (Cityfort calculations from the reported totals).
- The CET1 capital ratio was 16.9% at Sep 30, 2026 (company estimate), against a required minimum of 7.0% including the buffer.
What critics point to
- FY2024 net income of $498.7 million included a $258.4 million tax benefit from releasing a valuation allowance.
- Shares outstanding rose from 1,095.4 million at the end of FY2024 to 1,297.8 million at Oct 30, 2026.
- Sales and marketing cost $1,095.4 million in FY2025, 30.3% of total net revenue.
- Technology Platform revenue fell from $114.6 million in Q3 FY2025 to $87.4 million in Q3 FY2026 after a large client left.
- The FY2025 provision for credit losses was $30.3 million while net charge-offs were $670.9 million, because most loans are carried at fair value and their losses run through noninterest income.
10What to watch next
What should you watch next at SoFi?
Next event
Q4 FY2026 results
Date not announced yet.
Personal-loan charge-offs
2.26% of average balances in Q3 FY2026; SoFi estimates about 3.4% counting delinquent loans it sold before charge-off.
Margin and deposit costs
Net interest margin was 6.14% in Q3 FY2026; the CEO said on Oct 27, 2026 that 2026 brought one rate hike instead of the two cuts the original guidance assumed.
FY2026 results against guidance
SoFi guided on Oct 27, 2026 to about $5.04 billion of adjusted net revenue for FY2026; GAAP total net revenue was $3,704.1 million in the first nine months.
SoFiUSD and the GENIUS Act
The law takes effect Jan 18, 2027; SoFi says it intends to submit an OCC application and waiver request.
11Key facts
Key facts about SoFi
- What does SoFi do?
- SoFi Technologies is a US bank holding company that offers personal, student and home loans, checking and savings accounts, credit cards and investing through one app, and sells banking software to other companies through Galileo and Technisys. SoFi had 17.1 million members at Sep 30, 2026.
- How does SoFi make money?
- SoFi makes money from the gap between the interest it earns on loans and the interest it pays on deposits and borrowings, plus fees. In FY2025 SoFi earned $2,219.0 million of net interest income and $1,394.4 million of noninterest income, including $575.9 million of loan platform fees for loans it arranged for other lenders, for total net revenue of $3,613.4 million.
- Is SoFi profitable?
- Yes. SoFi Technologies reported net income of $481.3 million in FY2025 and $498.7 million in FY2024, after net losses from FY2021 to FY2023. FY2024 included a $258.4 million tax benefit; income before tax was $525.9 million in FY2025 against $233.3 million in FY2024. SoFi's net income was $241.0 million in Q3 FY2026.
- What is SoFi's revenue by segment?
- In FY2025 SoFi's Lending segment had $1,848.9 million of net revenue, Financial Services $1,542.0 million and the Technology Platform $450.2 million; Corporate/Other and eliminations took off $227.8 million, for total net revenue of $3,613.4 million.
- How much does SoFi lend?
- SoFi originated $16.9 billion of loans in Q3 FY2026: $12.6 billion of personal loans (including $3.6 billion for third parties), $2.9 billion of student loans and $1.4 billion of home loans.
- How big are SoFi's deposits?
- SoFi held $51.3 billion of deposits at Sep 30, 2026, up from $37.5 billion at Dec 31, 2025. SoFi's Financial Services segment, which includes the checking and savings accounts, had $1,542.0 million of net revenue in FY2025.
- What is SoFi's Technology Platform?
- SoFi's Technology Platform segment, made up of Galileo and Technisys, sells payment-processing and core banking software to banks, fintechs and other companies. It had $450.2 million of net revenue in FY2025 and 140.4 million accounts on the platform at Sep 30, 2026.
- Is SoFi a bank?
- Yes. SoFi Technologies became a bank holding company in February 2022 when it bought Golden Pacific Bancorp; its subsidiary SoFi Bank, N.A. is a national bank. SoFi Technologies had a CET1 capital ratio of 16.9% at Sep 30, 2026, a company estimate.
- Who owns SoFi?
- SoFi Technologies has one class of common stock with one vote per share. As of the 2026 proxy's Apr 20, 2026 record date, SoFi's 16 directors and executive officers held 2.5% of the shares, and The Vanguard Group (6.4%), Vanguard Capital Management (5.3%) and BlackRock (5.1%) were listed as holders of more than 5%.
Terms on this page
- CET1 ratio
- Earnings per share (EPS)
- Efficiency ratio
- Market cap
- Net charge-offs
- Net interest income and margin
- P/E ratio
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
12What it sells
12What it sells
What does SoFi sell?
Personal loans
Fixed-rate loans of generally $5,000 to $100,000 over 2 to 7 years, for things like paying off credit cards or home projects.
Student loans
Refinancing of existing student loans and loans to students while they are in school.
Home loans
Mortgages for buying or refinancing a home, and home equity loans.
SoFi Money (checking and savings)
Accounts held at SoFi Bank that pay interest; SoFi held $51.3 billion of deposits at Sep 30, 2026.
SoFi Invest and SoFi Crypto
Trading in stocks, ETFs and options, managed portfolios, and, since Q4 2025, digital assets held through SoFi Bank.
SoFi Credit Card
Cash-back credit cards that earn interest and card fees.
Loan Platform Business
SoFi finds and approves borrowers for other lenders and earns a fee per loan: $575.9 million of fees in FY2025.
Technology Platform (Galileo and Technisys)
Payment-processing and core banking software that banks, fintechs and other companies pay to use.
Think of it like this
Like a bank, a lender and a brokerage combined in one phone app.
What it does
- Does: Makes personal, student and home loans
- Does: Holds checking and savings deposits at SoFi Bank
- Does: Sells many of its loans to other investors, or originates them for partners for a fee
- Does: Sells payment and banking software to other companies
What it does not do
- Does not: Pay a dividend on its common stock
- Does not: Earn most of its money from fees: net interest income was 61.4% of FY2025 total net revenue
- Does not: Hold most of its loans at cost under a loan-loss allowance: about 96% are carried at fair value
13How the money flows
13How the money flows · FY2025
How does money flow through SoFi?
Money in
- Interest income on loans and securities$3.4B
- Noninterest income (loan gains, fees and other)$1.4B
The company
SoFi
$4.8B came in
Money out
- Interest paid to depositors and lenders$1.2B
- Sales and marketing$1.1B
- Technology, operations and administration$2.0B
- Provision for credit losses$30.3M
- Income tax$44.5M
- Net income$481M
- Members deposit money at SoFi Bank, and SoFi also borrows from warehouse lines and securitization investors.
- It lends the money as personal, student and home loans, earning $3,375.2 million of interest income in FY2025.
- It earned $1,394.4 million more of noninterest income, from loan gains and fair-value changes, partner and card fees, and software fees.
- It paid $1,156.2 million of interest to depositors and lenders, and $3,057.2 million for marketing, technology, operations and administration.
- After a $30.3 million provision for credit losses and $44.5 million of income tax, $481.3 million was net income.
14What it needs to run
14What it needs to run
What does SoFi need to run?
Deposits
Members' deposits fund most loans: $51.3 billion at Sep 30, 2026. The 10-K says deposits generally cost less than warehouse and securitization funding.
Bank charter
SoFi Bank, N.A. is a national bank supervised by the OCC; the holding company is supervised by the Federal Reserve.
Borrowed funding
Warehouse lines, a revolving credit line, convertible notes and securitizations: $3,862.9 million of debt at Sep 30, 2026.
People
About 6,100 employees at Dec 31, 2025, 82% of them in the US.
15Where growth could come from
15Where growth could come from
Where could SoFi's growth come from?
SoFi said in its Q3 2026 earnings release (Oct 27, 2026) that it expects FY2026 adjusted net revenue of about $5.04 billion, adjusted EBITDAOperating profit before wear-and-tear charges (depreciation and amortization). As a margin: per $100 of sales. of about $1.66 billion and adjusted net income of about $840 million, and FY2027 adjusted net revenue of about $6.4 billion. These are the company's own non-GAAPThe company's own "adjusted" numbers, not the official (GAAP) ones. Always read them next to the official figure. Learn more measures.
More members
Working17.1M at Sep 30, 2026
Up from 12.6 million a year earlier, as SoFi reports.
Status: Working, on track against what the company said.
Loans made for partners
Working$575.9M fees in FY2025
The Loan Platform Business earned $151.2 million of loan platform fees in Q3 FY2026.
Status: Working, on track against what the company said.
Deposits funding loans
Working$51.3B deposits, Sep 30, 2026
Up from $32.9 billion a year earlier; loans were 104.7% of deposits (Cityfort calculation from the Q3 2026 earnings release).
Status: Working, on track against what the company said.
Technology Platform
Mixed$87.4M revenue, Q3 FY2026
Down from $114.6 million a year earlier after a large client left; SoFi said revenue grew 18% excluding that client.
Status: Mixed, partly on track.
Crypto and the SoFiUSD stablecoin
Early$1.6M net crypto revenue, Q3 FY2026
SoFi Crypto launched in Q4 2025 and SoFiUSD in Q3 2026; SoFi says it intends to apply to the OCC under the GENIUS Act, effective Jan 18, 2027.
Status: Early, too early to judge.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
16The company's own measures (non-GAAP)
16The company's own measures · FY2025 and Q3 FY2026
What do SoFi's own measures show?
Official (GAAP): Total net revenue, FY2025
$3.6B
Company's own measure: Adjusted net revenue, FY2025
$3.6B
Leaves out fair-value changes in servicing rights and residual interests that come from changes in valuation inputs.
Official (GAAP): Net income, FY2025
$481M
Company's own measure: Adjusted EBITDA, FY2025
$1.1B
Net income before interest on corporate borrowings, income tax, depreciation and amortization, stock-based compensation ($262.1 million in FY2025), restructuring, impairment and transaction costs, and the same fair-value items.
Official (GAAP): Return on average common equity, FY2025 (Cityfort calculation from the FY2025 10-K)
6.3%
Company's own measure: Return on tangible common equity, FY2025
8.0%
SoFi's own measure: its adjusted net income divided by average common equity without goodwill and intangible assets. SoFi reports no GAAP return on equity.
Official (GAAP): Net income, Q3 FY2026
$241M
Company's own measure: Adjusted net income, Q3 FY2026
$243M
Adds back $2.7 million of restructuring and $0.1 million of transaction costs, less $0.7 million of tax.
Official (GAAP)
No official figure measures this; it is the company's own operating measure.
Company's own measure: Members, Sep 30, 2026
17.1 million
A member is someone who has selected a SoFi product; members are removed only for cause, as SoFi defines it. The count was 13.7 million at Dec 31, 2025.
Official (GAAP)
No official figure measures this; it is the company's own operating measure.
Company's own measure: Total products, Sep 30, 2026
26.7 million
Counts every product selected since a member joined, active or not. SoFi changed what counts as a product in Q1, Q2 and Q3 FY2026 without recasting earlier periods.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out · Stock-based compensation and dilution: pay that becomes shares
17Financial strength: capital, loan losses, deposits
17Financial strength · FY2025
How strong is SoFi's balance sheet?
- Loans made$38.0B
- Deposits taken$37.5B
- of which pay no interest$118M
Loans were 101.4% of deposits at the end of FY2025 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 0.3% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 22.8%
- common equity capital as a share of risk-weighted assets; regulators set a minimum
- Allowance for credit losses
- $50.9M
- money set aside for expected loan losses
- Net charge-offs
- $671M
- loans written off, minus recoveries: 2.07% of average loans
- Efficiency ratio
- 84.6%
- $ of noninterest expense per $100 of revenue (net interest income + noninterest income)
- Return on assets
- 1.15%
- net income as % of average total assets
- Return on equity
- 6.3%
- net income as % of average common equity
- Return on tangible common equity
- 8.0%
- the company's own measure (non-GAAP): equity without goodwill and other intangibles
Figures at the end of FY2025, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
18Who owns it
18Who owns it · ownership as of Apr 20, 2026
Who owns SoFi?
- Officers and directors (as a group), shares
- 2.5%
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Insider trades · Form 4 data as of Nov 6, 2026
What did SoFi's insiders report trading?
SoFi's insiders made 94 Form 4A filing an insider must make within two business days of buying or selling the company's shares. Learn more filings in the 12 months to Nov 6, 2026.
They reported 7 purchases (140,211 shares) and 19 sales (571,239 shares) in the open market or privately (codes P and S).
17 of the 19 sales were on forms with the Rule 10b5-1 plan box checked.
The same filings report 121 other share transactions (M: 78, F: 37, G: 4, A: 2).
They also report 109 transactions in options, stock units or other derivatives.
Insiders are a company's officers, directors and owners of more than 10% of a class of its shares. Most changes in their holdings must be reported to the SEC on a Form 4 within two business days. Source: SEC Form 4 filings on EDGAR.
- P
- a purchase in the open market or privately
- S
- a sale in the open market or privately
- A
- a grant, award or other acquisition from the company under Rule 16b-3
- F
- shares withheld or handed over to pay an exercise price or tax when an award is received, exercised or vests
- M
- exercise or conversion of an option or other derivative, exempt under Rule 16b-3
- G
- a bona fide gift
Code meanings: General Instruction 8 of Form 4 (SEC).
The latest 25 of 147 transactions
Shares: A = acquired, D = disposed of. A price the filing gives only in a footnote shows as “See filing”. The 10b5-1 box is checked when at least one trade on the form was made under a Rule 10b5-1 plan. A Form 4/A replaces the form it amends. See all of SoFi's Form 4 filings on EDGAR.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes · Rule 10b5-1 trading plans: how insiders pre-schedule their trades
19What it does with profit
19What it does with profit
What does SoFi do with its profit?
Money raised · Jul 31, 2025
Sold 82,733,817 new shares at $20.85 each (priced Jul 29, 2025), including the underwriters' option, for net proceeds of $1.7 billion.
$1.7B
Money raised · Dec 8, 2025
Sold 54,545,454 new shares at $27.50 each (priced Dec 4, 2025) for net proceeds of $1.5 billion; with the underwriters' option, completed Jan 5, 2026, the offering reached 57,754,660 shares.
$1.5B
Sources (4)
- Form 8-K, Ex. 99.2: pricing of $1.5 billion common stock offering at $20.85 a share, filed Jul 30, 2025
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
- Form 8-K, Ex. 99.2: pricing of $1.5 billion common stock offering at $27.50 a share, filed Dec 5, 2025
- Form 8-K (Item 8.01), underwriters' option exercised; 57,754,660 shares sold in the December 2025 offering, filed Jan 5, 2026
20Governance signals
20Governance signals
What do SoFi's governance filings show?
- Auditor
- Deloitte & Touche LLP, since 2017
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy's related-person section lists pay arrangements, indemnification agreements and two relatives on staff: the CEO's daughter and a director's son each earned more than $120,000 in 2025, which the proxy says matches comparable employees.
- Credit rating
- No public credit rating found in a search of rating agency sites on Nov 6, 2026
Flags to know about
shares as collateral
CEO and CFO forward contracts
CEO Anthony Noto entered a prepaid variable forward contract on 1,500,000 shares on Aug 28, 2025 (maturing about Aug 28, 2028; $24.1 million paid up front) and put the shares up as collateral. CFO Christopher Lapointe did the same on 500,000 shares on Nov 12, 2025 (maturing about Nov 12, 2027; $11.8 million up front). SoFi's policy allows using its shares as collateral only with written approval from its Compliance Officer and Board.
disclosure
Product count definition changed
SoFi changed what counts as a product in Q1, Q2 and Q3 FY2026 without recasting earlier periods, and the count includes products no longer in use.
disclosure
Bank ratios not reported
SoFi reports no return on assets, return on equity, efficiency ratio or total employee pay; the ratios on this page are Cityfort calculations from its 10-Ks.
other
General Counsel retired
General Counsel Stephen Simcock retired effective Dec 31, 2025.
Sources (7)
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
- 2026 proxy statement (DEF 14A), record date Apr 20, 2026
- Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026)
- Form 8-K (Item 7.01), CEO prepaid variable forward contract on 1,500,000 shares, filed Aug 29, 2025
- Form 8-K (Item 7.01), CFO prepaid variable forward contract on 500,000 shares, filed Nov 13, 2025
- Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026
- Form 8-K (Item 5.02), General Counsel retirement effective Dec 31, 2025, filed Dec 4, 2025
21What the market paid
21What the market paid · price as of Nov 5, 2026
What did the market pay for SoFi on Nov 5, 2026?
Price as of Nov 5, 2026 (shown for education; prices change daily).
Price as of Nov 5, 2026: SoFi closed at $16.04 on Nasdaq. Times 1,297.8 million shares (Oct 30, 2026) that is a market value of about $20.8 billion (Cityfort calculation from the Nov 5, 2026 Nasdaq closing price and the Q3 FY2026 10-Q cover). P/E is price ÷ earnings per share: 29.2 on diluted EPS of $0.55 for the 12 months to Sep 30, 2026 (Cityfort calculation from the Q4 FY2025 to Q3 FY2026 earnings releases). P/B is price ÷ book value per share: 1.84 on the $8.71 book value per share at Sep 30, 2026 stated in the Q3 2026 earnings release.
- Share price
- $16.04
- Market value (market cap)
- $20.8B
- P/E
- 29.2×
- P/B
- 1.8×
More price-based ratios · as of Nov 5, 2026
Each ratio divides a number from the company's filings by the market value or share price on Nov 5, 2026. Prices change daily, so these ratios do too.
Price to sales (P/S)
4.4×
$20.8B market value ÷ $4.7B revenue (four quarters to Sep 30, 2026) = 4.4×
Cityfort calculation from the Nov 5, 2026 closing price and the Q4 FY2025 to Q3 FY2026 earnings releases. Source: SOFI historical daily prices, Nasdaq (close of Nov 5, 2026: $16.04); Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026); Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025 and 3 more
How price ratios work
Shares used for the market value: 1,297.8 million ($16.04 × 1,297.8 million shares ≈ $20.8B). Source: Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026); Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
Source: SOFI historical daily prices, Nasdaq (close of Nov 5, 2026: $16.04); Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026); Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025 and 3 more
Sources (7)
- SOFI historical daily prices, Nasdaq (close of Nov 5, 2026: $16.04)
- Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026)
- Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025
- Q1 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Mar 31, 2026
- Q2 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Jun 30, 2026
- Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026
- Form 10-K, fiscal year 2025 (year ended Dec 31, 2025)
22How it got here
22How it got here
How did SoFi get here?
2011
Milestone
Founded for student loans
Social Finance starts by refinancing private student loans.
2020
Business-model change
Buys Galileo
Adds payment-processing software that other companies pay to use.
2021
Milestone
Lists through a SPAC merger
Merges with Social Capital Hedosophia Holdings Corp. V on May 28, 2021; shares start trading on Nasdaq on Jun 1, 2021.
2022
Business-model change
Becomes a bank
Buys Golden Pacific Bancorp in February 2022 and starts SoFi Bank; also buys Technisys.
2023
Crisis
Goodwill write-down
Records a $247.2 million goodwill impairment in the Technology Platform; net loss of $300.7 million for the year.
2024
Milestone
First yearly profit in the five years shown
Net income of $498.7 million, including a $258.4 million tax benefit from releasing a valuation allowance.
2025
Milestone
$3.2 billion of new shares
Sells stock twice; launches SoFi Crypto in Q4; a large Technology Platform client leaves.
2026
Business-model change
Stablecoin and two acquisitions
Launches the SoFiUSD stablecoin in Q3 and buys Peach Finance and Composer Securities for about $70.1 million.
23Sources and changes
Where every number on this page comes from
Sources (24 documents)
- S1Form 10-K, fiscal year 2025 (year ended Dec 31, 2025) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Feb 17, 2026
- S2Form 10-K, fiscal year 2024 (year ended Dec 31, 2024) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Feb 24, 2025
- S3Form 10-K, fiscal year 2023 (year ended Dec 31, 2023) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Feb 27, 2024
- S4Form 10-K, fiscal year 2022 (year ended Dec 31, 2022) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Mar 1, 2023
- S5Form 10-K, fiscal year 2021 (year ended Dec 31, 2021) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Mar 1, 2022
- S6Form 10-Q, third quarter fiscal 2026 (quarter ended Sep 30, 2026) · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Nov 5, 2026
- S7Q3 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2026 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Oct 27, 2026
- S8Q2 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Jun 30, 2026 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jul 29, 2026
- S9Q1 2026 earnings release (Form 8-K Ex. 99.1), quarter ended Mar 31, 2026 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Apr 29, 2026
- S10Q4 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jan 30, 2026
- S11Q3 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Sep 30, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Oct 28, 2025
- S12Q2 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Jun 30, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jul 29, 2025
- S13Q1 2025 earnings release (Form 8-K Ex. 99.1), quarter ended Mar 31, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Apr 29, 2025
- S14Q4 2024 earnings release (Form 8-K Ex. 99.1), quarter ended Dec 31, 2024 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jan 27, 2025
- S152026 proxy statement (DEF 14A), record date Apr 20, 2026 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Apr 30, 2026
- S16Q3 2026 earnings presentation · SoFi Technologies, Inc. (investor relations) · Tier 1: company or exchange filing · Oct 27, 2026
- S17Third quarter 2026 earnings call transcript · SoFi Technologies, Inc. (investor relations) · Tier 1: company or exchange filing · Oct 27, 2026
- S22SOFI historical daily prices, Nasdaq (close of Nov 5, 2026: $16.04) · Nasdaq, Inc. · Tier 1: company or exchange filing · Nov 5, 2026
- S23Form 8-K (Item 7.01), CEO prepaid variable forward contract on 1,500,000 shares, filed Aug 29, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Aug 29, 2025
- S24Form 8-K (Item 7.01), CFO prepaid variable forward contract on 500,000 shares, filed Nov 13, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Nov 13, 2025
- S25Form 8-K, Ex. 99.2: pricing of $1.5 billion common stock offering at $20.85 a share, filed Jul 30, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jul 30, 2025
- S26Form 8-K, Ex. 99.2: pricing of $1.5 billion common stock offering at $27.50 a share, filed Dec 5, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Dec 5, 2025
- S27Form 8-K (Item 8.01), underwriters' option exercised; 57,754,660 shares sold in the December 2025 offering, filed Jan 5, 2026 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Jan 5, 2026
- S28Form 8-K (Item 5.02), General Counsel retirement effective Dec 31, 2025, filed Dec 4, 2025 · SoFi Technologies, Inc. (SEC EDGAR) · Tier 1: company or exchange filing · Dec 4, 2025
Changes to this page (v1 · Nov 6, 2026)
- v1 · Nov 6, 2026First version, through Q3 FY2026 (quarter ended Sep 30, 2026). (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.