Financials · NYSE: PGR
Progressive: how the business works
Progressive insures cars, trucks, motorcycles, boats and homes, and earned $81.7 billion of insurance premiums in FY2025.
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow Progressive
Email me when Progressive's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
The Progressive Corporation · Mayfield Village, Ohio
Updated for Q3 FY2026 · checked
- Revenue, FY2025
- $87.7B
- Net income, FY2025
- $11.3B
- Policies in force, Sep 30, 2026
- 40.5 million
- Combined ratio, FY2025
- 87.4
- Employees, Dec 31, 2025
- About 70,000
The short version
Progressive in 5 points
1 · What it sells
Progressive insures cars, trucks, motorcycles, boats and homes, earning $81.7 billion of insurance premiums in FY2025, with 40.5 million policies in force at Sep 30, 2026.
2 · Who pays it
Of Progressive's $87.7 billion of FY2025 revenue, Personal Lines customers paid 81%, businesses buying Commercial Lines cover 12%, its investments earned 5% and fees and services brought 2%.
3 · What it keeps from $100
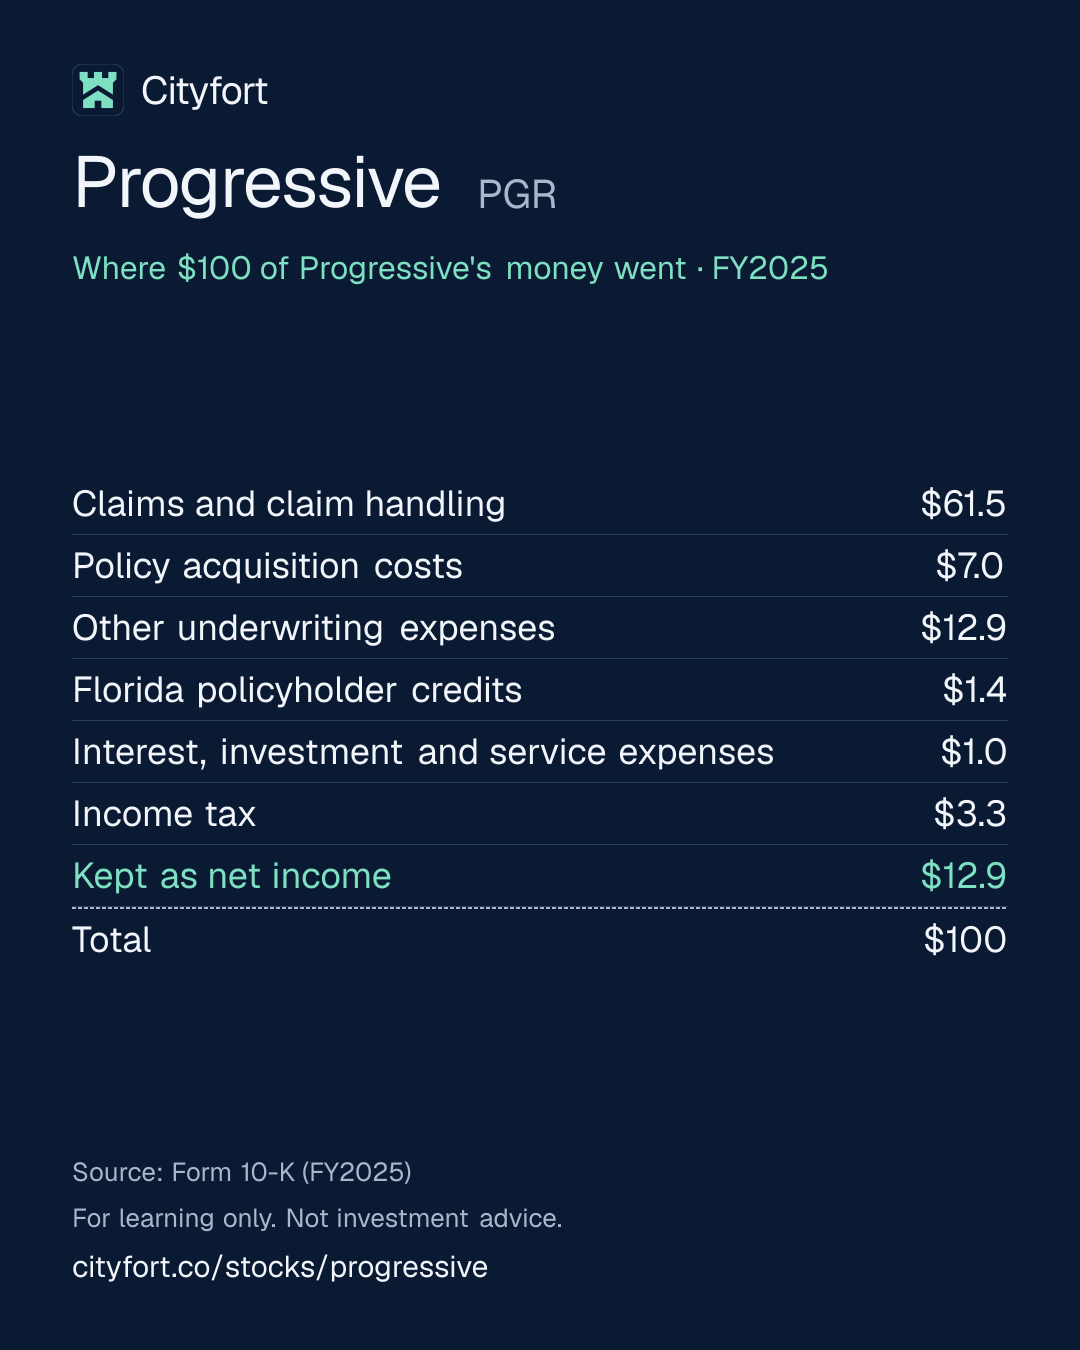
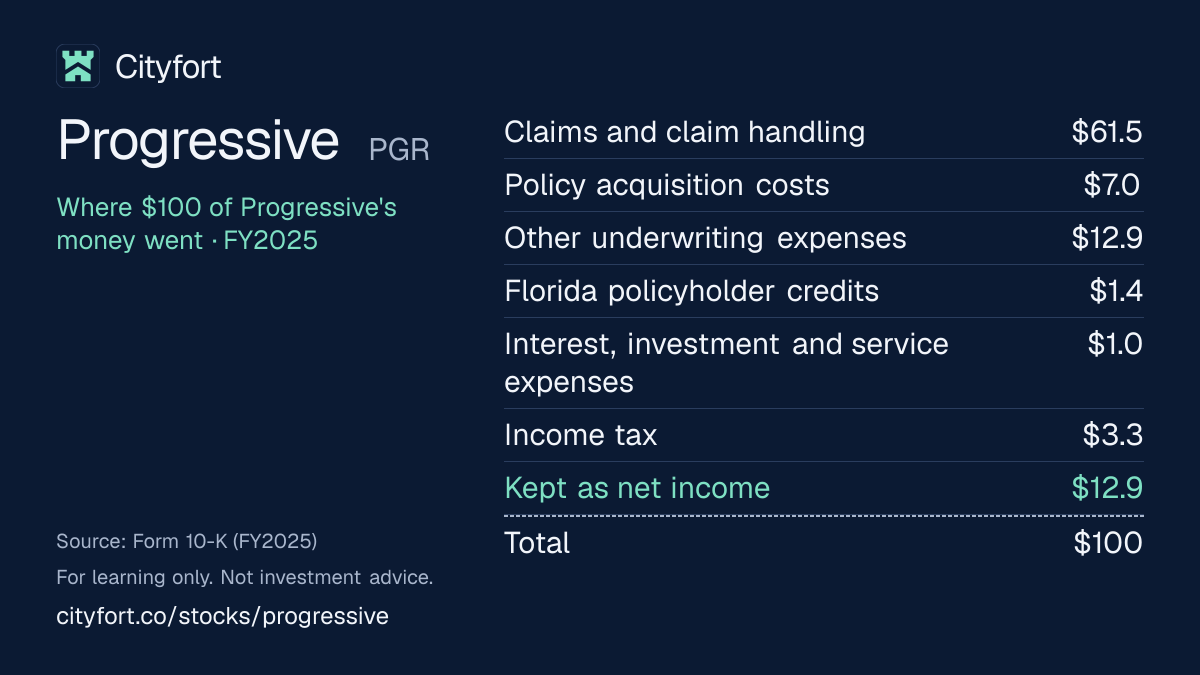
Of every $100 that came in during FY2025, Progressive paid $61.5 in claims and claim handling and kept $12.9 as net income, which included $727 million of gains on securities; pretax underwriting profit from insurance operations was $10.2 billion.
4 · Where the operating profit comes from
Personal Lines made 86.4% of FY2025 pretax underwriting profit ($8.9 billion) and Commercial Lines 13.8% ($1.4 billion), while investment income added $3.6 billion outside underwriting.
5 · The one thing to watch
Progressive's loss and loss adjustment expense ratio was 68.1 in Q3 FY2026, against 64.4 in Q3 FY2025, while premiums written grew 4%.
Sources: From Progressive's FY2025 annual report, Q3 FY2026 10-Q and Q3 2026 letter to shareholders · checked
See the full receipt and the management scorecard below
Sources (4)
01Where $100 of an insurer's money goes · FY2025
Where does $100 of Progressive's money go?
Progressive · FY2025
Receipt for every $100
| Claims and claim handling | $61.5 |
|---|---|
| Policy acquisition costs | $7.0 |
| Other underwriting expenses | $12.9 |
| Florida policyholder credits | $1.4 |
| Interest, investment and service expenses | $1.0 |
| Income tax | $3.3 |
| Kept as net income | $12.9 |
| Total | $100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly $100 because of rounding.
How this is worked out
Cityfort calculation from the FY2025 10-K. Of every $100 that came in (total revenues of $87,671 million): each line = line ÷ $87,671 million × 100. Revenue includes $727 million of net gains on securities, which change from year to year. Interest, investment and service expenses = $278 million + $34 million + $528 million.
Save this receipt as an image:
1080 × 1350 PNG for Instagram, LinkedIn1200 × 675 PNG for X
Embed this receipt
Paste this code into a blog or website to show the receipt, with a link back to this page:
Each week: one company explained in 5 points, picked by earnings date.
Free, no tips, unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does Progressive do?
Drivers, homeowners and businesses pay Progressive premiums to cover accidents and damage; most of the money goes on claims, and what's left, plus income from investing premiums until claims are paid, is profit.
- Of the $87.7 billion that came in during FY2025, 93.1% was insurance premiums earned: $70.8 billion from Personal Lines and $10.9 billion from Commercial Lines.
- Claims and the cost of handling them took $61.5 of every $100 that came in, and $12.9 was kept as net income.
03Who pays it
Who pays Progressive?
Drivers and homeowners (Personal Lines)
81%
of revenue
Premiums earned on personal auto, special lines and property policies ($70.8 billion)
Businesses (Commercial Lines)
12%
of revenue
Premiums earned on commercial auto and other business policies ($10.9 billion)
Its investment portfolio
5%
of revenue
Investment income ($3.6 billion) and net gains on securities ($727 million) from investing premiums held until claims are paid
Policyholders paying fees, and service customers
2%
of revenue
Fees and other revenues ($1.2 billion) and service revenues ($504 million)
- Drivers and homeowners (Personal Lines)81%
- Businesses (Commercial Lines)12%
- Its investment portfolio5%
- Policyholders paying fees, and service customers2%
How spread out the customers are
Shares are of FY2025 total revenue of $87.7 billion (Cityfort calculation from the FY2025 10-K). Progressive does not give any customer's share of revenue. Policies for Uber's U.S. subsidiaries were 14% of Commercial Lines premiums written in FY2025, about 1.8% of companywide premiums written (Cityfort calculation from the FY2025 10-K: 13% × 14%).
04Why it makes money
Why does Progressive make money?
Progressive earns an underwriting profit when claims and costs stay below premiums, and investment income on money held until claims are paid
Pretax underwriting profit was $10.2 billion in FY2025, or 12.6 cents per dollar of premiums earned, and investment income added $3.6 billion. Progressive's stated goal is a combined ratioAn insurer's claims plus underwriting costs, per $100 of premiums earned. Under 100% means premiums covered both. of 96 or better each year, which means at least 4 cents of underwriting profit per premium dollar.
Underwriting profit margin
4.7%12.6%
FY2021 to FY2025
- Customers pay premiums at the start of each policy
- Progressive prices policies to keep part of each premium as underwriting profit
- It invests the premiums until claims are paid
- Investment income adds to underwriting profit
- Profit and capital let it write more policies
↺ Step 5 feeds back into step 1.
05Business segments · FY2025
Which businesses make up Progressive?
Personal Lines
87%Insurance for individuals' cars, motorcycles, boats, RVs and homes; net premiums earned shown, with $8.9 billion of pretax underwriting profit, 86.4% of the segments' total (Cityfort calculation from the FY2025 10-K).
Revenue $70.8B · Operating profit $8.9B
Commercial Lines
13%Auto and other insurance for businesses; net premiums earned shown, with $1.4 billion of pretax underwriting profit, 13.8% of the total (other run-off business lost $21 million).
Revenue $10.9B · Operating profit $1.4B
How the mix changed
- Personal Lines
- Commercial Lines
Revenue by segment, FY2022 to FY2025.
US$
See the numbers
06The numbers · Consolidated · US$
How has Progressive done?
Premiums earned
$81.7BFY2025
Net premiums earned rose every year, from $44.4 billion in FY2021 to $81.7 billion in FY2025.
US$ · net premiums earned: the part of premiums that covers the period, after reinsurance
See the yearly numbers
See the quarterly numbers
Combined ratio
87.4%FY2025
The combined ratio, claims and underwriting costs per $100 of premiums earned, was 94.9 in FY2023 and 87.4 in FY2025; below 100 means an underwriting profit.
Progressive nets fees and other revenues against claim handling or underwriting expenses in its ratios and its underwriting profit, and its FY2025 expense ratio includes $1,224 million of Florida policyholder credits.
% of premiums earned · claims plus underwriting costs per $100 of premiums, as reported; under 100% means premiums covered both
See the yearly numbers
See the quarterly numbers
Net income
$11.3BFY2025
Net income to common shareholders fell to $694.6 million in FY2022, when holding-period losses on securities were $2.1 billion, and rose to $11.3 billion in FY2025, with $10.2 billion of pretax underwriting profit.
US$ · after claims, costs, investment results and tax; the table shows where it came from
See the numbers
Catastrophe losses
$1.5BFY2025
Catastrophe losses ranged from $1.3 billion in FY2021 to $2.5 billion in FY2024, and were $1.5 billion in FY2025.
US$ · claims from storms, wildfires and other events the company counts as catastrophes, as reported
See the numbers
See all yearly numbers
Loss ratio = losses and loss adjustment expenses ÷ net premiums earned. Expense ratio = underwriting costs ÷ net premiums earned. Combined ratio = loss ratio + expense ratio, as the company reports them. Net investment income is interest and dividends on the money the company holds before paying claims; realized and unrealized gains are shown apart because they move with markets. Net income is the amount for common stockholders. Fiscal years are the company's own (December 31 (fiscal year = calendar year)).
- Loss, expense and combined ratios are Progressive's GAAP ratios as reported in its annual reports; the loss ratio includes the cost of handling claims (loss adjustment expenses).
- Realized gains are gains on securities sold minus impairments; unrealized gains are net holding-period gains on stocks and other securities carried at fair value, which pass through net income. Price changes on bonds go to other comprehensive income instead.
- Investment income is shown before investment expenses ($34 million in FY2025), as on the income statement. Fees and other include service revenues ($504 million in FY2025).
- Policies in force are at each year end, Personal and Commercial Lines combined (Cityfort calculation from the FY2025 annual report's ten-year summary).
- Claim reserves of $46,786 million plus unearned premiums of $27,873 million = $74,659 million at Sep 30, 2026 (Cityfort calculation from the Q3 FY2026 10-Q). Short-term investments and U.S. Treasuries were $43.7 billion, just under 45% of the portfolio, the company states.
- The debt is senior notes with no rating triggers or financial covenants; notes of $1,000 million fall due in January and March 2027, and a $300 million line of credit was undrawn at Dec 31, 2025.
Download Progressive's yearly and quarterly numbers (CSV, with source ids)
Learn: What is the combined ratio? Claims plus costs, with real US insurers · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What is return on equity? Profit on equity, with real US companies
Sources (12)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- 2024 Annual Report to Shareholders (Exhibit 13 to the FY2024 Form 10-K)
- Earnings release: December 2024 and Q4 2024 results (8-K Exhibit 99)
- Earnings release: March 2025 and Q1 2025 results (8-K Exhibit 99)
- Earnings release: June 2025 and Q2 2025 results (8-K Exhibit 99)
- Earnings release: September 2025 and Q3 2025 results (8-K Exhibit 99)
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
- Earnings release: December 2025 and Q4 2025 results (8-K Exhibit 99.1)
- Earnings release: March 2026 and Q1 2026 results (8-K Exhibit 99)
- Earnings release: June 2026 and Q2 2026 results (8-K Exhibit 99)
- Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99)
07Who runs it
Who runs Progressive, and did they deliver?
Tricia Griffith
Chief Executive Officer
Her 2025 total pay in the Summary Compensation Table was $17,705,924; the median employee's was $86,906, a ratio of 204 to 1.
Andrew Quigg
Chief Financial Officer · since 2026
CFO from Jul 4, 2026, succeeding John Sauerland, who retired on Jul 3, 2026.
Pat Callahan
Personal Lines President
The company said in a Jun 17, 2026 8-K that he will retire in January 2027.
Lori Niederst
Chief Personal Lines Officer · since 2026
In this role from Jul 4, 2026.
What they said, and what happened
2 delivered · 2 too early to tell
Said on Oct 15, 2025
Progressive said it recorded $950 million of expense in September 2025 for credits to Florida personal auto policyholders under the state's excess-profit law.
DeliveredWhat happened
The FY2025 total was $1,224 million, credited to Florida personal auto policyholders with policies on Dec 31, 2025; $1.2 billion was paid in Q1 2026.
Said on Jan 28, 2026
Progressive said CFO John Sauerland would retire on Jul 3, 2026 and Andrew Quigg would succeed him.
DeliveredWhat happened
Quigg became CFO on Jul 4, 2026.
Said on Mar 2, 2026
Progressive repeated in its FY2025 10-K its goal to grow as fast as it can at a combined ratio of 96 or better each calendar year.
Too early to tellWhat happened
The underwriting margin was 12.5% in the first nine months of FY2026, a combined ratio of 87.5, and premiums written grew 5%.
Said on Nov 2, 2026
Progressive said it had launched its new commercial auto pricing model 8.4 in 2 states and planned to add 5 more in Q4 FY2026.
Too early to tellWhat happened
The 7 states are 15% of trailing 12-month core commercial auto premiums written, the company said.
Sources (10)
- 2026 proxy statement (DEF 14A)
- Form 8-K filed Jan 28, 2026 (Items 2.02, 5.02: CFO John Sauerland to retire Jul 3, 2026; Andrew Quigg to succeed)
- Form 8-K filed May 12, 2026 (Items 5.02, 5.07, 7.01: CFO election, 2026 annual meeting votes, 25M-share repurchase authorization)
- Form 8-K filed Jun 17, 2026 (Item 5.02: Personal Lines President Pat Callahan to retire Jan 2027; CFO pay)
- Earnings release: September 2025 and Q3 2025 results (8-K Exhibit 99)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99)
- Letter to Shareholders, Third Quarter 2026 (Exhibit 99 to the Q3 2026 Form 10-Q)
08What could go wrong
What could go wrong for Progressive?
- Pricing
Rising claim costs
The loss and loss adjustment expense ratio, claims per $100 of premiums earned, rose to 68.1 in Q3 FY2026 from 64.4 in Q3 FY2025, which the company tied to higher claim severity. Q3 FY2026 net income fell 3%.
Watch The loss and loss adjustment expense ratio in each monthly and quarterly release.
- Competition
Price competition
The CEO wrote that Q3 FY2026 was extremely competitive and described a soft market; premiums written grew 4%, partly reflecting rate cuts, and the company said market growth turned slightly negative.
Watch Premiums written growth and new business applications each quarter.
- Other
Storms and catastrophes
Catastrophe losses were $1,794 million in FY2023, $2,514 million in FY2024 and $1,478 million in FY2025. Property reinsurance covers large events above set retentions, but most vehicle business is not reinsured.
Watch Catastrophe losses in each quarter ($388 million in Q3 FY2026).
- Regulation
State insurance regulation
States regulate insurance rates, and Florida's excess-profit law led to $1,224 million of policyholder credits for FY2025.
Watch State rate approvals and any further Florida credits in the 10-K and 10-Qs.
- Other
Investment losses
The $99.2 billion portfolio is mostly bonds. In FY2022 net losses on securities were $1.9 billion, and in the first nine months of FY2026 unrealized bond losses cut comprehensive income by $2.8 billion.
Watch Gains and losses on securities, and the portfolio's 3.6-year duration, in each release.
- Legal
Class action lawsuits
Class actions allege improper valuation of total-loss vehicle claims by Progressive, with classes certified in three states, and other suits challenge claim and rating practices. The company says losses are reasonably possible but not estimable.
Watch Rulings and any new legal accruals in the 10-K and 10-Qs.
Sources (6)
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
- Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99)
- Letter to Shareholders, Third Quarter 2026 (Exhibit 99 to the Q3 2026 Form 10-Q)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
09Both sides
What do supporters and critics point to?
What supporters point to
- The combined ratio was below Progressive's goal of 96 in each year from FY2021 to FY2025, reaching 87.4 in FY2025.
- Policies in force rose 6% in the year to Sep 30, 2026, to 40.5 million.
- Return on average common equity was 35.3% in FY2025, as the company reports it.
- Book value per share rose from $30.35 at the end of FY2021 to $59.51 at Sep 30, 2026.
- Debt was 19.6% of total capital at Sep 30, 2026, below the company's 30% policy limit.
What critics point to
- The loss and loss adjustment expense ratio rose to 68.1 in Q3 FY2026 from 64.4 a year earlier, and Q3 net income fell 3%.
- The CEO described Q3 FY2026 as a soft market, with rate cuts to compete.
- About 83.5% of FY2025 premiums written came from personal vehicle policies (Cityfort calculation from the FY2025 10-K).
- Net income swung with investment results, falling to $721.5 million in FY2022 after $1.9 billion of losses on securities.
- Class actions over total-loss vehicle valuations have certified classes in Colorado, North Carolina and Ohio.
10What to watch next
What should you watch next at Progressive?
Next event
Q4 FY2026 results
Date not announced yet.
Monthly results
Progressive reports results every month; it said October 2026 results come out on Nov 18, 2026.
Claim costs
The loss and loss adjustment expense ratio was 68.1 in Q3 FY2026, against 64.4 in Q3 FY2025.
Personal Lines leadership
Personal Lines President Pat Callahan retires in January 2027, the company said in a Jun 17, 2026 8-K.
11Key dates
What are the key dates for Progressive?
| Event | Date | Source |
|---|---|---|
| October 2026 monthly results releaseAs announced in the Q3 2026 earnings release. | Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99) | |
| Personal Lines President Pat Callahan retiresJanuary 2027, as the Jun 17, 2026 8-K states. | Not yet stated | Form 8-K filed Jun 17, 2026 (Item 5.02: Personal Lines President Pat Callahan to retire Jan 2027; CFO pay) |
Learn: What is an 8-K? A company's news report, with a real Adobe filing
12Key facts
Key facts about Progressive
- What does Progressive do?
- Progressive (The Progressive Corporation) sells insurance for cars, motorcycles, boats, RVs and homes to individuals, and auto insurance to businesses. It had 40.5 million policies in force at Sep 30, 2026.
- How does Progressive make money?
- Progressive makes most of its money from insurance premiums: net premiums earned were $81.7 billion, or 93.1%, of its $87.7 billion of FY2025 revenue (Cityfort calculation from the FY2025 10-K). Investment income added $3.6 billion and investment gains $727 million.
- What is the Progressive business model?
- Progressive collects premiums before it pays claims, aims to keep part of each premium as underwriting profit, and invests the money it holds until claims are paid. In FY2025 its combined ratio was 87.4, meaning claims and expenses were $87.40 per $100 of premiums earned, and its investment portfolio was $97.4 billion at Dec 31, 2025.
- Is Progressive profitable?
- Progressive reported net income of $11.3 billion in FY2025, up from $8.5 billion in FY2024, on revenue of $87.7 billion; diluted earnings per share were $19.23. Net income in the first nine months of FY2026 was $8.7 billion.
- What is Progressive's revenue by segment?
- In FY2025 Progressive's Personal Lines segment earned $70.8 billion of net premiums and $8.9 billion of pretax underwriting profit, and Commercial Lines earned $10.9 billion of net premiums and $1.4 billion of pretax underwriting profit.
- How many car insurance policies does Progressive have?
- Progressive had 28.2 million personal auto policies in force at Sep 30, 2026: 16.8 million sold directly to customers and 11.3 million sold through independent agents, up 8% and 7% from a year earlier.
- Does Progressive sell home and motorcycle insurance?
- Yes. At Sep 30, 2026 Progressive had 7.4 million special lines policies (motorcycles, boats, RVs and similar vehicles) and 3.7 million property policies in force. Property was 4% of Personal Lines net premiums written in FY2025.
- Does Progressive insure businesses?
- Progressive's Commercial Lines segment, mainly auto insurance for businesses, earned $10.9 billion of net premiums in FY2025 and had 1.25 million policies in force at Sep 30, 2026. The FY2025 10-K says Progressive has been the largest U.S. commercial auto insurer since 2015.
- How does Progressive sell its policies?
- In FY2025, 57% of Progressive's personal vehicle premiums written came from policies sold directly to customers, and 43% through independent agents. More than 40,000 independent agencies sold its policies at Dec 31, 2025.
- Who owns Progressive?
- Progressive has one class of common shares, with 579.4 million outstanding on Oct 1, 2026. Vanguard Capital Management reported 7.53% at Mar 31, 2026 and BlackRock 7.2% at Jun 30, 2025; directors and executive officers as a group held less than 1% at Jan 31, 2026, according to the 2026 proxy statementThe yearly filing about shareholder votes, the board and executive pay. Learn more.
Sources (6)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
- Schedule 13G, Vanguard Capital Management (44,078,585 shares, 7.53%, as of Mar 31, 2026)
- 2026 proxy statement (DEF 14A)
Terms on this page
- Capital expenditures (capex)
- Combined ratio
- Earnings per share (EPS)
- Market cap
- Net margin
- P/E ratio
- Revenue vs net income
- Stock buyback
Each explains the term in plain English, with the same number from other companies on Cityfort.
Go deeper
More detail from the same filings. Open any section.
13What it sells
13What it sells
What does Progressive sell?
Personal auto insurance
Car insurance for individuals, sold directly to customers or through independent agents. Personal auto was 95% of personal vehicle premiums written in FY2025.
Special lines
Insurance for motorcycles, boats, RVs and similar vehicles; 7.4 million policies in force at Sep 30, 2026.
Property
Homeowners and other property insurance, mostly sold through agents (72% of property premiums written in FY2025); 3.7 million policies at Sep 30, 2026.
Commercial Lines
Auto insurance for businesses, mostly sold through agents, plus business owners policies and coverage for Uber's U.S. subsidiaries in 14 states.
What it does
- Does: Sells car, motorcycle, boat, RV and home insurance to individuals
- Does: Sells auto and other insurance to businesses
- Does: Invests the premiums it holds until claims are paid
- Does: Sells both directly and through independent agents
What it does not do
- Does not: Earn most of its revenue from investing: premiums earned were 93.1% of FY2025 revenue
- Does not: Reinsure most of its car insurance: personal vehicle business is generally not reinsured outside state-run programs
- Does not: Pay only a fixed dividend: it adds an annual-variable dividend whose size changes each year
14How the money flows
14How the money flows · FY2025
How does money flow through Progressive?
Money in
- Insurance premiums earned$81.7B
- Investment income$3.6B
- Fees, other and service revenues$1.7B
- Net gains on securities$727M
The company
Progressive
$87.7B came in
Money out
- Claims and claim handling (losses and loss adjustment expenses)$54.0B
- Policy acquisition costs$6.1B
- Other underwriting expenses$11.3B
- Florida policyholder credits$1.2B
- Interest, investment and service expenses$840M
- Income tax$2.9B
- Net income$11.3B
- Customers pay premiums for policies, and Progressive counts them as revenue over the policy term.
- It holds the money until claims come in, and invests it, mostly in bonds.
- Claims and the cost of settling them take the largest share.
- Selling and running the policies, the Florida credits, interest and tax take more.
- What is left is net income: $11.3 billion in FY2025.
15What it needs to run
15What it needs to run
What does Progressive need to run?
Capital held by its insurance companies
Statutory surplus, the capital its insurance companies hold under state insurance rules, was $28.4 billion at Dec 31, 2025; premiums written were 2.9 times that surplus.
Independent agents
More than 40,000 independent agencies sold its policies at Dec 31, 2025, including nearly 6,000 in its Platinum program.
Employees
About 70,000 employees at Dec 31, 2025, up from 49,077 at the end of 2021.
Reinsurance for homes
It buys reinsurance for large storm losses on property: under new contracts signed in Q2 2026, it keeps the first $300 million of a storm outside Florida and $75 million of a storm in Florida, and the program covers about $1.9 billion of losses.
16Where growth could come from
16Where growth could come from
Where could Progressive's growth come from?
CEO Tricia Griffith wrote in the Q3 2026 letter to shareholders (Nov 2, 2026) that Progressive's goal is to "grow as fast as we can and make at least four cents of underwriting profit". She also wrote that premiums written grew 4% in the quarter, a more moderate pace, in part reflecting its rate reductions as it competes in a soft market.
Personal auto policies
Working26.2M → 28.2M, Sep 2025 to Sep 2026
Direct auto policies in force rose 8% to 16.8 million and agency auto policies 7% to 11.3 million in the year to Sep 30, 2026.
Status: Working, on track against what the company said.
New personal auto pricing model
Working21 states, 55% of policies
The company said its personal auto model 9.0 was in 21 states at Sep 30, 2026, covering 55% of personal auto policies in force and 53% of trailing 12-month personal auto premiums written.
Status: Working, on track against what the company said.
Homeowners bundled with auto
Early3.65M property policies, flat
Property policies were 3.65 million at both Sep 30, 2025 and Sep 30, 2026, while new homeowners applications rose 22% in Q3 FY2026, the company said. It estimates the bundled auto and home market at about $230 billion of premiums.
Status: Early, too early to judge.
Commercial Lines
MixedPremiums earned −2%, 9M FY2026
Commercial Lines premiums earned fell 2% in the first nine months of FY2026, while premiums written rose 5%. Its combined ratio was 92.6 in Q3 FY2026, against 89.2 a year earlier.
Status: Mixed, partly on track.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
17The company's own measures (non-GAAP)
17The company's own measures · FY2025 and Q3 FY2026
What do Progressive's own measures show?
Official (GAAP): Income before income taxes, FY2025
$14.2B
Company's own measure: Pretax underwriting profit, FY2025
$10.2B
Premiums earned plus fees, minus claims, claim handling and underwriting expenses, as reported in the segment note. It leaves out investment income, gains on securities and interest expense.
Official (GAAP)
No official figure measures this; it is the company's own operating measure.
Company's own measure: Combined ratio, FY2025
87.4%
Claims and underwriting expenses per $100 of premiums earned, equal to 100 minus the underwriting margin (12.6%). Below 100 means an underwriting profit; Progressive's goal is 96 or better.
Official (GAAP)
No official figure measures this; it is the company's own operating measure.
Company's own measure: Combined ratio, Q3 FY2026
88.7%
Same measure for the quarter; it was 89.5 in Q3 FY2025, when the Florida policyholder credits added 4.6 points.
Official (GAAP): Net premiums earned, FY2025
$81.7B
Company's own measure: Net premiums written, FY2025
$83.2B
Premiums on policies sold or renewed in the year. They become revenue (premiums earned) over each policy's term, so written premiums are not revenue.
Official (GAAP)
No official figure measures this; it is the company's own operating measure.
Company's own measure: Policies in force, Sep 30, 2026
40.5 million
Policies active on that date across Personal Lines (39.2 million) and Commercial Lines (1.25 million), up 6% from 38.1 million a year earlier.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
18Financial strength: investments, debt, capital
18Financial strength · Sep 30, 2026
How strong is Progressive's balance sheet?
What the premiums are invested in
- Bonds (fixed maturities)$92.2B
93.0% of the investments listed
- Short-term investments$2.1B
2.1% of the investments listed
- Common stocks$4.6B
4.7% of the investments listed
- Preferred stocks$193M
0.2% of the investments listed
Shares of the portfolio: Cityfort calculation from the Q3 FY2026 10-Q, each type ÷ the total listed.
- Book value per share
- $51.74
- shareholders' equity per share at the end of FY2025, as reported
- Return on equity
- 35.3%
- net income as % of average shareholders' equity, as reported
- Investments
- $99.2B
- money held in bonds, stocks and cash until claims are paid
- Debt
- $8.4B
- borrowings on the balance sheet
- Shareholders' equity
- $34.5B
- what the company owns minus what it owes
- Debt to capital
- 19.6%
- debt ÷ (debt + equity), as reported by the company
- Policies in force
- 38.6 million
- at the end of FY2025, as reported
Progressive estimated its insurance subsidiaries' statutory surplus at $35.6 billion at Sep 30, 2026, and its financial policy is to keep debt below 30% of total capital.
Figures at Sep 30, 2026, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
19Who owns it
19Who owns it · ownership as of Mar 13, 2026
Who owns Progressive?
Share classes
Holders of 5% or more
From the company's proxy statement (DEF 14A), later Schedule 13G filings and the share counts on its latest annual or quarterly report. Each holder row shows the date of its own filing.
Insider trades · Form 4 data as of Nov 6, 2026
What did Progressive's insiders report trading?
Progressive's insiders made 165 Form 4A filing an insider must make within two business days of buying or selling the company's shares. Learn more filings in the 12 months to Nov 6, 2026.
They reported no purchases and 27 sales (146,093.684 shares) in the open market or privately (codes P and S).
23 of the 27 sales were on forms with the Rule 10b5-1 plan box checked.
The same filings report 78 other share transactions (F: 28, A: 25, M: 14, D: 6, G: 5).
They also report 128 transactions in options, stock units or other derivatives.
Insiders are a company's officers, directors and owners of more than 10% of a class of its shares. Most changes in their holdings must be reported to the SEC on a Form 4 within two business days. Source: SEC Form 4 filings on EDGAR.
- P
- a purchase in the open market or privately
- S
- a sale in the open market or privately
- A
- a grant, award or other acquisition from the company under Rule 16b-3
- D
- shares handed back to the company under Rule 16b-3
- F
- shares withheld or handed over to pay an exercise price or tax when an award is received, exercised or vests
- M
- exercise or conversion of an option or other derivative, exempt under Rule 16b-3
- G
- a bona fide gift
Code meanings: General Instruction 8 of Form 4 (SEC).
The latest 25 of 105 transactions
Shares: A = acquired, D = disposed of. A price the filing gives only in a footnote shows as “See filing”. The 10b5-1 box is checked when at least one trade on the form was made under a Rule 10b5-1 plan. A Form 4/A replaces the form it amends. See all of Progressive's Form 4 filings on EDGAR.
Learn: How to read a proxy statement (DEF 14A): Nvidia's 2026 proxy · Form 4 insider filings: who files, the codes and the footnotes · Rule 10b5-1 trading plans: how insiders pre-schedule their trades
20What it does with profit
20What it does with profit
What does Progressive do with its profit?
Dividend per share
$13.90FY2025
Dividend paid for each share, by financial year.
$ per share
See the numbers
Buyback · Sep 30, 2026
Open-market share repurchases in the first nine months of FY2026, plus $73 million for shares withheld for taxes on awards; the company says it bought back 7.7 million shares for $1.6 billion in the period, counting both.
$1.5B
Buyback · Dec 31, 2025
FY2025 open-market share repurchases, from the cash flow statement.
$74M
Money raised · Mar 26, 2026
Issued $500 million of 4.60% senior notes due 2031 and $1 billion of 5.15% senior notes due 2036.
$1.5B
21Governance signals
21Governance signals
What do Progressive's governance filings show?
- Auditor
- PricewaterhouseCoopers LLP, since 1984
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- The 2026 proxy discloses that the brother-in-law of the Chief Information Officer works in Claims and was paid about $138,000 for 2025.
- Credit rating
- Moody's, S&P and Fitch (expected ratings on the March 2026 senior notes, in the company's Mar 23, 2026 term sheet); AM Best (May 1, 2026) A2 (Moody's) / A (S&P) / A (Fitch) on the senior notes; AM Best: financial strength A+ and issuer rating "aa" for the main insurance subsidiaries, issuer rating "a" for The Progressive Corporation (Stable (all)), May 1, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
other · Mar 2, 2026
Total-loss vehicle valuation lawsuits
Class actions in several states allege improper valuation of total-loss vehicle claims through a "negotiation adjustment"; classes have been certified in Colorado, North Carolina and Ohio. Progressive says losses are reasonably possible but neither probable nor reasonably estimable.
other · Mar 2, 2026
Florida excess-profit credits
Florida law caps personal auto profit over three-year periods. Progressive recorded $1,224 million of policyholder credits for FY2025 (accident years 2023 to 2025) and paid $1.2 billion in Q1 2026.
Sources (5)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- 2026 proxy statement (DEF 14A)
- Free writing prospectus: term sheet for the 2031 and 2036 senior notes (expected ratings)
- AM Best Affirms Credit Ratings of The Progressive Corporation and Its Subsidiaries
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
22What the market paid
22What the market paid · price as of Nov 5, 2026
What did the market pay for Progressive on Nov 5, 2026?
Price as of Nov 5, 2026 (shown for education; prices change daily).
Price as of Nov 5, 2026: Progressive shares closed at $233.18, from Nasdaq's historical price table for PGR; the shares are listed on the NYSE. Market value of about $135.1 billion (Cityfort calculation from the Nov 5, 2026 closing price and the Q3 FY2026 10-Q) = $233.18 × 579.36 million shares on Oct 1, 2026. P/E is price ÷ earnings per share: 11.7 on diluted EPS of $19.86 for the four quarters to Sep 30, 2026 (Cityfort calculation from the Q4 FY2025 to Q3 FY2026 earnings releases). P/B is price ÷ book value per share: 3.92 on $59.51 at Sep 30, 2026, as the company states it. Dividend yield is 5.96% on the $13.90 a share declared for FY2025, which includes the $13.50 annual-variable dividend that changes each year; on the $0.10 quarterly dividend alone ($0.40 a year) it is 0.17% (Cityfort calculation from the FY2025 10-K and the Nov 5, 2026 closing price).
- Share price
- $233.18
- Market value (market cap)
- $135.1B
- P/E
- 11.7×
- P/B
- 3.9×
More price-based ratios · as of Nov 5, 2026
Each ratio divides a number from the company's filings by the market value or share price on Nov 5, 2026. Prices change daily, so these ratios do too.
Price to sales (P/S)
1.5×
$135.1B market value ÷ $91.7B revenue (four quarters to Sep 30, 2026) = 1.5×
Cityfort calculation from the Nov 5, 2026 closing price and the Q4 FY2025 to Q3 FY2026 10-Ks and 10-Qs and earnings releases. Source: PGR historical prices, Oct 6 to Nov 5, 2026 (Nasdaq.com historical table; PGR is listed on the NYSE); Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026); Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99) and 5 more
How price ratios work
Shares used for the market value: 579.36 million ($233.18 × 579.36 million shares ≈ $135.1B). Source: Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
Source: PGR historical prices, Oct 6 to Nov 5, 2026 (Nasdaq.com historical table; PGR is listed on the NYSE); Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026); Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99) and 4 more
Sources (8)
- PGR historical prices, Oct 6 to Nov 5, 2026 (Nasdaq.com historical table; PGR is listed on the NYSE)
- Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026)
- Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99)
- Earnings release: December 2025 and Q4 2025 results (8-K Exhibit 99.1)
- Earnings release: March 2026 and Q1 2026 results (8-K Exhibit 99)
- Earnings release: June 2026 and Q2 2026 results (8-K Exhibit 99)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- SEC XBRL company facts, The Progressive Corporation (CIK 0000080661): nine-month 2024 revenue, pretax income and net income from the Q3 2024 Form 10-Q
23How it got here
23How it got here
How did Progressive get here?
2015
Milestone
Largest in commercial auto
Progressive says it has been the largest U.S. commercial auto insurer since 2015.
2021
Milestone
Protective Insurance bought
It bought Protective Insurance for $313.2 million net of cash acquired.
2022
Crisis
Investment losses
Net income fell to $721.5 million after $1.9 billion of losses on securities and a $224.8 million goodwill write-down in property.
2024
Milestone
Preferred shares redeemed
It redeemed its Series B preferred shares on Feb 22, 2024 for $508 million, including accrued dividends.
2024
Business-model change
Property joins Personal Lines
From the FY2024 10-K, property insurance is reported inside Personal Lines instead of as a separate segment.
2025
Milestone
Florida policyholder credits
It recorded $1,224 million of credits to Florida auto policyholders under the state's excess-profit law.
2025
Milestone
$13.50 variable dividend
It declared a $13.50 a share annual-variable dividend ($7.9 billion) in Dec 2025, paid in Jan 2026.
2026
Milestone
New CFO and notes
It issued $1.5 billion of senior notes in March, and Andrew Quigg became CFO on Jul 4, 2026.
Sources (7)
- Form 10-K, fiscal year 2025 (ended Dec 31, 2025)
- 2023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K)
- 2025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K)
- 2024 Annual Report to Shareholders (Exhibit 13 to the FY2024 Form 10-K)
- Earnings release: September 2025 and Q3 2025 results (8-K Exhibit 99)
- Form 8-K filed Mar 26, 2026 (Item 8.01: $500M 4.60% notes due 2031 and $1B 5.15% notes due 2036)
- Form 8-K filed May 12, 2026 (Items 5.02, 5.07, 7.01: CFO election, 2026 annual meeting votes, 25M-share repurchase authorization)
24Sources and changes
Where every number on this page comes from
Sources (26 documents)
- S1Form 10-K, fiscal year 2025 (ended Dec 31, 2025) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 2, 2026
- S22025 Annual Report to Shareholders (Exhibit 13 to the FY2025 Form 10-K) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 2, 2026
- S32024 Annual Report to Shareholders (Exhibit 13 to the FY2024 Form 10-K) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 3, 2025
- S42023 Annual Report to Shareholders (Exhibit 13 to the FY2023 Form 10-K) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Feb 26, 2024
- S5Form 10-Q, Q3 2026 (quarter ended Sep 30, 2026) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Nov 2, 2026
- S6Letter to Shareholders, Third Quarter 2026 (Exhibit 99 to the Q3 2026 Form 10-Q) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Nov 2, 2026
- S7Earnings release: December 2024 and Q4 2024 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jan 29, 2025
- S8Earnings release: March 2025 and Q1 2025 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Apr 16, 2025
- S9Earnings release: June 2025 and Q2 2025 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jul 16, 2025
- S10Earnings release: September 2025 and Q3 2025 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Oct 15, 2025
- S11Earnings release: December 2025 and Q4 2025 results (8-K Exhibit 99.1) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jan 28, 2026
- S12Earnings release: March 2026 and Q1 2026 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Apr 15, 2026
- S13Earnings release: June 2026 and Q2 2026 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jul 15, 2026
- S14Earnings release: September 2026 and Q3 2026 results (8-K Exhibit 99) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Oct 14, 2026
- S152026 proxy statement (DEF 14A) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 23, 2026
- S16Form 8-K filed Jan 28, 2026 (Items 2.02, 5.02: CFO John Sauerland to retire Jul 3, 2026; Andrew Quigg to succeed) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jan 28, 2026
- S17Form 8-K filed May 12, 2026 (Items 5.02, 5.07, 7.01: CFO election, 2026 annual meeting votes, 25M-share repurchase authorization) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · May 12, 2026
- S18Form 8-K filed Jun 17, 2026 (Item 5.02: Personal Lines President Pat Callahan to retire Jan 2027; CFO pay) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Jun 17, 2026
- S19Form 8-K filed Mar 26, 2026 (Item 8.01: $500M 4.60% notes due 2031 and $1B 5.15% notes due 2036) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 26, 2026
- S20Free writing prospectus: term sheet for the 2031 and 2036 senior notes (expected ratings) · The Progressive Corporation (SEC EDGAR) · Tier 1: company or exchange filing · Mar 23, 2026
- S21AM Best Affirms Credit Ratings of The Progressive Corporation and Its Subsidiaries · AM Best (via Business Wire) · Tier 2: rating agency or regulator · May 1, 2026
- S22Schedule 13G/A, The Vanguard Group (0 shares after its Jan 12, 2026 realignment; event date Mar 13, 2026) · The Vanguard Group (SEC EDGAR) · Tier 1: company or exchange filing · Mar 27, 2026
- S23Schedule 13G, Vanguard Capital Management (44,078,585 shares, 7.53%, as of Mar 31, 2026) · Vanguard Capital Management (SEC EDGAR) · Tier 1: company or exchange filing · Apr 30, 2026
- S24PGR historical prices, Oct 6 to Nov 5, 2026 (Nasdaq.com historical table; PGR is listed on the NYSE) · Nasdaq, Inc. · Tier 1: company or exchange filing · Nov 6, 2026
- S25SEC XBRL company facts, The Progressive Corporation (CIK 0000080661): nine-month 2024 revenue, pretax income and net income from the Q3 2024 Form 10-Q · U.S. Securities and Exchange Commission (data.sec.gov) · Tier 1: company or exchange filing · Nov 6, 2026
- S26Q2 2026 Investor Relations event slides (Robinsons consumer segment) · The Progressive Corporation (investors.progressive.com) · Tier 1: company or exchange filing · Aug 4, 2026
Changes to this page (v1 · Nov 6, 2026)
- v1 · Nov 6, 2026First version, through Q3 FY2026 (quarter ended Sep 30, 2026). (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.