Financials · NYSE: IBN
ICICI Bank: how the business works
ICICI Bank takes deposits and makes loans across India through 7,511 branches, and earned net profit of INR 542,077 million in FY2026 (year ended Mar 31, 2026).
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow ICICI Bank
Email me when ICICI Bank's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
ICICI Bank Limited · Mumbai, India · Founded 1994
Updated for Q2 FY2027 · checked
- Revenue (net interest income plus other income), FY2026
- INR 2,230,898 million
- Net profit, FY2026
- INR 542,077 million
- Gross loans, Mar 31, 2026
- INR 16,620,543 million
- Branches in India, Mar 31, 2026
- 7,511
- Group employees, Mar 31, 2026
- 174,666
The short version
ICICI Bank in 5 points
1 · What it sells
ICICI Bank takes deposits and makes loans across India through 7,511 branches, with INR 16,620,543 million of gross loans and INR 18,300,201 million of deposits at Mar 31, 2026.
2 · Who pays it
Of the money that came in during FY2026, interest from borrowers and bonds was 62.5%, insurance premiums 24.8%, fees and commissions 9.4% and investment gains and other income 3.3%.
3 · What it keeps from INR 100
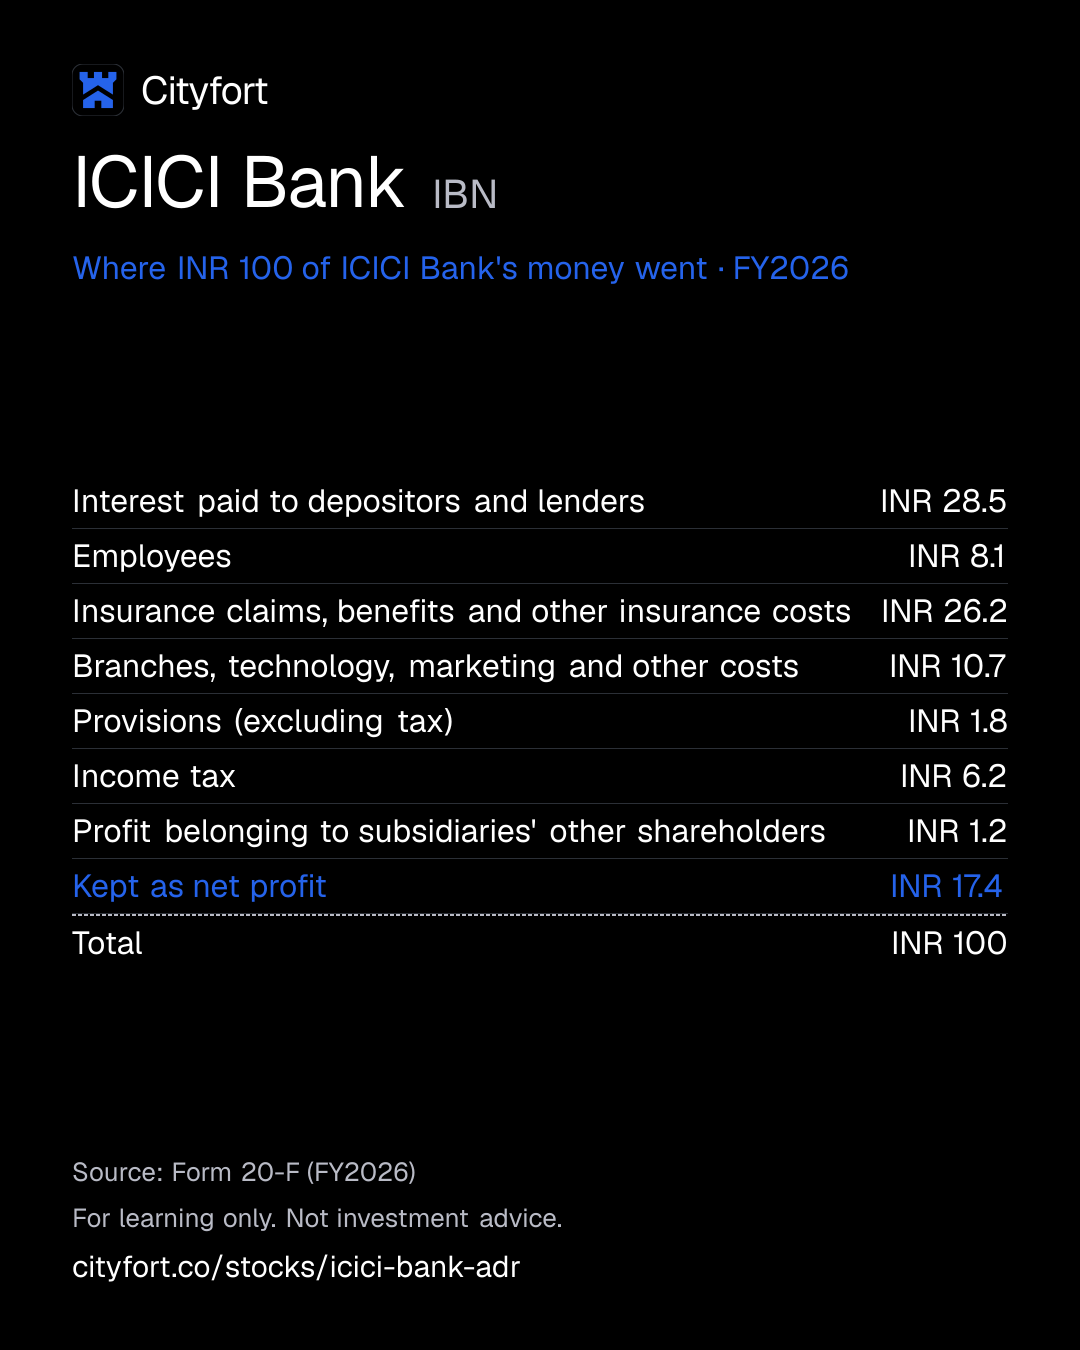
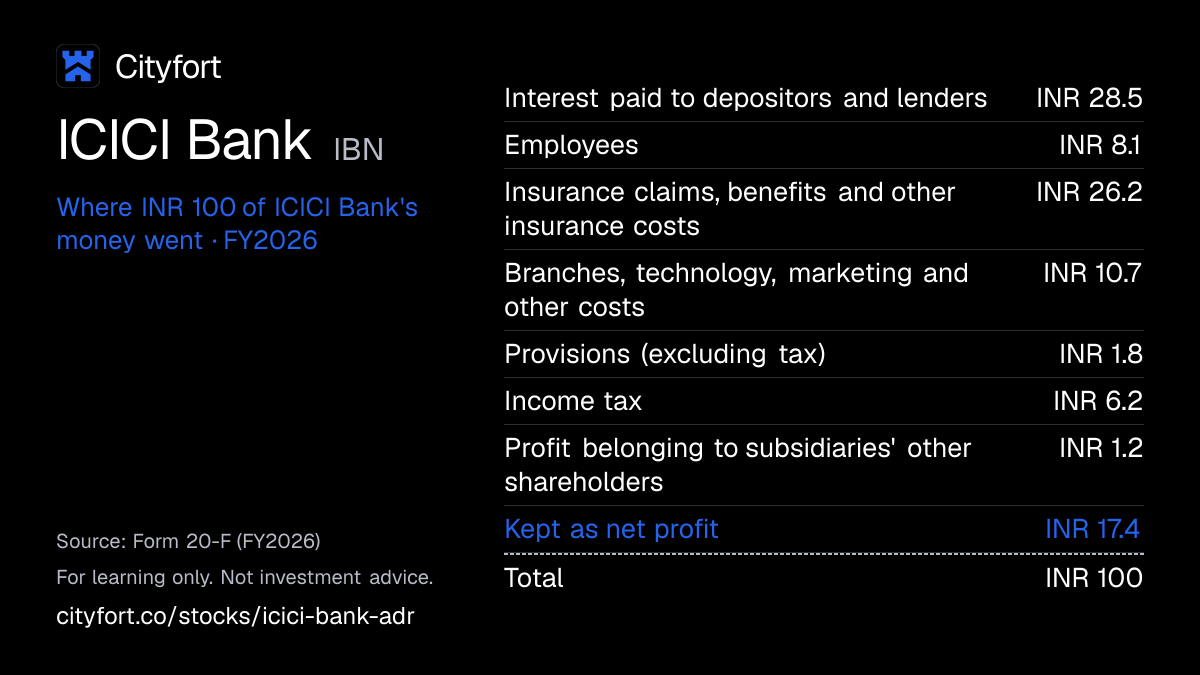
Of every INR 100 that came in during FY2026, ICICI Bank paid INR 28.5 in interest and INR 26.2 in insurance claims and costs, and kept INR 17.4 as net profit, with no large one-off gains.
4 · Where the operating profit comes from
Wholesale banking earned INR 244,890 million of ICICI Bank's FY2026 segment profit before tax, retail banking INR 232,442 million and treasury INR 172,509 million.
5 · The one thing to watch
Deposits rose 11.8% in Q2 FY2027 to INR 20,915,385 million at Sep 30, 2026, after the Bank raised foreign currency (FCNR (B)) deposits under an RBI swap facility.
Sources: From ICICI Bank's FY2026 Form 20-F and its Q2 FY2027 Form 6-K results · checked
Sources (3)
01Where INR 100 of a bank's money goes · FY2026
Where does INR 100 of ICICI Bank's money go?
ICICI Bank · FY2026
Receipt for every INR 100
| Interest paid to depositors and lenders | INR 28.5 |
|---|---|
| Employees | INR 8.1 |
| Insurance claims, benefits and other insurance costs | INR 26.2 |
| Branches, technology, marketing and other costs | INR 10.7 |
| Provisions (excluding tax) | INR 1.8 |
| Income tax | INR 6.2 |
| Profit belonging to subsidiaries' other shareholders | INR 1.2 |
| Kept as net profit | INR 17.4 |
| Total | INR 100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly INR 100 because of rounding.
How this is worked out
Cityfort calculation from the FY2026 20-F. Of every INR 100 that came in (interest earned of INR 1,952,185 million plus other income of INR 1,168,999 million plus the share of associates' profit of INR 2,629 million = INR 3,123,812 million): each line = line ÷ INR 3,123,812 million × 100. Provisions leave out income tax, which the 20-F's provisions line includes. Interest paid to depositors and lenders took INR 28.5 of every INR 100, insurance claims and costs INR 26.2, and INR 17.4 was kept as net profit.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report earnings, explained in 5 points.
No tips. Unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does ICICI Bank do?
People and companies in India deposit money with ICICI Bank, and it lends that money out. Interest paid to depositors and lenders is its biggest cost. In FY2026 it kept INR 17.4 of every INR 100 that came in as net profit.
- Insurance runs through the accounts: ICICI Lombard, a general insurer, became a subsidiary on Feb 29, 2024. Insurance premiums were INR 776,242 million of FY2026 other income of INR 1,168,999 million.
- Net profit rose from INR 251,101 million in FY2022 to INR 542,077 million in FY2026, under Indian GAAP as filed in the 20-F.
03Who pays it
Who pays ICICI Bank?
Borrowers and bond issuers (interest)
62.5%
of revenue
Interest on loans and on the bonds the bank holds: INR 1,952,185 million, 62.5% of the money that came in during FY2026
Insurance customers
24.8%
of revenue
Premiums and other income of the life and general insurers: INR 776,242 million, 24.8% of the money that came in during FY2026
Customers paying fees
9.4%
of revenue
Commission, exchange and brokerage on cards, accounts, loans and trading: INR 293,302 million, 9.4% of the money that came in during FY2026
Markets and other income
3.3%
of revenue
Gains on investments and foreign exchange, other income and the share of associates' profit: INR 102,083 million, 3.3% of the money that came in during FY2026
- Borrowers and bond issuers (interest)62.5%
- Insurance customers24.8%
- Customers paying fees9.4%
- Markets and other income3.3%
How spread out the customers are
Shares are of the INR 3,123,812 million that came in during FY2026 (Cityfort calculation from the FY2026 20-FThe annual report a foreign company listed in the US files with the SEC, in place of a 10-K. Learn more). The 20-F gives no income by customer. Its 20 largest borrowers were 4.2% of gross loans at Mar 31, 2026, and the largest 0.6%.
04How it makes money
How does ICICI Bank make money?
It earns the gap between loan and deposit interest, plus fees and insurance premiums
Deposits fund the loans, and the bank keeps the difference in interest, called the net interest margin. ICICI Bank's margin rose from 3.95% in FY2022 to 4.41% in FY2026; fees and its insurers add income on top.
Net interest margin, consolidated, as ICICI Bank reports it
4.0%4.4%
FY2022 to FY2026
- Collect deposits and borrow
- Lend to people and companies, and buy bonds
- Earn interest, fees and insurance premiums
- Pay interest, claims and running costs, and set money aside for bad loans
- Keep the rest as capital to lend again
↺ Step 5 feeds back into step 1.
05Business segments · FY2026
Which businesses make up ICICI Bank?
Wholesale banking
30.4%Loans and services for companies, firms, trusts and public bodies. Profit before tax of INR 244,890 million was 30.4% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 878,473M · Operating profit INR 244,890M
Retail banking
28.9%Loans, cards and deposits for individuals and small businesses. Profit before tax of INR 232,442 million was 28.9% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 1,623,942M · Operating profit INR 232,442M
Treasury
21.4%The bank's own bond and derivative holdings. Profit before tax of INR 172,509 million was 21.4% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 1,384,304M · Operating profit INR 172,509M
Others
10.4%Asset management, brokerage, home finance and pension fund subsidiaries. Profit before tax of INR 83,784 million was 10.4% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 199,701M · Operating profit INR 83,784M
General insurance
4.5%ICICI Lombard. Profit before tax of INR 36,590 million was 4.5% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 288,906M · Operating profit INR 36,590M
Life insurance
2.2%ICICI Life Insurance. Profit before tax of INR 18,077 million was 2.2% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 654,721M · Operating profit INR 18,077M
Other banking
2.1%Leasing, unallocated items and the banking subsidiaries in the UK and Canada. Profit before tax of INR 17,027 million was 2.1% of the seven segments' combined profit before tax, before an inter-segment deduction of INR 34,746 million.
Revenue INR 75,167M · Operating profit INR 17,027M
06The numbers · Consolidated · INR million
How has ICICI Bank done?
ICICI Bank files a Form 20-F each year and furnishes quarterly results on Form 6-KHow a foreign company listed in the US furnishes the SEC with reports it publishes at home, such as quarterly results. It is not a 10-Q. Learn more, as a foreign private issuerA non-US company that the SEC lets file a 20-F instead of a 10-K. It files no US proxy statement. Learn more. Its financial statements follow Indian GAAP, the basis of the primary financial statements in its 20-F and are reported in Indian rupees, shown here as filed in INR million (not converted to dollars). Quarterly figures: Indian GAAP, consolidated; unaudited with a limited review by the joint statutory auditors (Q4 is the audited year minus nine months), from results furnished on Form 6-K.
ICICI Bank's 20-F statements are consolidated Indian GAAP, in Indian rupees, with a reconciliation to US GAAP that this page does not show. Amounts are converted to INR million from the units the 20-F and the 6-Ks use; nothing is converted to dollars.
Net interest income
INR 1,061,899MFY2026
Net interest income rose every year, from INR 542,402 million in FY2022 to INR 1,061,899 million in FY2026, and was INR 303,356 million in Q2 FY2027.
INR million · interest earned minus interest paid
See the yearly numbers
See the quarterly numbers
Net income
INR 542,077MFY2026
Profit before provisions rose from INR 432,179 million in FY2022 to INR 826,962 million in FY2026, and net profit from INR 251,101 million to INR 542,077 million.
INR million · after the provision for credit losses and tax
See the yearly numbers
See the quarterly numbers
Net interest margin
4.41%FY2026
The consolidated net interest margin, as ICICI Bank reports it, rose from 3.95% in FY2022 to 4.53% in FY2024 and was 4.41% in FY2025 and FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
0.45%FY2026
Net loan write-offs were 0.45% of average gross loans in FY2026, against 1.09% in FY2022, and provisions held were 2.41% of gross loans at Mar 31, 2026.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the numbers
See all yearly numbers
Diluted EPS per equity share as filed (INR 74.77 in FY2026); quarterly EPS is for the quarter, not annualized. One ADS represents two equity shares, so FY2026 diluted EPS per ADS is INR 149.54 (Cityfort calculation from the FY2026 20-F).
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (Fiscal year ends on March 31).
- All figures are consolidated Indian GAAP from the 20-Fs (years) and the 6-K results (quarters). The 20-F's "Provisions and contingencies" line includes income tax; the provisions shown here leave tax out, and they cover investments, standard loans and contingencies, not only bad loans. FY2023 includes a contingency provision of INR 56,500.0 million made "on a prudent basis".
- ICICI Lombard became a subsidiary on Feb 29, 2024. From then, insurance premiums sit in other income (INR 776,241.9 million in FY2026) and insurance claims and other insurance costs in operating expenses (INR 818,363.6 million), which raises the efficiency ratio.
- Revenue on this page is net interest income plus other income (Cityfort calculation from the 20-Fs). The 20-F's own "total income" (INR 3,121,183.6 million in FY2026) counts interest earned before interest paid.
- Loans are total gross loans. The allowance is the 20-F's provisions held, including general provisions on standard loans. Non-performing loans were INR 234,273 million at Mar 31, 2026, 1.41% of gross loans, and specific provisions covered 73.98% of them.
- Net charge-offs are the 20-F's net loan write-offs: write-offs minus recoveries of loans written off earlier. The ratio to average gross loans is as reported.
- CET1 is the consolidated ratio under the RBI's Basel III rules, at year end. Net interest margin, the efficiency (cost-to-income) ratio, ROA and ROE are ICICI Bank's own reported consolidated ratios; it reports no return on tangible equity.
- Noninterest-bearing deposits are the 20-F's other demand deposits; their share of deposits (14.8% at Mar 31, 2026) is a Cityfort calculation. Quarterly margins and write-off ratios are blank: the 6-K results give no consolidated figures for them.
- Q4 quarters are the audited year minus the published nine months. Q4 other income is seasonally higher, mostly from insurance premiums. In Q2 FY2027 consolidated deposits rose 11.8% and net advances 11.9% from Jun 30, 2026. The Q2 FY2027 release gives the Bank's own (standalone) growth with and without FCNR (B) deposits raised under an RBI swap facility and the loans made against them.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100 · Fiscal years that don't end in December: Nvidia's FY2027 explained
Sources (9)
- Form 20-F for FY2024 (year ended March 31, 2024)
- Form 20-F for FY2023 (year ended March 31, 2023)
- Form 20-F for FY2022 (year ended March 31, 2022)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 20-F for FY2025 (year ended March 31, 2025)
- Form 6-K: Q3 FY2026 results (unaudited standalone and consolidated results for the quarter ended December 31, 2025, approved January 17, 2026)
- Form 6-K: Q4 FY2026 results (audited results for the year and quarter ended March 31, 2026, approved April 18, 2026)
- Form 6-K: Q1 FY2027 results (unaudited standalone and consolidated results for the quarter ended June 30, 2026, approved July 18, 2026)
- Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026)
07Who runs it
Who runs ICICI Bank, and did they deliver?
Sandeep Bakhshi
Managing Director and Chief Executive Officer · since 2018
CEO since Oct 15, 2018. Re-appointed for two years from Oct 4, 2026 to Oct 3, 2028, with RBI approval (May 22, 2026) and shareholder approval at the Aug 21, 2026 annual general meeting.
Pradeep Kumar Sinha
Non-executive Part-time Chairperson · since 2024
Independent director from Feb 17, 2024 for five years, and chairperson from Jul 1, 2024.
Sandeep Batra
Executive Director · since 2020
Whole-time director from Dec 23, 2020; current term to Dec 22, 2027.
Rakesh Jha
Executive Director · since 2022
Whole-time director from Sep 2, 2022; current term to Sep 1, 2027.
Ajay Kumar Gupta
Executive Director · since 2024
Whole-time director from Mar 15, 2024. Re-appointed for two years from Nov 27, 2026 to Nov 26, 2028, with RBI approval (Jul 31, 2026) and shareholder approval at the Aug 21, 2026 annual general meeting.
08What could go wrong
What could go wrong for ICICI Bank?
- Other
Bad loans
The 20-F says: "If the level of our non-performing assets increases and the overall quality of our loan portfolio deteriorates, our business will suffer." Non-performing loans were 1.41% of gross loans at Mar 31, 2026, down from 2.18% two years earlier.
Watch Non-performing loans and net loan write-offs in the next 20-F.
- Pricing
Interest rates
The 20-F says its banking and trading activities are "particularly vulnerable to interest rate risk", which could hurt its net interest margin and bond holdings. The margin was 4.41% in FY2026, against 4.53% in FY2024.
Watch Net interest margin in the FY2027 20-F.
- Cash and liquidity
Depositors may not roll over
The 20-F says: "Our funding is primarily short-term and if depositors do not roll over deposited funds upon maturity, our business could be adversely affected." Gross loans were 90.8% of deposits at Mar 31, 2026 (Cityfort calculation from the FY2026 20-F).
Watch Deposits against gross loans at each year end.
- Regulation
Capital rules
The Bank must meet the RBI's Basel III capital rules, and the 20-F says not keeping adequate capital "may impact our ability to grow and support our businesses". Its consolidated CET1 ratio was 16.25% at Mar 31, 2026, against a minimum of 8.20%.
Watch The CET1 ratio in each 20-F.
- Regulation
Regulators' fines and orders
The 20-F says: "We may be subject to fines, restrictions or other sanctions for regulatory compliance failures". The RBI fined the Bank twice in 2025, and directed an INR 12.8 billion provision on farm loans in FY2026.
Watch New penalties or directions, in the 20-F or on Form 6-K.
- Legal
Tax disputes
The 20-F says: "A determination against us in respect of disputed tax assessments may adversely impact our financial performance." Contingent tax liabilities not provided for were INR 148.5 billion at Mar 31, 2026.
Watch The GST notice of Sep 30, 2026 and the contingent tax liability in the FY2027 20-F.
- Regulation
Fee income
The 20-F says regulatory or market changes could make fee and foreign exchange income "decline and adversely impact our financial performance". Commission, exchange and brokerage were 25.1% of other income in FY2026 (Cityfort calculation from the FY2026 20-F).
Watch Commission, exchange and brokerage in the FY2027 20-F.
09Supporters vs. critics
What do supporters and critics point to?
What supporters point to
- Net profit rose every year, from INR 251,101 million in FY2022 to INR 542,077 million in FY2026.
- Non-performing loans fell from 2.18% of gross loans at Mar 31, 2024 to 1.41% at Mar 31, 2026.
- The consolidated CET1 ratio rose from 15.43% at Mar 31, 2024 to 16.25% at Mar 31, 2026.
- Commission, exchange and brokerage income rose 24.4% from FY2024 to INR 293,302 million in FY2026.
- Q2 FY2027 consolidated net profit was INR 163,332 million, up 22.3% from Q2 FY2026 (Cityfort calculation from the Q2 FY2027 6-K).
What critics point to
- Return on average equity fell from 18.98% in FY2024 to 15.90% in FY2026.
- Net profit rose 6.2% in FY2026, while gross loans grew 15.5% (Cityfort calculation from the FY2025 and FY2026 20-Fs).
- Provisions excluding tax rose from INR 37,124 million in FY2024 to INR 56,388 million in FY2026, including an RBI-directed provision on farm loans.
- The efficiency ratio (operating costs ÷ revenue) was 62.93% in FY2026; it includes insurance claims and costs.
- The Bank had INR 148.5 billion of contingent tax liabilities it had not provided for at Mar 31, 2026.
10What to watch next
What should you watch next at ICICI Bank?
Next event
Q3 FY2027 results (quarter ending Dec 31, 2026), furnished on Form 6-K
Date not announced yet.
The foreign currency deposits
Deposits rose 11.8% in Q2 FY2027 to INR 20,915,385 million at Sep 30, 2026, after the Bank raised foreign currency (FCNR (B)) deposits under an RBI swap facility.
LIC's approval to own up to 9.99%
The RBI approved Life Insurance Corporation of India on Sep 4, 2026 to acquire up to 9.99% of the Bank within one year; LIC held 4.4% at Jun 30, 2026.
Open tax and regulatory matters
The GST notice of Sep 30, 2026 for INR 2,291,435,396 plus interest and penalty, and the pending show cause notice from India's securities regulator.
11Key dates
What are the key dates for ICICI Bank?
| Event | Date | Source |
|---|---|---|
| Executive Director Ajay Kumar Gupta's new two-year term beginsRe-appointed to Nov 26, 2028, with approval from the RBI (Reserve Bank of India, the banking regulator) on Jul 31, 2026 and from shareholders at the Aug 21, 2026 annual general meeting. | Form 20-F for FY2026 (year ended March 31, 2026); Form 6-K: Outcome of the 32nd Annual General Meeting held on August 21, 2026; Form 6-K: RBI approval for the re-appointment of Ajay Kumar Gupta as Executive Director (filed August 3, 2026) | |
| Fiscal 2027 endsICICI Bank's fiscal year runs from Apr 1 to Mar 31. | Form 20-F for FY2026 (year ended March 31, 2026) | |
| Executive Director Rakesh Jha's term endsRe-appointed from Sep 2, 2025, per the FY2026 20-F. | Form 20-F for FY2026 (year ended March 31, 2026) | |
| Executive Director Sandeep Batra's term endsRe-appointed from Dec 23, 2025, per the FY2026 20-F. | Form 20-F for FY2026 (year ended March 31, 2026) | |
| CEO Sandeep Bakhshi's current term endsThe RBI approved his two-year re-appointment on May 22, 2026, and shareholders approved it at the Aug 21, 2026 annual general meeting. | Form 20-F for FY2026 (year ended March 31, 2026); Form 6-K: Outcome of the 32nd Annual General Meeting held on August 21, 2026 |
Learn: Fiscal years that don't end in December: Nvidia's FY2027 explained
12Key facts
Key facts about ICICI Bank
- What does ICICI Bank do?
- ICICI Bank is an Indian bank that takes deposits and makes loans; at Mar 31, 2026 it had 7,511 branches in India and INR 16,620,543 million of gross loans, according to its FY2026 Form 20-F.
- How does ICICI Bank make money?
- ICICI Bank earned INR 1,061,899 million of net interest income (interest earned minus interest paid) in FY2026, plus INR 1,168,999 million of other income, which includes INR 776,242 million of insurance premiums from its insurers.
- Who borrows from ICICI Bank?
- Retail loans to individuals were 51.3% of ICICI Bank's gross loans at Mar 31, 2026, down from 53.1% a year earlier; its 20 largest borrowers were 4.2% of gross loans, per the FY2026 20-F.
- How big is ICICI Bank?
- ICICI Bank reported consolidated net profit of INR 542,077 million under Indian GAAP in FY2026 (year ended Mar 31, 2026), up from INR 510,292 million in FY2025, and its group had 174,666 employees at Mar 31, 2026.
- Who owns ICICI Bank?
- No shareholder controls ICICI Bank: at Jun 30, 2026 the depositary for its ADSA certificate a US bank (the depositary) issues for shares of a foreign company that it holds. It trades in US dollars on a US exchange, and one may stand for more than one share. Learn more holders held 16.0% of the equity shares, SBI Mutual Fund 6.3% and Life Insurance Corporation of India 4.4%, per the FY2026 20-F.
- What is an ICICI Bank ADS?
- One ICICI Bank American depositary share (ADS), traded on the New York Stock Exchange as IBN since March 2000, represents two equity shares; the depositary is Deutsche Bank Trust Company Americas, per the FY2026 20-F.
- What is ICICI Bank's CET1 ratio?
- ICICI Bank's consolidated common equity tier 1 (CET1) capital ratio was 16.25% at Mar 31, 2026 under India's Basel III rules, against a minimum of 8.20%, per the FY2026 20-F.
- What did ICICI Bank earn in Q2 FY2027?
- ICICI Bank reported consolidated net profit of INR 163,332 million for Q2 FY2027 (quarter ended Sep 30, 2026), up from INR 133,571 million a year earlier, in results furnished on Form 6-K.
Go deeper
More detail from the same filings. Open any section.
13What it sells
13What it sells
What does ICICI Bank sell?
Deposit accounts
Savings, term and other deposits: INR 18,300,201 million at Mar 31, 2026, of which INR 2,717,034 million paid no interest.
Loans to people
Retail loans, such as home, vehicle, personal and card loans, were 51.3% of gross loans at Mar 31, 2026.
Loans and services for companies
Wholesale banking lends to companies, partnership firms, trusts and public bodies, and earned the most segment profit in FY2026.
Life and general insurance
ICICI Life Insurance (formerly ICICI Prudential Life) and ICICI Lombard are subsidiaries; their premiums and claims sit in the Bank's consolidated accounts.
Funds, home loans and brokerage
Other subsidiaries include ICICI Prudential Asset Management (mutual funds), ICICI Home Finance and ICICI Securities (share trading).
What it does
- Does: Takes deposits from people and companies
- Does: Lends to individuals, small businesses and companies
- Does: Sells life and general insurance through subsidiaries
- Does: Runs branches abroad, including New York, Singapore and Hong Kong
What it does not do
- Does not: Have a controlling shareholder: the largest holder at Jun 30, 2026 was the ADS depositary, with 16.0%
- Does not: Report its 20-F statements under US GAAP: they use Indian GAAP, with a reconciliation
14How the money flows
14How the money flows · FY2026
How does money flow through ICICI Bank?
Money in
- Interest earned on loans and investmentsINR 1,952,185M
- Insurance premiums and other insurance incomeINR 776,242M
- Commission, exchange and brokerageINR 293,302M
- Investment and foreign exchange gains, other income and share of associates' profitINR 102,083M
The company
ICICI Bank
INR 3,123,812M came in
Money out
- Interest paid to depositors and lendersINR 890,286M
- EmployeesINR 252,586M
- Insurance claims, benefits and other insurance costsINR 818,364M
- Branches, technology, marketing and other costsINR 332,986M
- Provisions (excluding tax)INR 56,388M
- Income taxINR 193,839M
- Profit belonging to subsidiaries' other shareholdersINR 37,286M
- Net profit for ICICI Bank's shareholdersINR 542,077M
- People and companies deposit money; ICICI Bank paid INR 890,286 million of interest to depositors and lenders in FY2026.
- It lends the money out and buys bonds, earning INR 1,952,185 million of interest.
- Its insurers collected INR 776,242 million of premiums and other income, and fees brought INR 293,302 million.
- Insurance claims and costs of INR 818,364 million come out, then staff and branch costs and INR 56,388 million of provisions.
- After income tax and the profit belonging to subsidiaries' other shareholders, INR 542,077 million was left for ICICI Bank's shareholders.
15Where growth could come from
15Where growth could come from
Where could ICICI Bank's growth come from?
This page shows reported results only and quotes no company forecast of loans, revenue or profit.
More loans
WorkingGross loans up 15.5% in FY2026
Gross loans rose from INR 14,389,294 million at Mar 31, 2025 to INR 16,620,543 million a year later; deposits rose 11.5% (Cityfort calculation from the FY2025 and FY2026 20-Fs).
Status: Working, on track against what the company said.
Insurance subsidiaries
WorkingINR 776,242 million of insurance premiums and income, FY2026
Insurance income rose from INR 458,528 million in FY2024, when ICICI Lombard joined. Life insurance profit before tax rose from INR 13,364 million in FY2025 to INR 18,077 million in FY2026; general insurance from INR 33,213 million to INR 36,590 million.
Status: Working, on track against what the company said.
Fees and commissions
WorkingINR 293,302 million, FY2026
Commission, exchange and brokerage income rose 24.4% from INR 235,719 million in FY2024 (Cityfort calculation from the FY2026 20-F).
Status: Working, on track against what the company said.
Foreign currency deposits from non-resident Indians
NewDeposits INR 20,915,385 million, Sep 30, 2026
Under an RBI swap facility the Bank raised about 17.88 billion US dollars of FCNR (B) deposits by Aug 31, 2026, provisional and unaudited. Consolidated deposits rose 11.8% in Q2 FY2027 (Cityfort calculation from the Q2 FY2027 6-K).
Status: New, recently announced.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
Sources (4)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 20-F for FY2025 (year ended March 31, 2025)
- Form 6-K: FCNR (B) deposit mobilisation under the RBI swap facility, up to August 31, 2026
- Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026)
16Financial strength: capital, loan losses, deposits
16Financial strength · FY2026
How strong is ICICI Bank's balance sheet?
- Loans madeINR 16,620,543M
- Deposits takenINR 18,300,201M
- of which pay no interestINR 2,717,034M
Loans were 90.8% of deposits at the end of FY2026 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 14.8% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 16.25%
- common equity capital as a share of risk-weighted assets (Consolidated, India's Basel III (RBI)); regulators set a minimum
- Allowance for credit losses
- INR 400,090M
- money set aside for expected loan losses: 2.41% of loans
- Net charge-offs
- INR 61,244M
- loans written off, minus recoveries: 0.45% of average loans
- Efficiency ratio
- 62.93%
- INR of noninterest expense per INR 100 of revenue (net interest income + noninterest income)
- Return on assets
- 2.02%
- net income as % of average total assets
- Return on equity
- 15.9%
- net income as % of average common equity
Figures at the end of FY2026, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
17Who owns it
17Who owns it · ownership as of Jun 30, 2026
Who owns ICICI Bank?
- Officers and directors (as a group), shares
- 0.0%
Share classes
Holders of 5% or more
One American depositary share (ADS) represents two equity shares. Deutsche Bank Trust Company Americas is the depositary, and the ADSs trade on the New York Stock Exchange. Each ADS holder owns the shares through the depositary, so the ADSs are not a separate share class.
From the company's annual report on Form 20-F (Items 6.E and 7.A), later Schedule 13G filings and the share count in that report. Each holder row shows the date of its own filing.
Insider trades · Form 4 data as of Nov 18, 2026
What did ICICI Bank's insiders report trading?
ICICI Bank's insiders made 12 Form 4A filing an insider must make within two business days of buying or selling the company's shares. Learn more filings in the 12 months to Nov 18, 2026.
They reported no purchases and 4 sales (204,999 shares) in the open market or privately (codes P and S).
None of the sales were on forms with the Rule 10b5-1 plan box checked.
The same filings report 13 other share transactions (M: 13).
They also report 14 transactions in options, stock units or other derivatives.
Insiders are a company's officers, directors and owners of more than 10% of a class of its shares. Most changes in their holdings must be reported to the SEC on a Form 4 within two business days. Source: SEC Form 4 filings on EDGAR.
- P
- a purchase in the open market or privately
- S
- a sale in the open market or privately
- M
- exercise or conversion of an option or other derivative, exempt under Rule 16b-3
Code meanings: General Instruction 8 of Form 4 (SEC).
All 17 transactions
Shares: A = acquired, D = disposed of. A price the filing gives only in a footnote shows as “See filing”. The 10b5-1 box is checked when at least one trade on the form was made under a Rule 10b5-1 plan. A Form 4/A replaces the form it amends. See all of ICICI Bank's Form 4 filings on EDGAR.
Learn: Form 4 insider filings: who files, the codes and the footnotes · Rule 10b5-1 trading plans: how insiders pre-schedule their trades
18What it does with profit
18What it does with profit
What does ICICI Bank do with its profit?
Dividend per share
INR 12.00FY2026
Dividend paid for each share, by financial year.
INR per share
See the numbers
Money raised · Aug 31, 2026
Raised about 3.55 billion US dollars through US dollar bonds in July and August 2026 (provisional and unaudited, per a Form 6-K). Moody's (Baa3) and S&P (BBB) rated the 500 million US dollar senior unsecured notes, the Bank said in a 6-K filed Sep 2, 2026. The amount is in US dollars as filed, so no INR figure is shown.
Sources (4)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 6-K: Outcome of the 32nd Annual General Meeting held on August 21, 2026
- Form 6-K: FCNR (B) deposit mobilisation under the RBI swap facility, up to August 31, 2026
- Form 6-K: Moody's and S&P ratings assigned to US$500 million senior unsecured notes (letters dated September 1, 2026)
19Governance signals
19Governance signals
What do ICICI Bank's governance filings show?
- Auditor
- KPMG Assurance and Consulting Services LLP, since 1999
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- This page does not summarize related-party transactions from the FY2026 20-F. Item 16F of the 20-F (changes in the registrant's certifying accountant) reads "Not Applicable". The Indian quarterly results are reviewed by joint statutory auditors B S R & Co. LLP and C N K & Associates LLP.
- Credit rating
- Moody's Ratings and S&P Global Ratings (ratings of the Bank's US dollar senior unsecured notes, as stated in a Form 6-K) Baa3 (Moody's) / BBB (S&P) (outlook Not stated (note ratings)), Sep 2, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
regulatory
Penalties from the RBI
The 20-F lists two penalties from the Reserve Bank of India (RBI), the banking regulator: INR 10 million (order of Apr 29, 2025, on its cybersecurity framework, know-your-customer rules, card issuance and conduct) and INR 8 million (order of Aug 7, 2025, on property valuation and the opening of current accounts). Both were paid.
regulatory
Show cause notice from India's securities regulator
A show cause notice from fiscal 2018 about compliance with listing rules, issued to the Bank and its former CEO, was revised in fiscal 2025. The 20-F says the revision "decoupled the Bank's matter from that of the Ex-Managing Director & CEO" and that "The matter is currently pending."
regulatory
Extra provision directed by the RBI
In FY2026 the Bank made an RBI-directed provision of INR 12.8 billion on farm loans the 20-F describes as "not fully compliant with the regulatory requirements for classification as agricultural priority sector lending".
regulatory
Tax demands
At Mar 31, 2026 the Bank had contingent tax liabilities of INR 148.5 billion that it had not provided for, the 20-F says. On Sep 30, 2026 it received a GST show cause notice demanding INR 2,291,435,396 plus interest and penalty on services to customers who keep minimum balances.
Sources (4)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026)
- Form 6-K: Moody's and S&P ratings assigned to US$500 million senior unsecured notes (letters dated September 1, 2026)
- Form 6-K: GST show cause notice received September 30, 2026 (Maharashtra, minimum-balance services)
20What the market paid
20What the market paid · price as of Nov 16, 2026
What did the market pay for ICICI Bank on Nov 16, 2026?
Price as of Nov 16, 2026 (shown for education; prices change daily).
ADS price (NYSE) as of Nov 16, 2026: $34.42, the closing price in Nasdaq.com's historical price table for IBN; the ADSs are listed on the New York Stock Exchange. One ADS represents two equity shares, so with 7,173,615,744 equity shares at Jun 30, 2026, the market value is about $123,458 million (Cityfort calculation from the Nov 16, 2026 closing price and the FY2026 20-F). No P/E, P/B or EV/EBITDA is shown: ICICI Bank reports earnings and equity in Indian rupees, so dividing them into a US-dollar price would mix two currencies.
- ADS price (NYSE)
- $34.42
- Market value (market cap)
- $123.5B
Source: IBN historical daily prices, Nov 2 to Nov 16, 2026 (Nasdaq.com table for the NYSE-listed ADS; close of Nov 16, 2026: $34.42); Form 20-F for FY2026 (year ended March 31, 2026)
21How it got here
21How it got here
How did ICICI Bank get here?
1994
Milestone
Bank set up
ICICI Bank was incorporated in 1994 as part of the ICICI group, whose parent began as a lender to Indian industry.
2000
Milestone
ADSs listed in New York
The ADSs were first issued in a public offering in March 2000 and trade on the New York Stock Exchange as IBN.
2002
Business-model change
Merger with ICICI
ICICI, the parent institution, and ICICI Bank merged in 2002.
2018
Milestone
Sandeep Bakhshi becomes CEO
He became Managing Director and CEO on Oct 15, 2018.
2024
Business-model change
ICICI Lombard becomes a subsidiary
The general insurer stopped being an associate and became a subsidiary on Feb 29, 2024, so its premiums and claims entered the Bank's accounts.
2025
Milestone
ICICI Securities fully owned
The brokerage became a wholly owned subsidiary and was delisted from the stock exchanges on Mar 24, 2025.
2026
Milestone
Foreign currency deposits under an RBI swap facility
The Bank raised about 17.88 billion US dollars of FCNR (B) deposits by Aug 31, 2026; consolidated deposits rose 11.8% in Q2 FY2027.
Sources (4)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 20-F for FY2024 (year ended March 31, 2024)
- Form 6-K: FCNR (B) deposit mobilisation under the RBI swap facility, up to August 31, 2026
- Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026)
22Sources and changes
Where every number on this page comes from
Sources (17 documents)
- S1Form 20-F for FY2026 (year ended March 31, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 20, 2026
- S2Form 20-F for FY2025 (year ended March 31, 2025) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 25, 2025
- S3Form 20-F for FY2024 (year ended March 31, 2024) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 31, 2024
- S4Form 20-F for FY2023 (year ended March 31, 2023) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 28, 2023
- S5Form 20-F for FY2022 (year ended March 31, 2022) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 29, 2022
- S6Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 22, 2026
- S7Form 6-K: Q1 FY2027 results (unaudited standalone and consolidated results for the quarter ended June 30, 2026, approved July 18, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 22, 2026
- S8Form 6-K: Q4 FY2026 results (audited results for the year and quarter ended March 31, 2026, approved April 18, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Apr 21, 2026
- S9Form 6-K: Q3 FY2026 results (unaudited standalone and consolidated results for the quarter ended December 31, 2025, approved January 17, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jan 22, 2026
- S10Form 6-K: Outcome of the 32nd Annual General Meeting held on August 21, 2026 · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Aug 25, 2026
- S11Form 6-K: Moody's and S&P ratings assigned to US$500 million senior unsecured notes (letters dated September 1, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Sep 2, 2026
- S12Form 6-K: FCNR (B) deposit mobilisation under the RBI swap facility, up to August 31, 2026 · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Sep 2, 2026
- S13Form 6-K: RBI approval for Life Insurance Corporation of India to hold up to 9.99% of the Bank (letter dated September 4, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Sep 8, 2026
- S14Form 6-K: GST show cause notice received September 30, 2026 (Maharashtra, minimum-balance services) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 1, 2026
- S15IBN historical daily prices, Nov 2 to Nov 16, 2026 (Nasdaq.com table for the NYSE-listed ADS; close of Nov 16, 2026: $34.42) · Nasdaq, Inc. · Tier 1: company or exchange filing · Nov 18, 2026
- S16EDGAR filing index for ICICI Bank Ltd (CIK 0001103838) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Nov 16, 2026
- S17Form 6-K: RBI approval for the re-appointment of Ajay Kumar Gupta as Executive Director (filed August 3, 2026) · ICICI Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Aug 3, 2026
Changes to this page (v1 · Nov 18, 2026)
- v1 · Nov 18, 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.