Financials · NYSE: HDB
HDFC Bank: how the business works
HDFC Bank takes deposits and makes loans across India through 9,689 branches, and earned net income of INR 704,793 million in FY2026 (year ended Mar 31, 2026).
By Hardik Bhandare · Checked against filings: . Editorial policy. Corrections
Follow HDFC Bank
Email me when HDFC Bank's page is updated after earnings.
We'll send a confirmation email first. See our privacy policy.
HDFC Bank Limited · Mumbai, India · Founded 1994
Updated for FY2026 · checked
- Revenue (net interest income plus noninterest revenue), FY2026
- INR 2,495,618 million
- Net income, FY2026
- INR 704,793 million
- Customers, Mar 31, 2026
- Over 100.6 million
- Branches, Mar 31, 2026
- 9,689
- Employees, Mar 31, 2026
- 211,178
The short version
HDFC Bank in 5 points
1 · What it sells
HDFC Bank takes deposits and makes loans across India through 9,689 branches, with INR 31,588,195 million of gross loans and INR 31,001,718 million of deposits at Mar 31, 2026.
2 · Who pays it
Retail banking brought 56.7% of FY2026 revenue, HDFC Life's insurance business 27.8%, wholesale banking for companies 11.0%, treasury 2.5% and other businesses 2.0%.
3 · What it keeps from INR 100
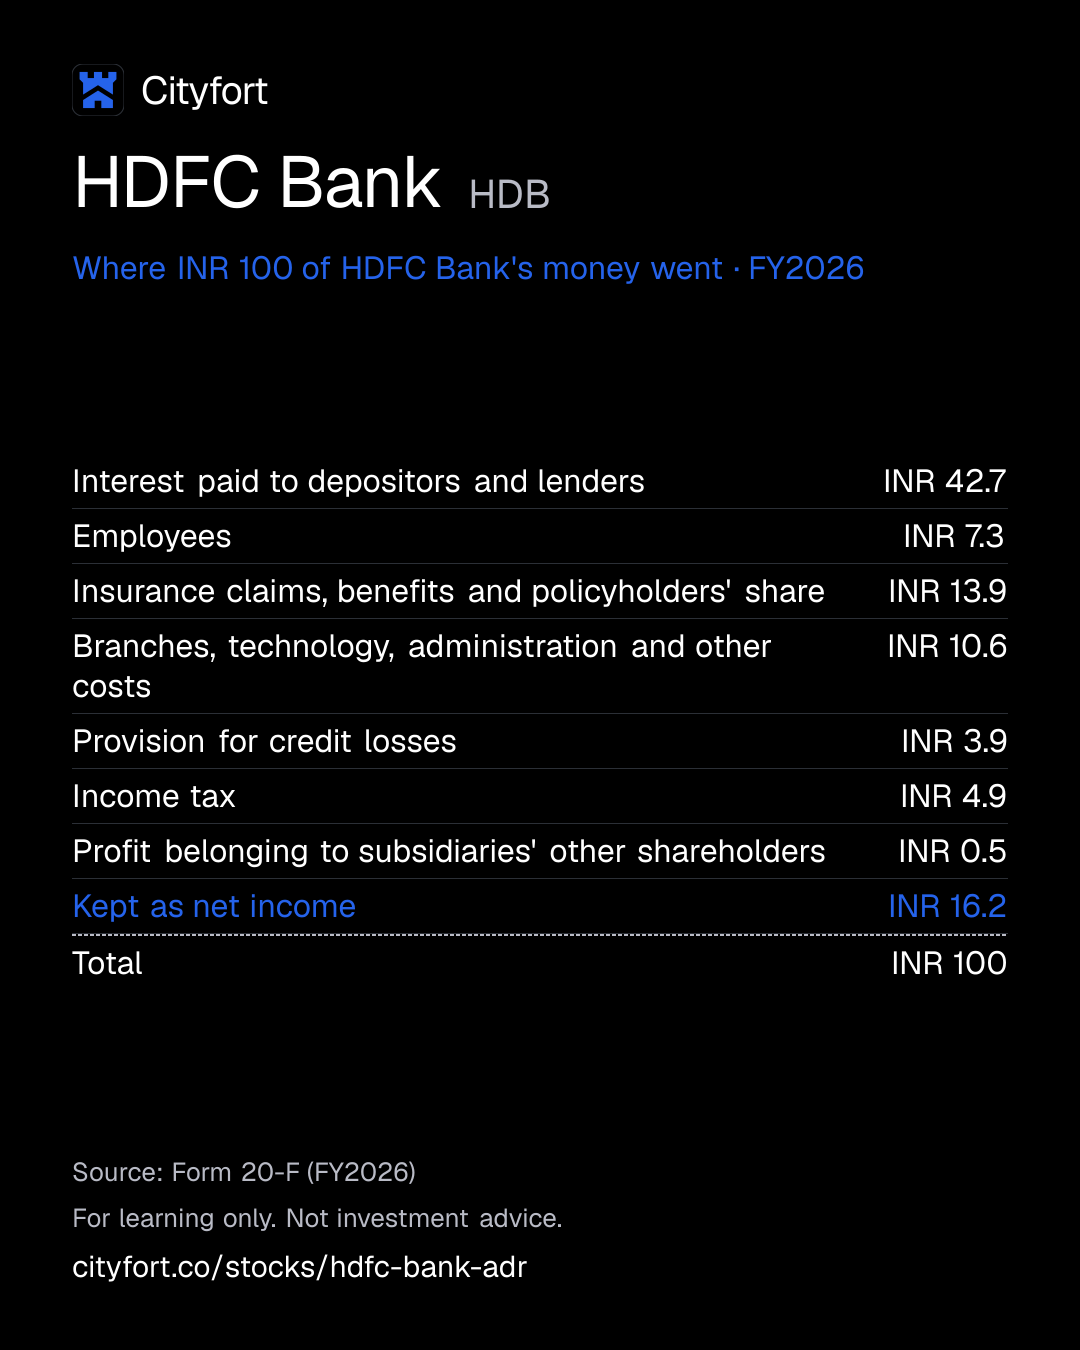
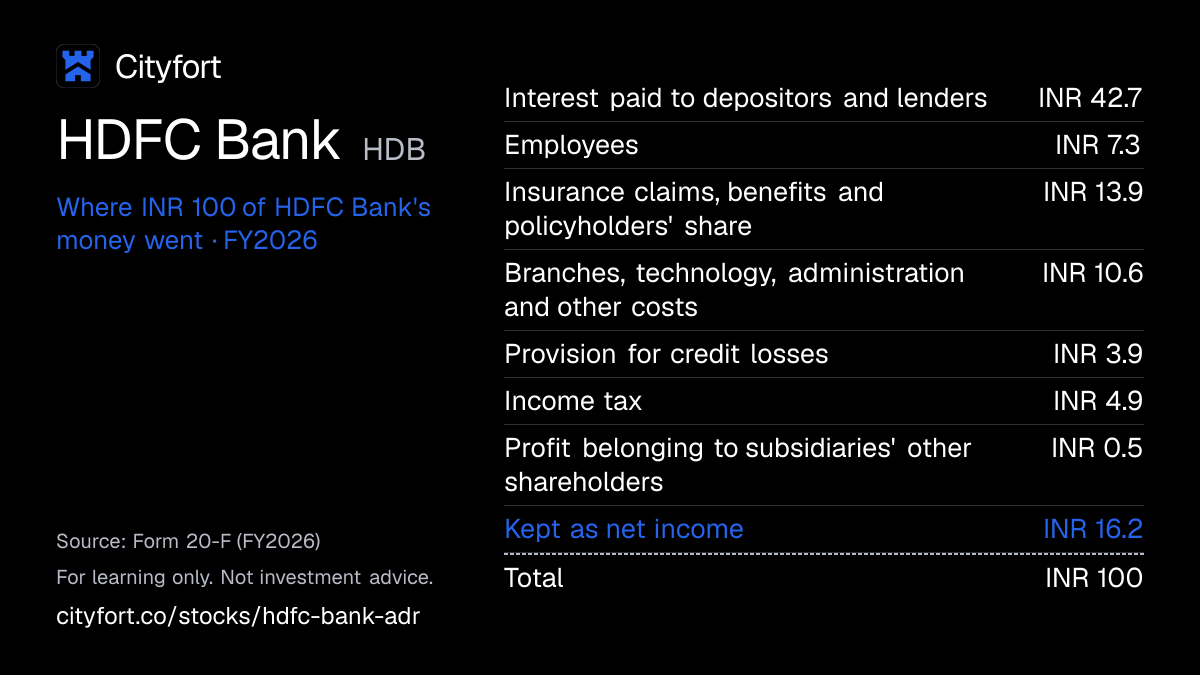
Of every INR 100 that came in during FY2026, HDFC Bank paid INR 42.7 in interest to depositors and lenders and kept INR 16.2 as net income, from an operating profit before credit losses of INR 1,144,090 million.
4 · Where the operating profit comes from
Retail banking earned INR 587,249 million of HDFC Bank's FY2026 income before tax, wholesale banking INR 223,122 million and treasury INR 59,575 million.
5 · The one thing to watch
Gross loans were 101.9% of deposits at Mar 31, 2026, down from 112.7% at Mar 31, 2024, the first year end after the merger.
Sources: From HDFC Bank's Form 20-Fs for FY2023 to FY2026 · checked
01Where INR 100 of a bank's money goes · FY2026
Where does INR 100 of HDFC Bank's money go?
HDFC Bank · FY2026
Receipt for every INR 100
| Interest paid to depositors and lenders | INR 42.7 |
|---|---|
| Employees | INR 7.3 |
| Insurance claims, benefits and policyholders' share | INR 13.9 |
| Branches, technology, administration and other costs | INR 10.6 |
| Provision for credit losses | INR 3.9 |
| Income tax | INR 4.9 |
| Profit belonging to subsidiaries' other shareholders | INR 0.5 |
| Kept as net income | INR 16.2 |
| Total | INR 100 |
Each line = amount ÷ total money in × 100. Lines may not add to exactly INR 100 because of rounding.
How this is worked out
Cityfort calculation from the FY2026 20-F. Of every INR 100 that came in (interest and dividend revenue of INR 3,360,265 million plus noninterest revenue of INR 995,848 million = INR 4,356,113 million): each line = line ÷ INR 4,356,113 million × 100. The policyholders' share is the INR 36,790 million surplus HDFC Life transferred to undistributed policyholders' earnings.
Save this receipt as an image
Embed this receipt or the key numbers
Paste this code into a blog or website to show the card you choose, with a link back to this page.
Each week: the next company due to report earnings, explained in 5 points.
No tips. Unsubscribe anytime.
We'll send a confirmation email. See our privacy policy.
02The business in one line
What does HDFC Bank do?
People and companies in India deposit money with HDFC Bank, and it lends it out, along with money it borrows. Interest paid to depositors and lenders is its biggest cost. In FY2026 it kept INR 16.2 of every INR 100 that came in as net income.
- Retail banking brought 56.7% of FY2026 revenue and the HDFC Life insurance business 27.8%, by the 20-F's segment figures (Cityfort calculation from the FY2026 20-F).
- HDFC Limited, which with its subsidiaries owned 20.83% of the Bank, merged into it on July 1, 2023; gross loans went from INR 17,418,092 million at Mar 31, 2023 to INR 31,588,195 million at Mar 31, 2026.
03Who pays it
Who pays HDFC Bank?
Retail banking customers
56.7%
of revenue
Interest on home, vehicle, card and small-business loans, plus account and card fees; home loans were INR 7,464,999 million of INR 23,581,443 million of retail loans at Mar 31, 2026
Life insurance customers
27.8%
of revenue
HDFC Life's premiums and the income on the money it invests
Companies (wholesale banking)
11%
of revenue
Interest on company loans and fees for banking services
Treasury
2.5%
of revenue
Income from the bank's own bond and money-market holdings
Other businesses
2%
of revenue
Businesses outside the four named segments, as the 20-FThe annual report a foreign company listed in the US files with the SEC, in place of a 10-K. Learn more groups them
- Retail banking customers56.7%
- Life insurance customers27.8%
- Companies (wholesale banking)11%
- Treasury2.5%
- Other businesses2%
How spread out the customers are
Shares are each segment's net interest income plus noninterest revenue in FY2026, divided by the total of INR 2,495,618 million (Cityfort calculation from the FY2026 20-F, note 28). The 20-F figures used for this page give no revenue for single customers.
04How it makes money
How does HDFC Bank make money?
It earns the gap between loan interest and deposit interest, and the merger changed that gap
Deposits fund the loans, and the bank keeps the difference in interest, called the net interest margin. After HDFC Limited's loans joined on July 1, 2023, loans exceeded deposits and the margin narrowed.
Net interest margin, as HDFC Bank reports it
4.4%3.6%
FY2023 to FY2026
- Collect deposits and borrow
- Lend to people and companies
- Earn interest and fees
- Pay interest and set aside money for bad loans
- Keep the rest as capital to lend again
↺ Step 5 feeds back into step 1.
05Business segments · FY2026
Which businesses make up HDFC Bank?
Retail banking
56.7%Accounts, cards and loans for people and small businesses; income before tax INR 587,249 million.
Revenue INR 1,415,320M · Operating profit INR 587,249M
Insurance services
27.8%HDFC Life; income before tax INR 39,806 million, after paying claims and the policyholders' share.
Revenue INR 692,566M · Operating profit INR 39,806M
Wholesale banking
11%Loans and services for companies; income before tax INR 223,122 million, helped by a net release of INR 10,546 million of provisions.
Revenue INR 273,757M · Operating profit INR 223,122M
Treasury
2.5%The bank's own bond and money-market holdings; income before tax INR 59,575 million.
Revenue INR 63,234M · Operating profit INR 59,575M
Others
2%Businesses other than the four named segments, as the 20-F groups them; income before tax INR 29,276 million.
Revenue INR 50,741M · Operating profit INR 29,276M
06The numbers · Consolidated · INR million
How has HDFC Bank done?
HDFC Bank files a Form 20-F each year and furnishes quarterly results on Form 6-KHow a foreign company listed in the US furnishes the SEC with reports it publishes at home, such as quarterly results. It is not a 10-Q. Learn more, as a foreign private issuerA non-US company that the SEC lets file a 20-F instead of a 10-K. It files no US proxy statement. Learn more. Its financial statements follow US GAAP and are reported in Indian rupees, shown here as filed in INR million (not converted to dollars).
HDFC Bank's 20-F statements are US GAAP, in Indian rupees, shown here in INR million as filed. FY2022 and FY2023 come before the July 1, 2023 merger with HDFC Limited; FY2024 includes it for nine months only.
Quarterly results are furnished on Form 6-K under Indian GAAP (unaudited) and are not shown beside the annual figures, which use US GAAP. Latest Form 6-K: Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026).
Net interest income
INR 1,499,770MFY2026
Net interest income rose from INR 748,840 million in FY2022 to INR 1,499,770 million in FY2026; FY2024 includes HDFC Limited from July 1, 2023 only, so the 20-F calls that year "not fully comparable".
* FY2024: Includes HDFC Ltd from Jul 1, 2023.
INR million · interest earned minus interest paid
See the numbers
Net income
INR 704,793MFY2026
Profit before credit losses rose from INR 646,142 million in FY2022 to INR 1,144,090 million in FY2026, and net income from INR 386,000 million to INR 704,793 million.
* FY2024: Includes HDFC Ltd from Jul 1, 2023.
INR million · after the provision for credit losses and tax
See the numbers
Net interest margin
3.6%FY2026
The net interest margin, as HDFC Bank reports it, fell from 4.4% in FY2023 to 3.8% in FY2024, the first year with HDFC Limited, and was 3.6% in FY2026.
% · net interest income as a share of the assets that earn interest, as reported by the company
See the numbers
Loans written off (net charge-offs)
0.4%FY2026
Net charge-offs were 0.4% of average loans in each year from FY2024 to FY2026, down from 0.8% in FY2022, and the allowance was 1.88% of gross loans at Mar 31, 2026.
* FY2024: Includes HDFC Ltd from Jul 1, 2023.
% of average loans · loans written off as unlikely to be repaid, minus amounts later recovered, as reported
See the numbers
See all yearly numbers
† Restated by the company. Diluted EPS per equity share, restated in the FY2026 20-F for the 1:1 bonus issue (record date Aug 27, 2025) for FY2024 onward; the 20-Fs give FY2022 and FY2023 EPS only before the bonus, so those years are blank. One ADS represents three equity shares; the 20-F states FY2026 diluted EPS per ADS of INR 137.25.
Net interest income = interest earned on loans and securities minus interest paid to depositors and lenders. Revenue (net of interest expense) = net interest income + noninterest income (fees and other income). Provision for credit losses = money set aside for loans that may not be repaid. Net income is the amount for common stockholders. Fiscal years are the company's own (Fiscal year ends on March 31).
- FY2022 and FY2023 come before the merger with HDFC Limited. The 20-F says FY2024 "includes the financial information of HDFC Limited and its former subsidiaries for the period from July 1, 2023 to March 31, 2024" and that "our consolidated financial information for the year ended March 31, 2024 is not fully comparable".
- Revenue on this page is net interest income plus noninterest revenue (Cityfort calculation from the 20-Fs). The 20-F's own "Total revenue, net" (INR 2,327,345 million in FY2026) subtracts the provision for credit losses.
- From FY2024 HDFC Life's premiums sit in noninterest revenue (INR 545,990 million in FY2026) and its claims and benefits in noninterest expense (INR 569,950 million). A further INR 36,790 million went to policyholders below noninterest expense, so profit before credit losses minus the provision is not income before tax.
- Noninterest revenue in FY2026 included INR 50,332 million of realized gains on securities sold, against INR 6,825 million in FY2025.
- Loans are gross loans, the base of the 20-F's allowance ratio. Net charge-offs are write-offs net of recoveries; the ratio to average loans is as reported. Non-performing loans, as the 20-F defines them under US GAAP, were 1.2% of gross loans at Mar 31, 2026 (INR 368,717 million) and 1.4% at Mar 31, 2022.
- CET1 is the Bank's own (bank level) ratio under the RBI's Basel III rules, at year end. The efficiency ratio is a Cityfort calculation (noninterest expense ÷ (net interest income + noninterest revenue)); it includes HDFC Life's claims from FY2024.
- ROA and ROE are Cityfort calculations from the 20-Fs: net income ÷ average total assets and ÷ average total shareholders' equity. From FY2024 HDFC Bank reports only returns on tangible assets and equity; ROTCE here is its return on average tangible equity, its own measure.
- Noninterest-bearing deposits are the 20-F's non-interest-bearing deposits at year end; their share of deposits (11.3% at Mar 31, 2026) is a Cityfort calculation.
Learn: What is net interest income and margin? NII and NIM at real US banks · How to read a US earnings release: Nvidia's Q2 fiscal 2027 · What a margin means: dollars kept per $100 · Fiscal years that don't end in December: Nvidia's FY2027 explained
07Who runs it
Who runs HDFC Bank, and did they deliver?
Anup Bagchi
Managing Director and Chief Executive Officer · since 2026
Took charge on Oct 27, 2026 for three years, after RBI approval and a Board decision on Oct 1, 2026. Shareholders approved by postal ballot with 98.646% of valid votes in favor, deemed passed Nov 6, 2026.
Rajiv Kumar
Part-Time Chairman · since 2026
Appointed an independent director from Jun 30, 2026, then Part-Time Chairman for three years from Jul 15, 2026, after RBI approval. Keki Mistry, interim chairman until that day, remains a non-executive director.
Kaizad Bharucha
Deputy Managing Director
In a letter of Oct 17, 2026 the Bank said he has requested to leave its service from the close of Dec 31, 2026.
Sashidhar Jagdishan
Former Managing Director and Chief Executive Officer · since 2020
CEO from October 2020 and with the Bank since 1996; he left office on Oct 26, 2026 on completing his tenure.
Sources (5)
- Form 6-K: Appointment of Anup Bagchi as Managing Director and CEO (RBI approval and Board decision of October 1, 2026)
- Form 6-K: Sashidhar Jagdishan vacates office; Anup Bagchi takes charge as Managing Director and CEO (October 27, 2026)
- Form 6-K: Postal ballot result, appointment of Anup Bagchi approved by shareholders (November 6, 2026)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 6-K: Disclosure of October 17, 2026 (independent director re-appointment; Deputy Managing Director to leave on December 31, 2026)
08What could go wrong
What could go wrong for HDFC Bank?
- Demand
India's economy
The 20-F says: "A slowdown in economic growth in India would cause us to experience slower growth in our asset portfolio and deterioration in the quality of our assets." Non-performing loans, as the 20-F defines them under US GAAP, were 1.2% of gross loans at Mar 31, 2026.
Watch The non-performing loan ratio and net charge-offs in the next 20-F.
- Pricing
Interest rates
The 20-F says HDFC Bank is "particularly vulnerable to interest rate risk", which could hurt its net interest margin and bond holdings. The margin was 3.6% in FY2026, down from 4.4% in FY2023.
Watch Net interest margin in the FY2027 20-F.
- Cash and liquidity
Depositors may not roll over
The 20-F says: "Our funding is primarily short- and medium-term, and if depositors do not roll over deposited funds upon maturity, our net income may decrease." Gross loans were 101.9% of deposits at Mar 31, 2026.
Watch Deposits against gross loans at each year end.
- Regulation
Capital rules
The Bank must keep a minimum capital adequacy ratio, and the 20-F says "limited access to the capital markets may prevent us from maintaining an adequate ratio". Its Tier I ratio was 17.73% at Mar 31, 2026, against an RBI minimum of 9.90%.
Watch The CET1 and Tier I ratios in each 20-F.
- Execution
Newer branches cost more to run
The 20-F says many branches, including some from the merger, are not yet as efficient as the rest, "which adversely affects our profitability". The efficiency ratio was 54.2% in FY2026, against 38.9% in FY2023 (Cityfort calculation from the FY2023 and FY2026 20-Fs; it includes insurance claims from FY2024).
Watch Noninterest expense against revenue in the FY2027 20-F.
- Governance
Reputation after the chairman's exit
The 20-F says: "Negative publicity could damage our reputation and adversely impact our business and financial results." It describes the part-time chairman's resignation of Mar 18, 2026 under this risk.
Watch Further board and senior management changes, announced on Form 6-K.
- Regulation
Regulators' actions
The 20-F says HDFC Bank has "previously been subjected to penalties" by the RBI, India's securities regulator and other authorities. Since Sep 25, 2025 its DIFC branch in Dubai may not take new clients for specified financial services.
Watch New penalties or a change to the Dubai restriction, in the 20-F or on Form 6-K.
- Currency
The rupee
HDFC Bank reports and pays dividends in rupees, which the depositary converts to US dollars for ADSA certificate a US bank (the depositary) issues for shares of a foreign company that it holds. It trades in US dollars on a US exchange, and one may stand for more than one share. Learn more holders. The 20-F says: "Except for a 2.8 percent appreciation in fiscal yearThe company's own 12-month year, which may not end in December. Learn more 2021 … the rupee has depreciated against the United States dollar each year since 2018".
Watch The rupee's rate against the US dollar.
09Supporters vs. critics
What do supporters and critics point to?
What supporters point to
- Net income rose every year, from INR 386,000 million in FY2022 to INR 704,793 million in FY2026.
- Net charge-offs were 0.4% of average loans in each year from FY2024 to FY2026, down from 0.8% in FY2022.
- The Bank's CET1 ratio rose from 16.30% at Mar 31, 2024 to 17.28% at Mar 31, 2026.
- Deposits rose 30.4% in the two years to Mar 31, 2026, faster than gross loans at 17.9% (Cityfort calculation from the FY2025 and FY2026 20-Fs).
- Dividends relating to FY2026 were INR 15.50 per share, against INR 11.00 for FY2025.
What critics point to
- The net interest margin fell from 4.4% in FY2023 to 3.6% in FY2026.
- Return on average equity was 9.06% in FY2026, against 18.75% in FY2023, as equity grew with the merger (Cityfort calculation from the FY2023 and FY2026 20-Fs).
- Net income rose 4.6% in FY2026 while income before tax rose 9.0%: the tax rate went from 20.3% to 22.6%, and the profit belonging to subsidiaries' other shareholders rose from INR 13,023 million to INR 22,303 million.
- The part-time chairman resigned on Mar 18, 2026, citing "happenings and practices" at the Bank that he said conflicted with his values.
- Since Sep 25, 2025 the Bank's Dubai branch may not take new clients for specified financial services.
10What to watch next
What should you watch next at HDFC Bank?
Next event
Q3 FY2027 results (quarter ending Dec 31, 2026), furnished on Form 6-K under Indian GAAP
Date not announced yet.
A new leadership team
Rajiv Kumar became Part-Time Chairman on Jul 15, 2026 and Anup Bagchi CEO on Oct 27, 2026; Deputy Managing Director Kaizad Bharucha has asked to leave from Dec 31, 2026, subject to RBI approval.
Loans against deposits
Gross loans were 101.9% of deposits at Mar 31, 2026, down from 112.7% two years earlier (Cityfort calculation from the 20-Fs).
The Dubai restriction
The DFSA's ban on new clients for specified financial services at the DIFC branch stays until the regulator amends or revokes it in writing.
11Key dates
What are the key dates for HDFC Bank?
| Event | Date | Source |
|---|---|---|
| Lily Vadera's new term as independent director beginsRe-appointed to Nov 25, 2029, subject to shareholders' approval. | Form 6-K: Disclosure of October 17, 2026 (independent director re-appointment; Deputy Managing Director to leave on December 31, 2026) | |
| Deputy Managing Director Kaizad Bharucha's requested exit dateHe requested to leave the Bank's service from the close of Dec 31, 2026; the Board forwarded the request to the RBI for approval. | Form 6-K: Disclosure of October 17, 2026 (independent director re-appointment; Deputy Managing Director to leave on December 31, 2026) | |
| RBI approval for the ICICI group to build a stake of up to 9.95% lapses if unusedThe approval lapses if the stake is not acquired by this date, the FY2026 20-F says. | Form 20-F for FY2026 (year ended March 31, 2026) | |
| Fiscal 2027 endsHDFC Bank's fiscal year runs from Apr 1 to Mar 31. | Form 20-F for FY2026 (year ended March 31, 2026) |
Learn: Fiscal years that don't end in December: Nvidia's FY2027 explained
12Key facts
Key facts about HDFC Bank
- What does HDFC Bank do?
- HDFC Bank is an Indian bank that takes deposits and makes loans; at Mar 31, 2026 it had 9,689 branches, over 100.6 million customers and INR 31,588,195 million of gross loans, according to its FY2026 Form 20-F.
- How does HDFC Bank make money?
- HDFC Bank earned INR 1,499,770 million of net interest income (interest earned minus interest paid) in FY2026, plus INR 995,848 million of noninterest revenue, which includes fees and its life insurer's premiums.
- Who are HDFC Bank's customers?
- Loans to individuals and small businesses (retail) were 74.7% of HDFC Bank's gross loans at Mar 31, 2026 and loans to companies (wholesale) 25.3% (Cityfort calculation from the FY2026 20-F).
- How big is HDFC Bank?
- HDFC Bank reported net income of INR 704,793 million under US GAAP in FY2026 (year ended Mar 31, 2026), up from INR 673,508 million in FY2025, and had 211,178 employees at Mar 31, 2026.
- Who owns HDFC Bank?
- No shareholder controls HDFC Bank: at Mar 31, 2026 the largest holder in the FY2026 20-F's shareholder table, SBI Nifty 50 ETF, held 6.46%, Life Insurance Corporation of India 4.04%, and its directors and their relatives 0.16%.
- What is an HDFC Bank ADS?
- One HDFC Bank American depositary share (ADS), traded on the New York Stock Exchange as HDB, represents three equity shares; the depositary is JPMorgan Chase Bank, N.A., per the FY2026 20-F.
- How did the HDFC Limited merger change HDFC Bank?
- HDFC Limited merged into HDFC Bank on July 1, 2023; HDFC Bank's total assets went from INR 25,755,624 million at Mar 31, 2023 to INR 44,118,573 million at Mar 31, 2024, and HDFC Life became its subsidiary.
- What is HDFC Bank's CET1 ratio?
- HDFC Bank's common equity tier 1 (CET1) capital ratio was 17.28% at Mar 31, 2026, at bank level under India's Basel III rules set by the Reserve Bank of India (RBI), per the FY2026 20-F.
Go deeper
More detail from the same filings. Open any section.
13What it sells
13What it sells
What does HDFC Bank sell?
Deposit accounts
Current and savings accounts and other deposits: INR 31,001,718 million at Mar 31, 2026, 58.9% of total liabilities and equity.
Loans to people and small businesses
Retail loans, including vehicle and equipment loans to small businesses, were 74.7% of gross loans at Mar 31, 2026; 26.3 million credit cards were outstanding.
Loans and services for companies
Wholesale banking loans were 25.3% of gross loans at Mar 31, 2026.
Life insurance
HDFC Life, 50.2% owned, sells life insurance; its premiums and claims sit in HDFC Bank's accounts from FY2024.
Funds, consumer loans and brokerage
Subsidiaries include HDFC AMC (mutual funds), HDB Financial Services (74.6% owned, a retail-lending subsidiary making mortgage, vehicle, consumer and gold loans) and HDFC Securities (94.3% owned, share trading).
What it does
- Does: Takes deposits from people and companies
- Does: Lends to individuals, small businesses and companies
- Does: Issues credit cards
- Does: Sells life insurance through HDFC Life
What it does not do
- Does not: Operate mainly outside India: the 20-F says substantially all its operations and assets are in India
- Does not: Control HDFC ERGO, a general insurer: it is a 50.3% joint venture, counted by the equity method
- Does not: Have a controlling shareholder since July 1, 2023
14How the money flows
14How the money flows · FY2026
How does money flow through HDFC Bank?
Money in
- Interest and dividends earned on loans and securitiesINR 3,360,265M
- Fees and commissionsINR 356,569M
- Insurance premiums and other insurance incomeINR 545,990M
- Trading, securities and other noninterest revenueINR 93,289M
The company
HDFC Bank
INR 4,356,113M came in
Money out
- Interest paid to depositors and lendersINR 1,860,496M
- EmployeesINR 318,595M
- Insurance claims, benefits and policyholders' shareINR 606,739M
- Branches, technology, administration and other costsINR 462,983M
- Provision for credit lossesINR 168,272M
- Income taxINR 211,932M
- Profit belonging to subsidiaries' other shareholdersINR 22,303M
- Net income for HDFC Bank's shareholdersINR 704,793M
- People and companies deposit money; HDFC Bank paid INR 1,860,496 million of interest to depositors and lenders in FY2026.
- It lends the money out and buys bonds, earning INR 3,360,265 million of interest and dividends.
- Fees brought INR 356,569 million, and HDFC Life's premiums and other insurance income INR 545,990 million.
- Insurance claims, staff and branch costs come out, plus INR 168,272 million set aside for loan losses.
- After income tax and the profit belonging to subsidiaries' other shareholders, INR 704,793 million was left for HDFC Bank's shareholders.
15Where growth could come from
15Where growth could come from
Where could HDFC Bank's growth come from?
The 20-F and the 6-K filings used for this page give no forecast of loans, revenue or profit.
Deposits catching up with loans
WorkingLoans 101.9% of deposits, Mar 31, 2026
Deposits rose 30.4% from Mar 31, 2024 to INR 31,001,718 million at Mar 31, 2026, while gross loans rose 17.9% (Cityfort calculation from the FY2025 and FY2026 20-Fs).
Status: Working, on track against what the company said.
Life insurance through HDFC Life
WorkingINR 545,990 million of insurance income, FY2026
Insurance premiums and other income rose from INR 381,880 million in FY2024; the insurance segment's income before tax rose from INR 20,548 million in FY2025 to INR 39,806 million in FY2026.
Status: Working, on track against what the company said.
Fees and commissions
WorkingINR 356,569 million, FY2026
Fees and commissions rose 26.9% from INR 280,966 million in FY2024.
Status: Working, on track against what the company said.
Newer branches
Early9,689 branches, Mar 31, 2026
The 20-F says many recently added branches, including some from the merger, "are not operating with the same efficiency as compared to the rest of our existing branches".
Status: Early, too early to judge.
Status compares progress with what the company itself said it would do: Working = on track against what the company said; Mixed = partly on track; Behind = behind the company's own plan; New = recently announced; Early = too early to judge.
16The company's own measures (non-GAAP)
16The company's own measures · FY2026
What do HDFC Bank's own measures show?
Official (US GAAP): Return on average equity, FY2026 (Cityfort calculation from the FY2026 20-F)
9.1%
Company's own measure: Return on average tangible equity, FY2026
12.4%
HDFC Bank's own ratio: net income divided by average equity after taking out goodwill and other intangible assets, mostly the INR 1,554,600 million of goodwill from the HDFC Limited merger.
Official (US GAAP): Return on average total assets, FY2026 (Cityfort calculation from the FY2026 20-F)
1.5%
Company's own measure: Return on average tangible assets, FY2026
1.6%
HDFC Bank's own ratio, on assets without goodwill and other intangibles.
Official (US GAAP): Efficiency ratio, FY2026 (Cityfort calculation from the FY2026 20-F)
54.2%
Company's own measure: Cost-to-net revenue ratio, FY2026
58.1%
HDFC Bank divides noninterest expense by net interest income after the provision for credit losses plus noninterest revenue; the efficiency ratio uses net interest income before the provision.
These are the company's own measures, defined by the company. They are not comparable across companies, and they are not added together. Each sits beside the nearest official (US GAAP) figure.
Learn: Non-GAAP measures: what a company's "adjusted" numbers leave out
17Financial strength: capital, loan losses, deposits
17Financial strength · FY2026
How strong is HDFC Bank's balance sheet?
- Loans madeINR 31,588,195M
- Deposits takenINR 31,001,718M
- of which pay no interestINR 3,504,126M
Loans were 101.9% of deposits at the end of FY2026 (Cityfort calculation from the reported totals: loans ÷ deposits).
Noninterest-bearing deposits, such as many checking accounts, were 11.3% of deposits (Cityfort calculation: noninterest-bearing deposits ÷ total deposits).
- CET1 capital ratio
- 17.28%
- common equity capital as a share of risk-weighted assets (Bank level, India's Basel III (RBI)); regulators set a minimum
- Allowance for credit losses
- INR 594,309M
- money set aside for expected loan losses: 1.88% of loans
- Net charge-offs
- INR 109,793M
- loans written off, minus recoveries: 0.4% of average loans
- Efficiency ratio
- 54.2%
- INR of noninterest expense per INR 100 of revenue (net interest income + noninterest income)
- Return on assets
- 1.46%
- net income as % of average total assets
- Return on equity
- 9.06%
- net income as % of average common equity
- Return on tangible common equity
- 12.4%
- the company's own measure (non-GAAP): equity without goodwill and other intangibles
Figures at the end of FY2026, consolidated, as reported by the company in its 10-K and earnings release; see the dates on each source.
Learn: What are net charge-offs? Loans written off, with real US companies · What is the allowance for credit losses? Loss reserves at US banks · What is the CET1 ratio? A bank's core capital, with real US companies · What is a bank efficiency ratio? Costs vs revenue, with real US banks · How to read a 10-K in 10 minutes
18Who owns it
18Who owns it · ownership as of Mar 31, 2026
Who owns HDFC Bank?
- Officers and directors (as a group), shares
- 0.2%
Share classes
Holders of 5% or more
One American depositary share (ADS) represents three equity shares. JPMorgan Chase Bank, N.A. is the depositary, and the ADSs trade on the New York Stock Exchange. Each ADS holder owns the shares through the depositary, so the ADSs are not a separate share class.
From the company's annual report on Form 20-F (Items 6.E and 7.A), later Schedule 13G filings and the share count in that report. Each holder row shows the date of its own filing.
Insider trades · Form 4 data as of Nov 17, 2026
What did HDFC Bank's insiders report trading?
HDFC Bank's insiders made 13 Form 4A filing an insider must make within two business days of buying or selling the company's shares. Learn more filings in the 12 months to Nov 17, 2026.
They reported no purchases and 4 sales (31,600 shares) in the open market or privately (codes P and S).
None of the sales were on forms with the Rule 10b5-1 plan box checked.
The same filings report 10 other share transactions (X: 10).
They also report 10 transactions in options, stock units or other derivatives.
Insiders are a company's officers, directors and owners of more than 10% of a class of its shares. Most changes in their holdings must be reported to the SEC on a Form 4 within two business days. Source: SEC Form 4 filings on EDGAR.
- P
- a purchase in the open market or privately
- S
- a sale in the open market or privately
- X
- exercise of an in-the-money or at-the-money derivative
Code meanings: General Instruction 8 of Form 4 (SEC).
All 14 transactions
Shares: A = acquired, D = disposed of. A price the filing gives only in a footnote shows as “See filing”. The 10b5-1 box is checked when at least one trade on the form was made under a Rule 10b5-1 plan. A Form 4/A replaces the form it amends. See all of HDFC Bank's Form 4 filings on EDGAR.
Learn: Form 4 insider filings: who files, the codes and the footnotes · Rule 10b5-1 trading plans: how insiders pre-schedule their trades
19What it does with profit
19What it does with profit
What does HDFC Bank do with its profit?
Dividend per share
INR 15.50FY2026
Dividend paid for each share, by financial year.
INR per share
See the numbers
Money raised · Aug 26, 2026
Issued 1,750 million US dollars of senior unsecured notes through its GIFT City branch, settled Aug 26, 2026: 500 million US dollars for 3 years at 5.159% and 1,250 million US dollars for 5 years at 5.401%. The amount is in US dollars as filed, so no INR figure is shown.
20Governance signals
20Governance signals
What do HDFC Bank's governance filings show?
- Auditor
- KPMG Assurance and Consulting Services LLP
- Auditor changes
- None in the period covered
- Audit qualifications
- None reported
- Related-party dealings
- This page does not summarize related-party transactions from the FY2026 20-F. Item 16F of the 20-F (changes in or disagreements with accountants) reads "Not Applicable".
- Credit rating
- Moody's and S&P (issuer ratings, as stated by HDFC Bank in a Form 6-K) Baa3 (Moody's) / BBB (S&P) (outlook Stable), Aug 24, 2026
A credit rating describes the company's ability to repay debt. It is not a rating of the share.
Flags to know about
other · Mar 18, 2026
Part-time chairman resigned
The 20-F says the part-time chairman resigned on Mar 18, 2026, stating that "certain happenings and practices within the Bank over the prior two years were not in congruence with his personal values and ethics". It says no specific allegations were raised, the RBI issued a statement supporting the Bank's governance, and an external legal review found his statement "not substantiated by the record reviewed and witness interviews".
regulatory · Sep 25, 2025
Dubai branch barred from taking new clients for specified financial services
On Sep 25, 2025 the Dubai Financial Services Authority (DFSA) prohibited the Bank's DIFC Branch "from, among other things, soliciting or conducting business with new clients for specified financial services". The 20-F says: "The prohibition does not affect servicing of existing customers and will remain in place until otherwise amended or revoked in writing by the DFSA."
regulatory
Penalties from Indian regulators
The 20-F lists RBI penalties of INR 10.0 million (Sep 10, 2024), INR 7.5 million (Mar 26, 2025, know-your-customer rules), INR 0.5 million (Jul 11, 2025, foreign exchange rules) and INR 9.1 million (Nov 28, 2025). It also lists an INR 0.9 million settlement with India's securities regulator (order of Feb 29, 2024), made without admitting or denying the findings.
other
Court cases linked to an old loan recovery
The Bank is recovering dues from Splendour Gems Limited and its guarantors; the 20-F says "outstanding dues remain substantially unpaid". It says: "On May 5, 2026, the Bombay High Court quashed a first information report alleging cheating, criminal breach of trust, and conspiracy against the Bank's Chief Executive Officer and Managing Director". It adds: "An appeal filed in the Supreme Court against the order of the Bombay High Court is pending adjudication."
disclosure
Quarterly results only under Indian GAAP
HDFC Bank furnishes its quarterly results on Form 6-K under Indian GAAP, with a limited review by its auditors; its US GAAP figures come once a year in the 20-F.
Sources (3)
- Form 20-F for FY2026 (year ended March 31, 2026)
- Form 6-K: Issue of US$1,750 million senior unsecured notes through the GIFT City branch (issuer ratings Baa3/BBB, stable)
- Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026)
21What the market paid
21What the market paid · price as of Nov 16, 2026
What did the market pay for HDFC Bank on Nov 16, 2026?
Price as of Nov 16, 2026 (shown for education; prices change daily).
ADS price (NYSE) as of Nov 16, 2026: $26.29, the closing price in Nasdaq.com's historical price table for HDB; the ADSs are listed on the New York Stock Exchange. One ADS represents three equity shares, so with 15,418,597,348 equity shares at the Oct 2, 2026 cut-off date of HDFC Bank's postal ballot, the market value is about $135,118 million (Cityfort calculation from the Nov 16, 2026 closing price and the Form 6-K filed Nov 10, 2026). No P/E, P/B or EV/EBITDA is shown: HDFC Bank reports earnings and equity in Indian rupees, so dividing them into a US-dollar price would mix two currencies.
- ADS price (NYSE)
- $26.29
- Market value (market cap)
- $135.1B
Source: HDB historical daily prices, Nov 2 to Nov 16, 2026 (Nasdaq.com table for the NYSE-listed ADS; close of Nov 16, 2026: $26.29); Form 6-K: Postal ballot result, appointment of Anup Bagchi approved by shareholders (November 6, 2026)
22How it got here
22How it got here
How did HDFC Bank get here?
1995
Milestone
Opened for business
Incorporated in August 1994, HDFC Bank began operations as a scheduled commercial bank in January 1995.
2020
Milestone
Sashidhar Jagdishan becomes CEO
He became Managing Director and CEO in October 2020, after joining the Bank in 1996.
2023
Business-model change
Merger with HDFC Limited
HDFC Limited, which with its subsidiaries owned 20.83% of the Bank, merged into it on July 1, 2023: 42 Bank shares for every 25 HDFC Limited shares. HDFC Life and other subsidiaries came with it.
2025
Milestone
HDB Financial Services listed
Its retail-lending subsidiary opened its IPO on Jun 25, 2025 and listed in India on Jul 2, 2025; the Bank sold INR 100,000 million of shares in the offer and held 74.6% at Mar 31, 2026.
2025
Milestone
One bonus share for each share
A 1:1 bonus issue with record date Aug 27, 2025 doubled the share count; one ADS still represents three equity shares.
2026
Crisis
Chairman resigns
The part-time chairman resigned on Mar 18, 2026; Rajiv Kumar became Part-Time Chairman on Jul 15, 2026, after RBI approval, according to the FY2026 20-F.
2026
Milestone
New CEO
Anup Bagchi took charge as Managing Director and CEO on Oct 27, 2026.
23Sources and changes
Where every number on this page comes from
Sources (13 documents)
- S1Form 20-F for FY2026 (year ended March 31, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 29, 2026
- S2Form 20-F for FY2025 (year ended March 31, 2025) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 14, 2025
- S3Form 20-F for FY2024 (year ended March 31, 2024) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jul 29, 2024
- S4Form 20-F for FY2023 (year ended March 31, 2023) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Jun 29, 2023
- S5Form 6-K: Q2 FY2027 results (unaudited standalone and consolidated results for the quarter ended September 30, 2026, approved October 17, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 19, 2026
- S6Form 6-K: Disclosure of October 17, 2026 (independent director re-appointment; Deputy Managing Director to leave on December 31, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 19, 2026
- S7Form 6-K: Appointment of Anup Bagchi as Managing Director and CEO (RBI approval and Board decision of October 1, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 2, 2026
- S8Form 6-K: Sashidhar Jagdishan vacates office; Anup Bagchi takes charge as Managing Director and CEO (October 27, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Oct 28, 2026
- S9Form 6-K: Postal ballot result, appointment of Anup Bagchi approved by shareholders (November 6, 2026) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Nov 10, 2026
- S10Form 6-K: Issue of US$1,750 million senior unsecured notes through the GIFT City branch (issuer ratings Baa3/BBB, stable) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Aug 24, 2026
- S11Form 6-K: RBI approval for Life Insurance Corporation of India to hold up to 9.99% of the Bank · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Aug 20, 2026
- S12HDB historical daily prices, Nov 2 to Nov 16, 2026 (Nasdaq.com table for the NYSE-listed ADS; close of Nov 16, 2026: $26.29) · Nasdaq, Inc. · Tier 1: company or exchange filing · Nov 17, 2026
- S13EDGAR filing index for HDFC Bank Ltd (CIK 0001144967) · HDFC Bank Limited (SEC EDGAR) · Tier 1: company or exchange filing · Nov 16, 2026
Changes to this page (v2 · Nov 18, 2026)
- v2 · Nov 18, 2026Reworded the profit-source point so every number in it is also shown on the page (the release build checks this). (editorial update, FY2026)
- v1 · Nov 17, 2026First version. (first version)
Numbers come only from tier 1 and tier 2 sources. Read how we research.
Disclaimer
For learning only. Cityfort is not a registered investment adviser or broker-dealer and does not recommend buying or selling any security. Prices shown are dated and may be out of date.
Investing in securities involves risk, including loss of capital. Before making any investment decision, do your own research and consider consulting a registered investment adviser or other qualified professional.
Cityfort, its owners and contributors may or may not hold securities of companies covered. Cityfort is not paid by any company it covers. Content is not an offer or solicitation to buy or sell any security, including in any initial public offering.
Read the positions policyRead the full disclaimerHide the full disclaimer
Cityfort publishes general educational content that explains how listed companies work. Cityfort is not registered with the US Securities and Exchange Commission or any state securities regulator as an investment adviser, and is not a broker-dealer or a member of FINRA. Cityfort does not provide investment, tax or legal advice, recommendations, ratings, price targets or any opinion on whether to buy, sell or hold any security. Nothing on the site is tailored to any person's circumstances.
All information is taken from publicly available sources, mainly company filings with the SEC, which are listed on each page with dates. We work to keep it accurate and correct errors publicly, but we do not guarantee that it is complete, accurate or up to date. Any market price or price-based ratio shown is dated, may be out of date by the time you read it, and is included only to explain concepts.
Statements by company management, including forward-looking statements and guidance, are reported as the company's statements, with their date and source; they are not our forecasts. Adjusted (non-GAAP) figures are the company's own measures and are shown next to the official (GAAP) figures.